

- Brent crude surges over 4% past 104 USD per barrel amid escalating Middle East tensions.
- Hurricane Isaias shuts in roughly a quarter of crude production in the Gulf of Mexico.
- US 10-year Treasury yields rise 5 bps to 5.35% as higher oil prices fuel inflation fears.
- European equities retreat broadly, with the Euro Stoxx 50 dropping 1.1% and the banking sector under pressure.
- Samsung shares slide nearly 2.5% despite reporting a record Q3 operating profit exceeding 100 trillion KRW.
- Gold climbs to approximately 4 120 USD per ounce, supported by inflation concerns and returning Chinese demand.
Thursday's trading session has been dominated by a sharp rebound in crude oil prices, triggering another wave of sell-offs across both equities and government bonds. Investors are once again focusing on escalating geopolitical risks and their inflationary repercussions.
Commodities
Brent crude is gaining over 4% today, breaking above $104 per barrel. WTI crude is recording a similar scale of advance, reaching nearly $92. The immediate catalyst behind the movement stems from reports challenging the previous assumption that the Donald Trump administration would refrain from escalating the conflict with Iran until the November mid-term elections.
Figure 1: Brent and WTI Crude Oil (2026)
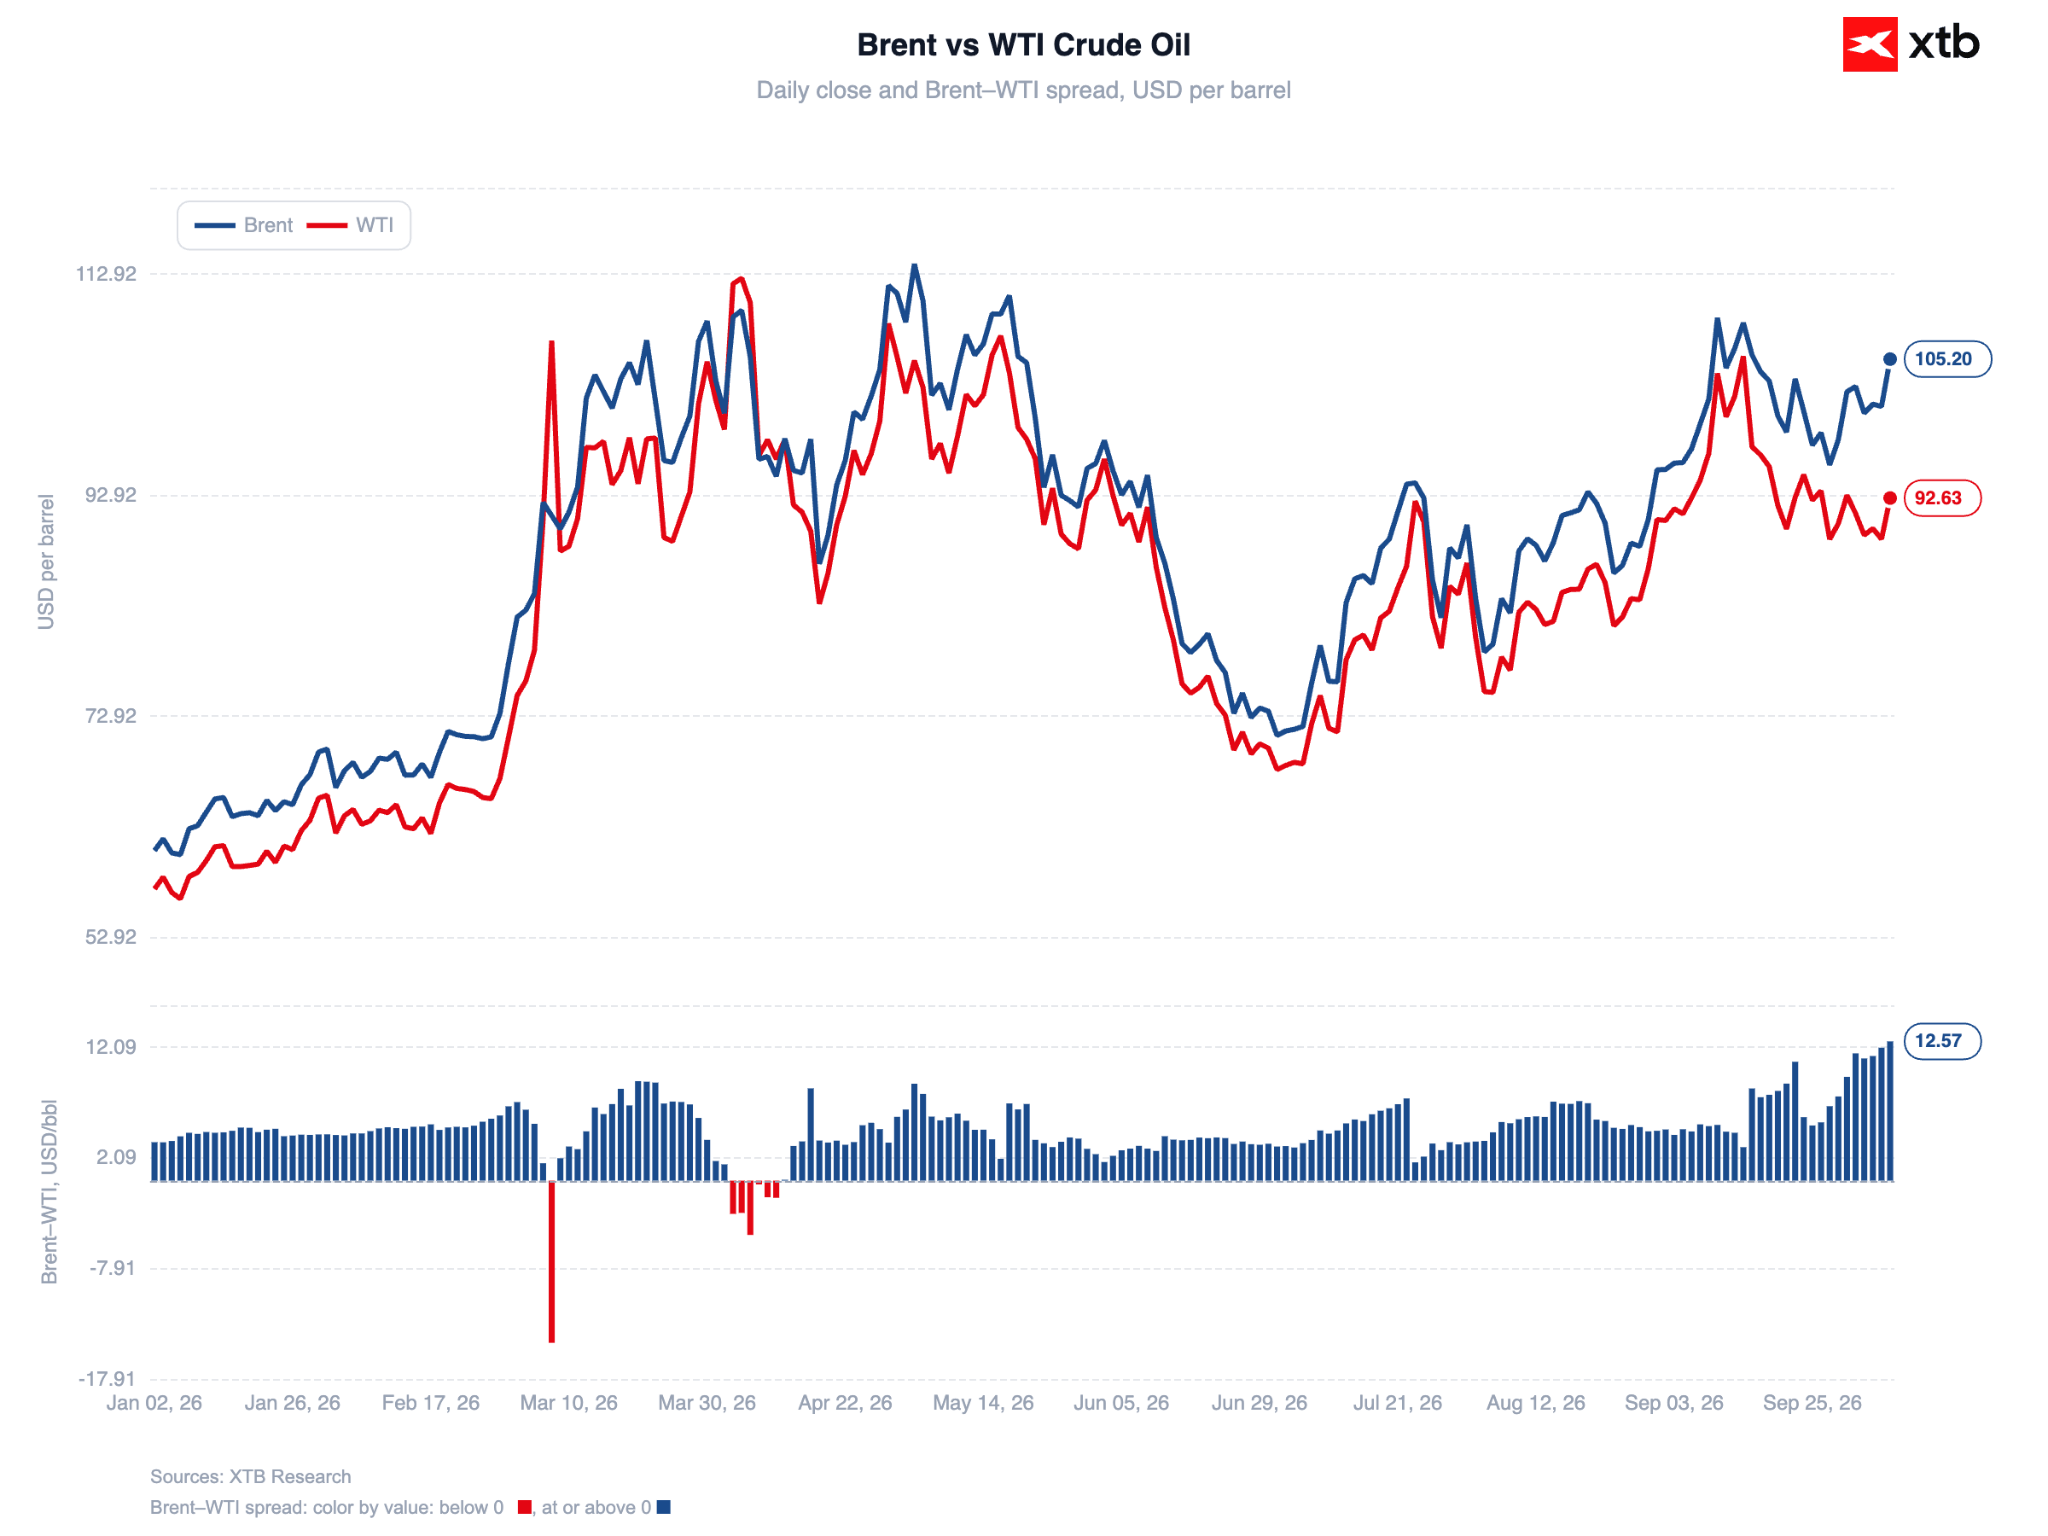 Source: XTB Research, 08.10.2026
Tensions are further exacerbated by renewed Houthi attacks; over the past two days, rebels struck two Saudi airports (in Riyadh and Abha), killing three people and injuring dozens more. Adding to supply-side risks is Hurricane Isaias, the first of the Atlantic season, which forced Gulf of Mexico producers to shut in approximately a quarter of crude oil output and around 16% of natural gas production. The storm is expected to intensify further, making landfall on the Louisiana and Texas coasts between Friday evening and Saturday.
Debt Market
Rising oil prices are feeding concerns over persistent inflation, driving a continued sell-off in sovereign bonds. The yield on US 10-year Treasuries is up around 5 bps to 5.35%. An even more dynamic movement is visible in French government bonds (+9 bps to 4.95%), a topic addressed in greater detail in yesterday's equity commentary.
Figure 2: WTI Crude Oil and US 10-Year Treasury Yields (2026)
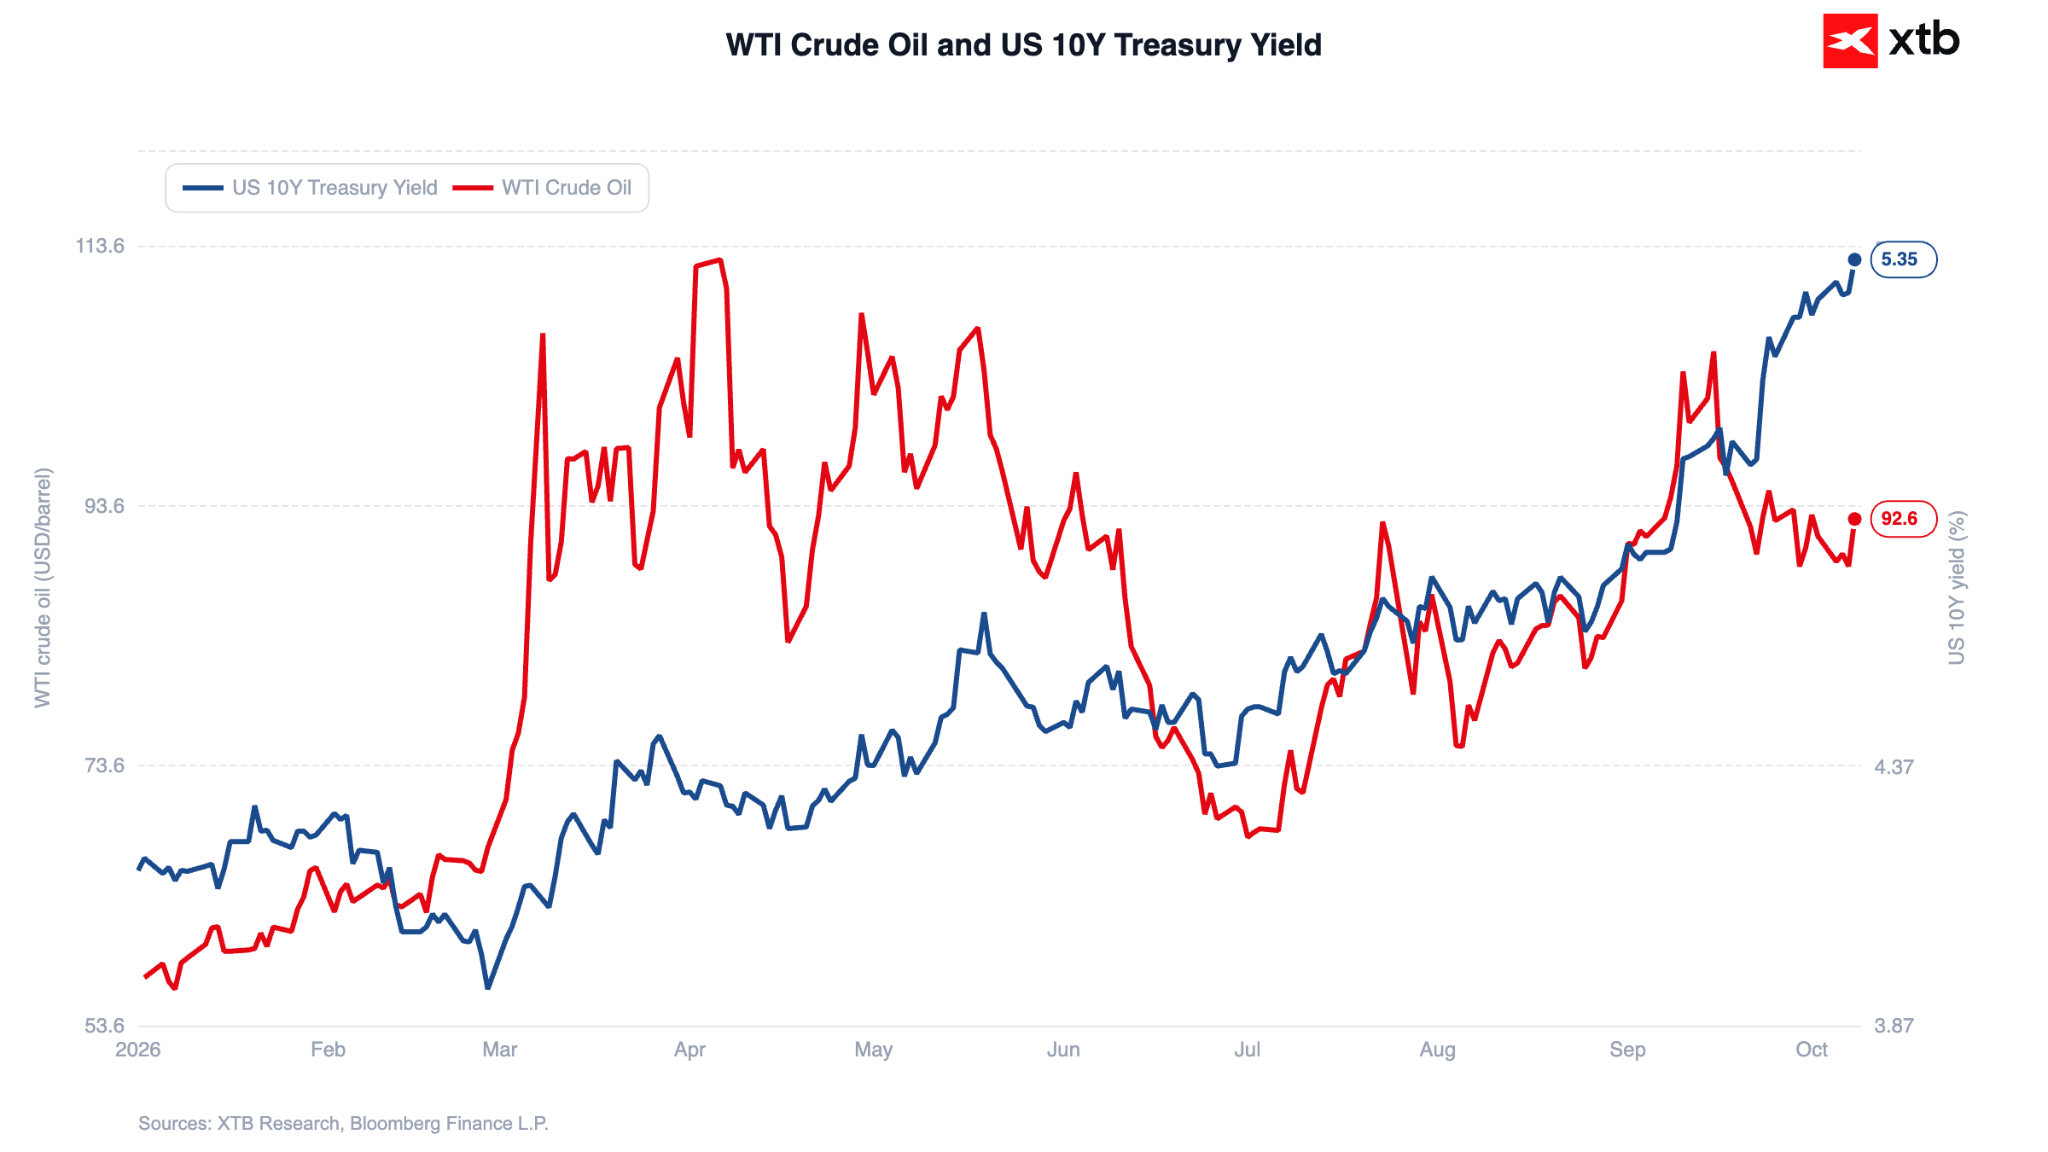 Source: XTB Research, 08.10.2026
Notably, as much as 38% of the entire pool of French high-grade corporate debt is currently trading at a lower yield than comparable government securities (compared to just €12 billion at the start of 2026). Investors view companies with robust, international revenue exposure, such as L'Oréal or TotalEnergies, as a safer haven than the French sovereign.
Figure 3: 10-Year Sovereign Yield Spread Between France and Germany (2026)
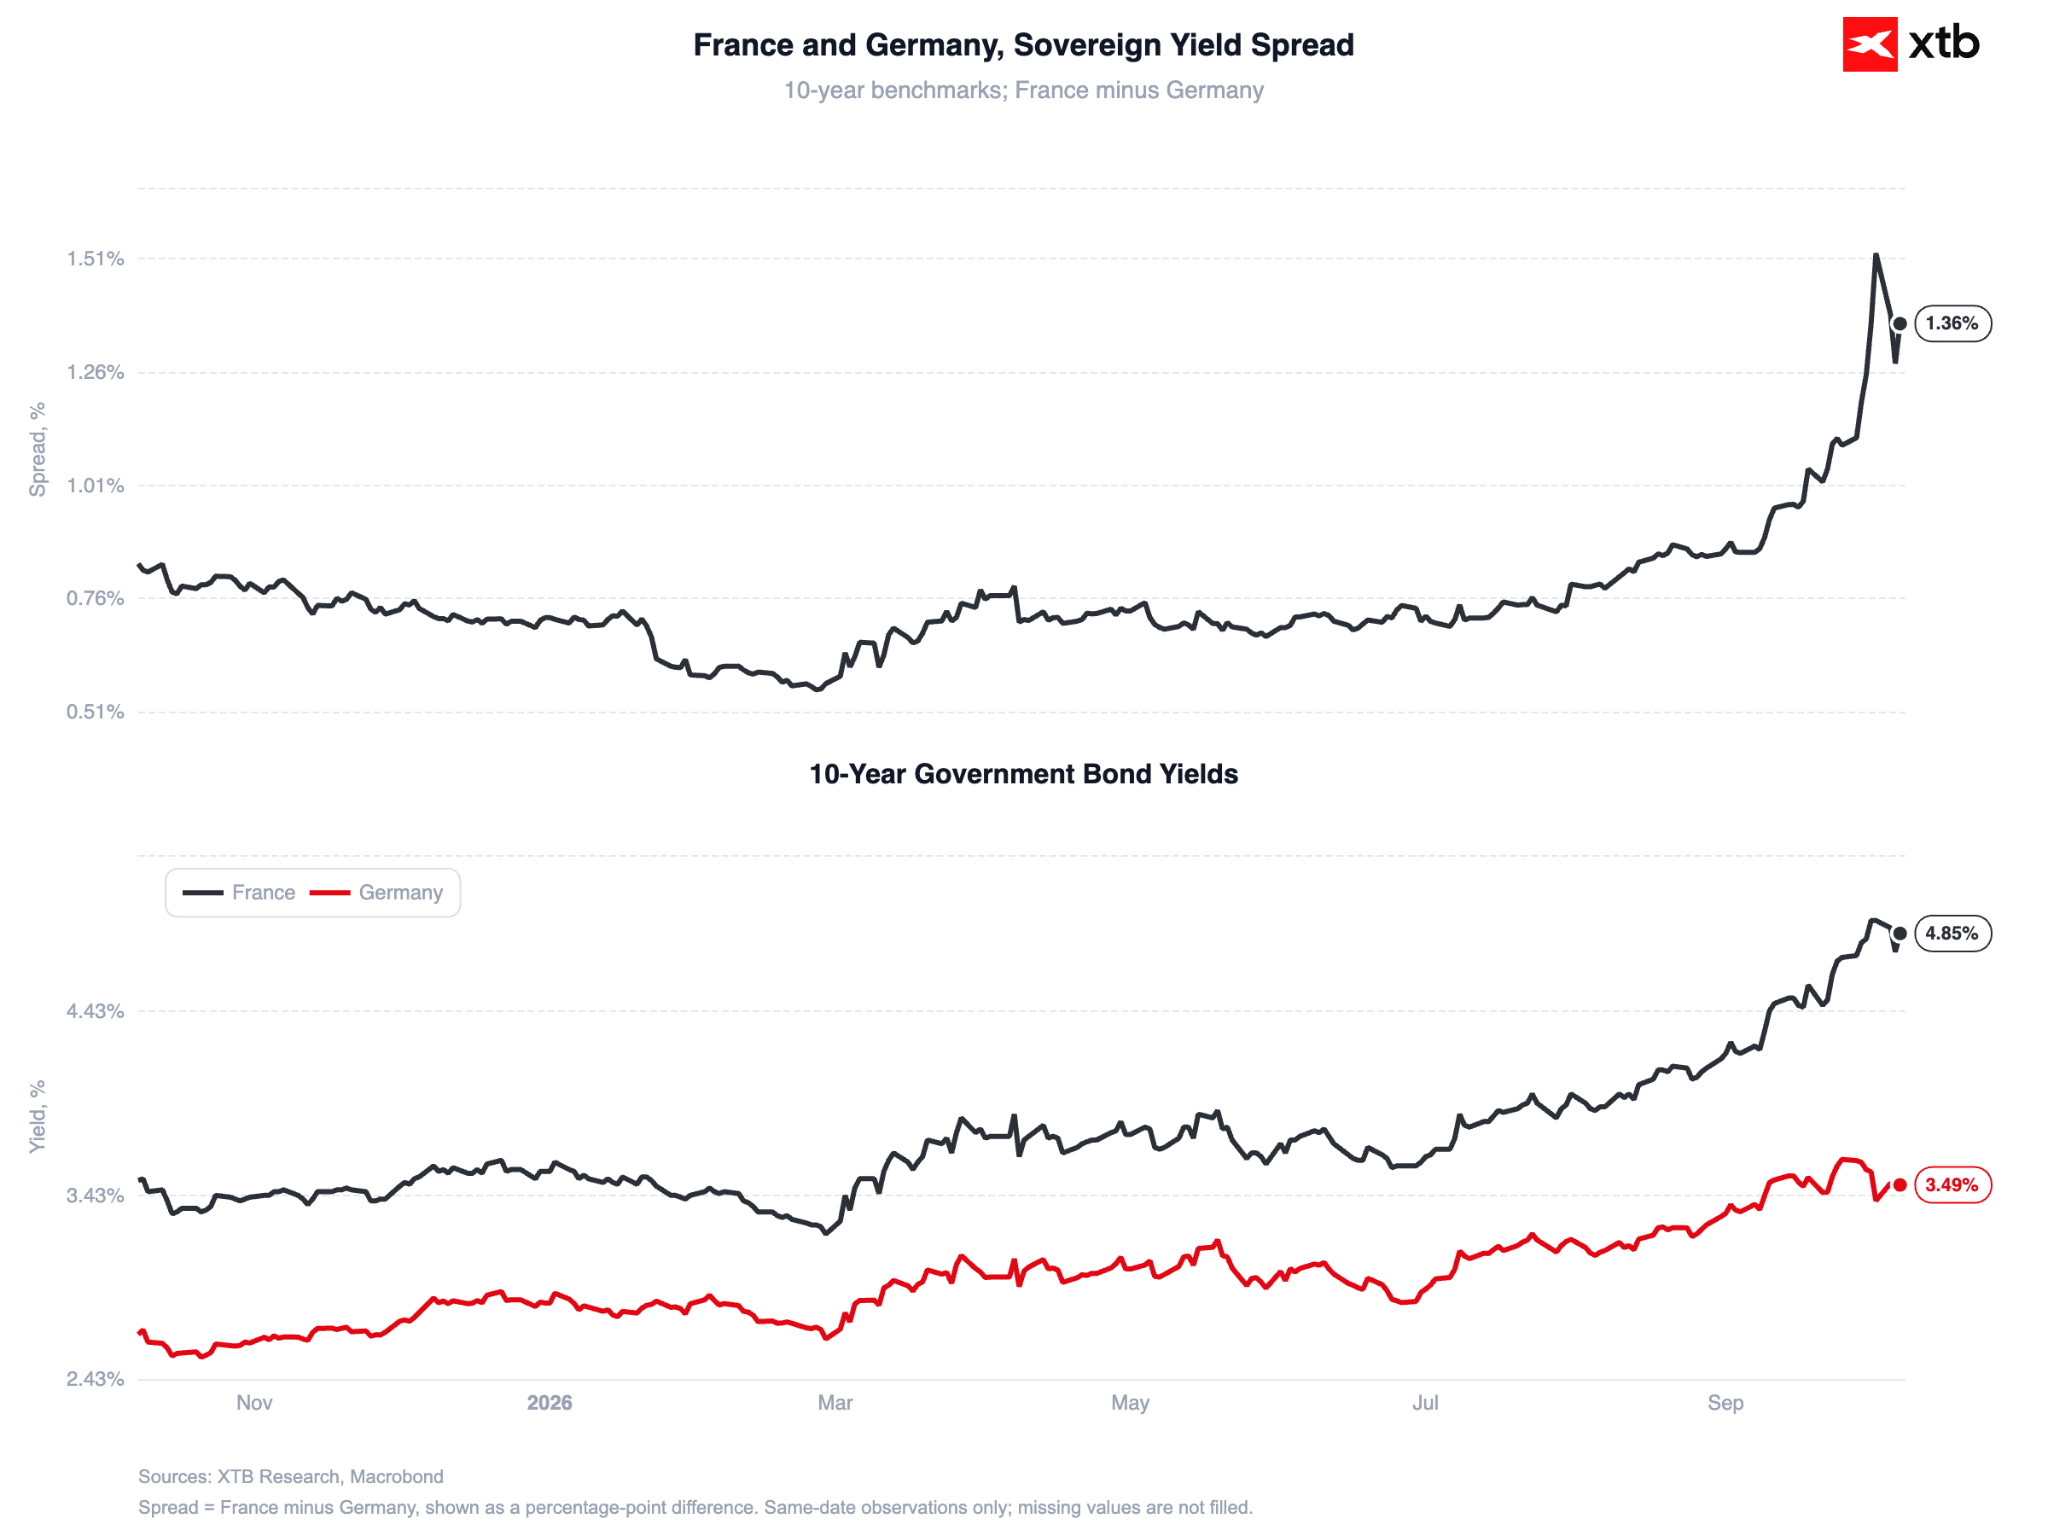 Source: XTB Research, 08.10.2026
Equity Market
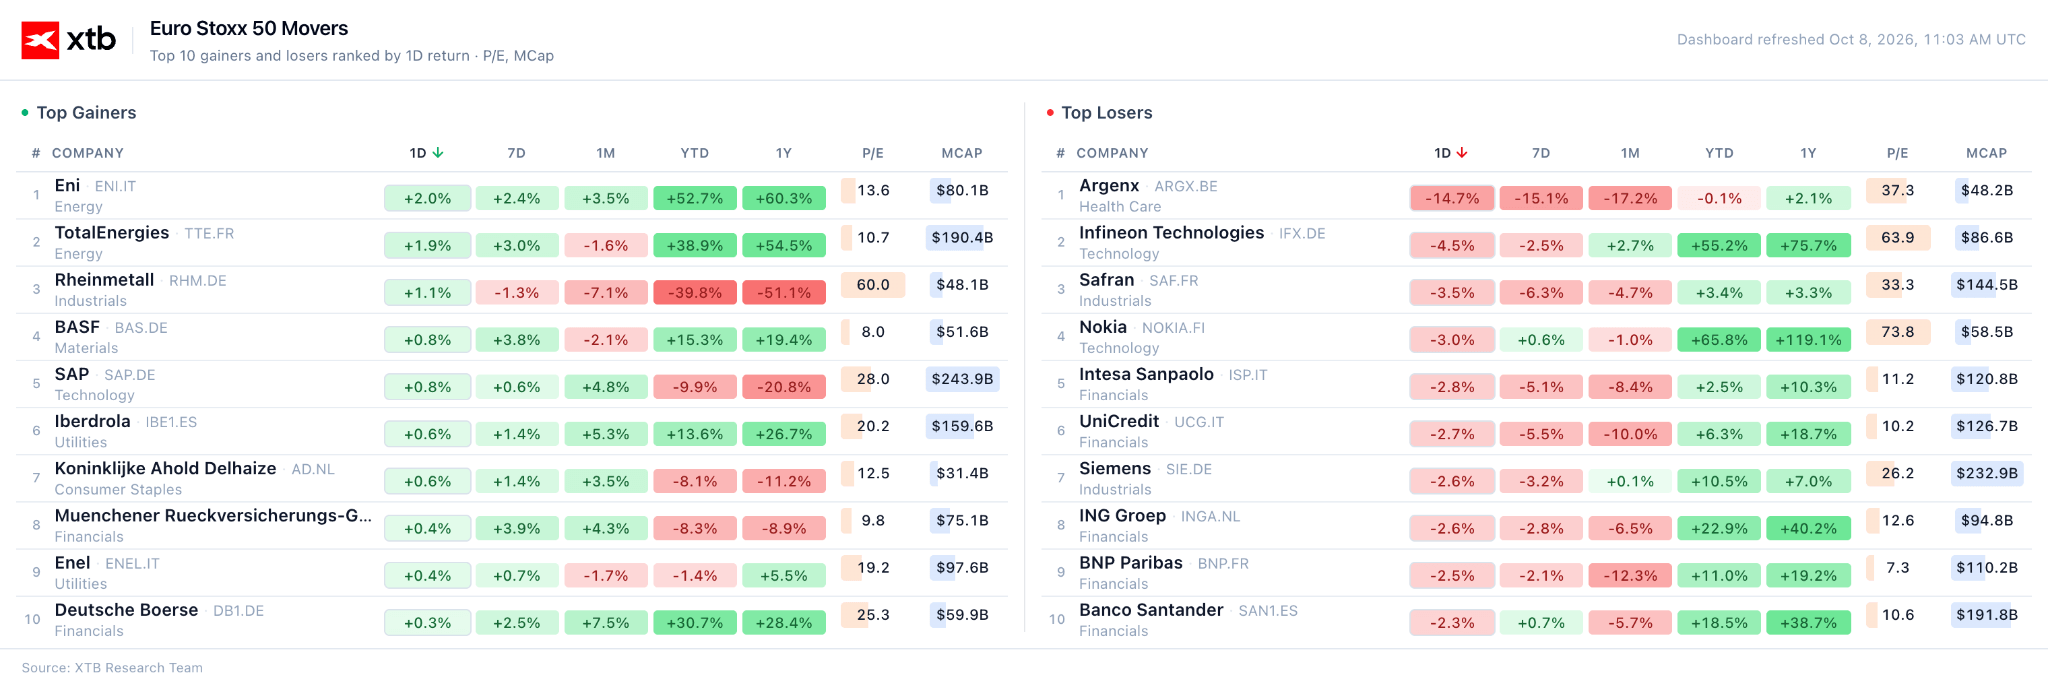
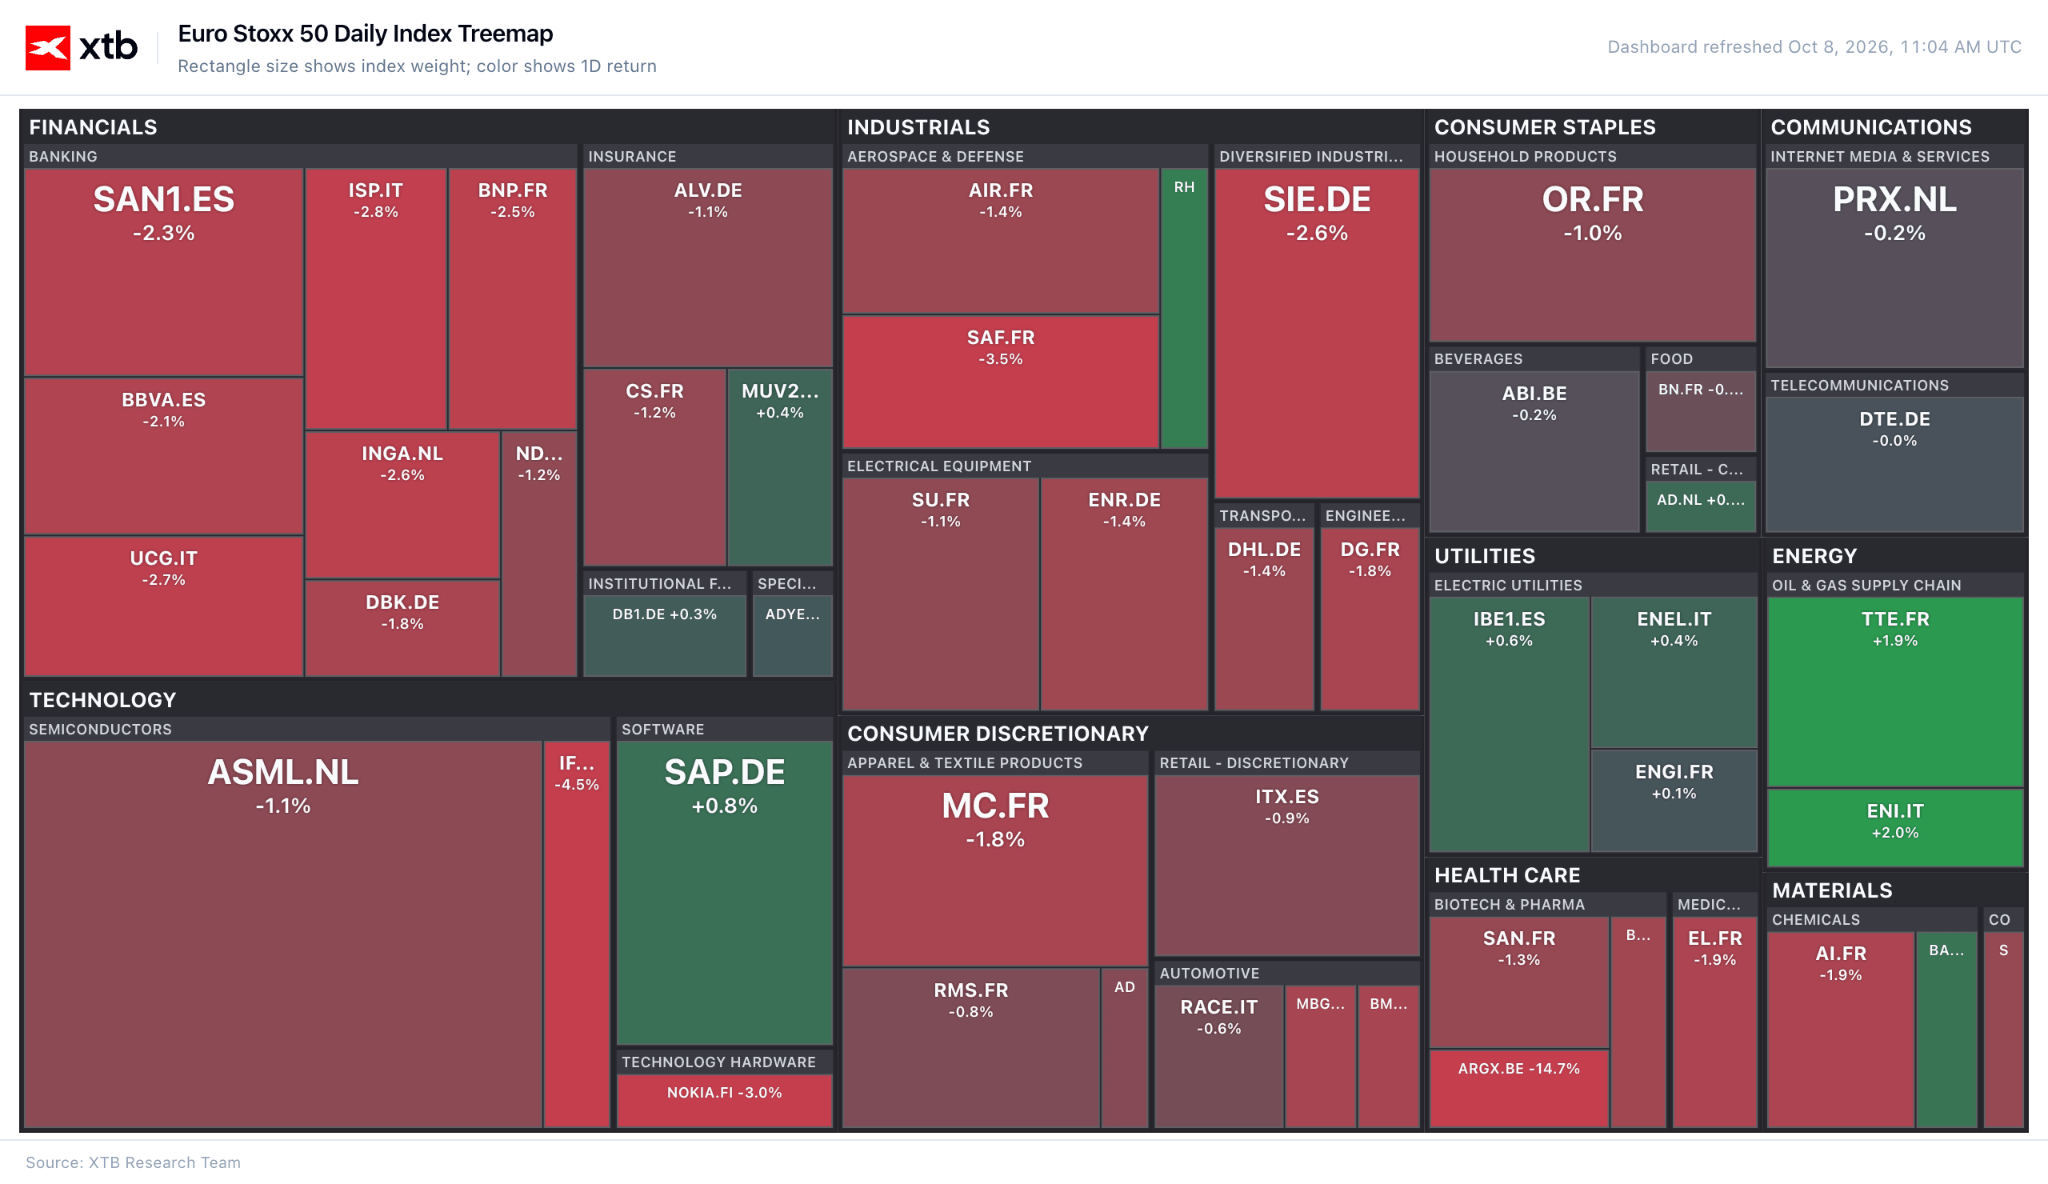
The sell-off across oil and bond markets is spilling over into equities. Futures on the S&P 500 are down 0.4%, signalling a second consecutive day of retreat from record highs. European indices are also trading firmly in the red. The pan-European Euro Stoxx 50 is down 1.1%, the French CAC 40 has lost 0.9%, the Italian FTSE MIB is down 1.3%, whilst Germany's DAX is trading 0.8% lower.
Figure 4: Gainers and Losers in the Euro Stoxx 50 (08.10.2026)
 Source: XTB Research, 08.10.2026
The European banking sector is coming under particularly intense pressure, with the Stoxx 600 Banks Index down by nearly 2%. Concerns surrounding France's fiscal position are weighing on sentiment, potentially dissuading the ECB from embarking on an aggressive interest rate hiking cycle that markets had previously priced in.
Figure 5: Treemap for the Euro Stoxx 50 (08.10.2026)
 Source: XTB Research, 08.10.2026
Semiconductor stocks are also underperforming, with Samsung's quarterly results taking centre stage. Despite reporting a tenfold surge in operating profit, the figures failed to satisfy investor expectations, causing its share price to slide by almost 2.5%. Samsung's preliminary Q3 operating profit surpassed 100 trillion South Korean won for the first time (reaching KRW 107.4 trillion, or approximately USD 80 billion). Revenue rose to KRW 195 trillion, driven primarily by demand for HBM and DRAM memory chips.
Monetary Policy
One of the FOMC's most vocal policymakers recently, Christopher Waller, remarked today that further interest rate increases will likely be necessary to bring inflation back down to target. However, he noted that the central bank retains flexibility regarding the timing and does not need to tighten policy at an aggressive pace with rate hikes at every consecutive meeting. Markets are fully pricing in a rate increase in December, whilst attributing a probability of under 20% to a move at the upcoming meeting in late October.
Precious Metals and Cryptocurrencies
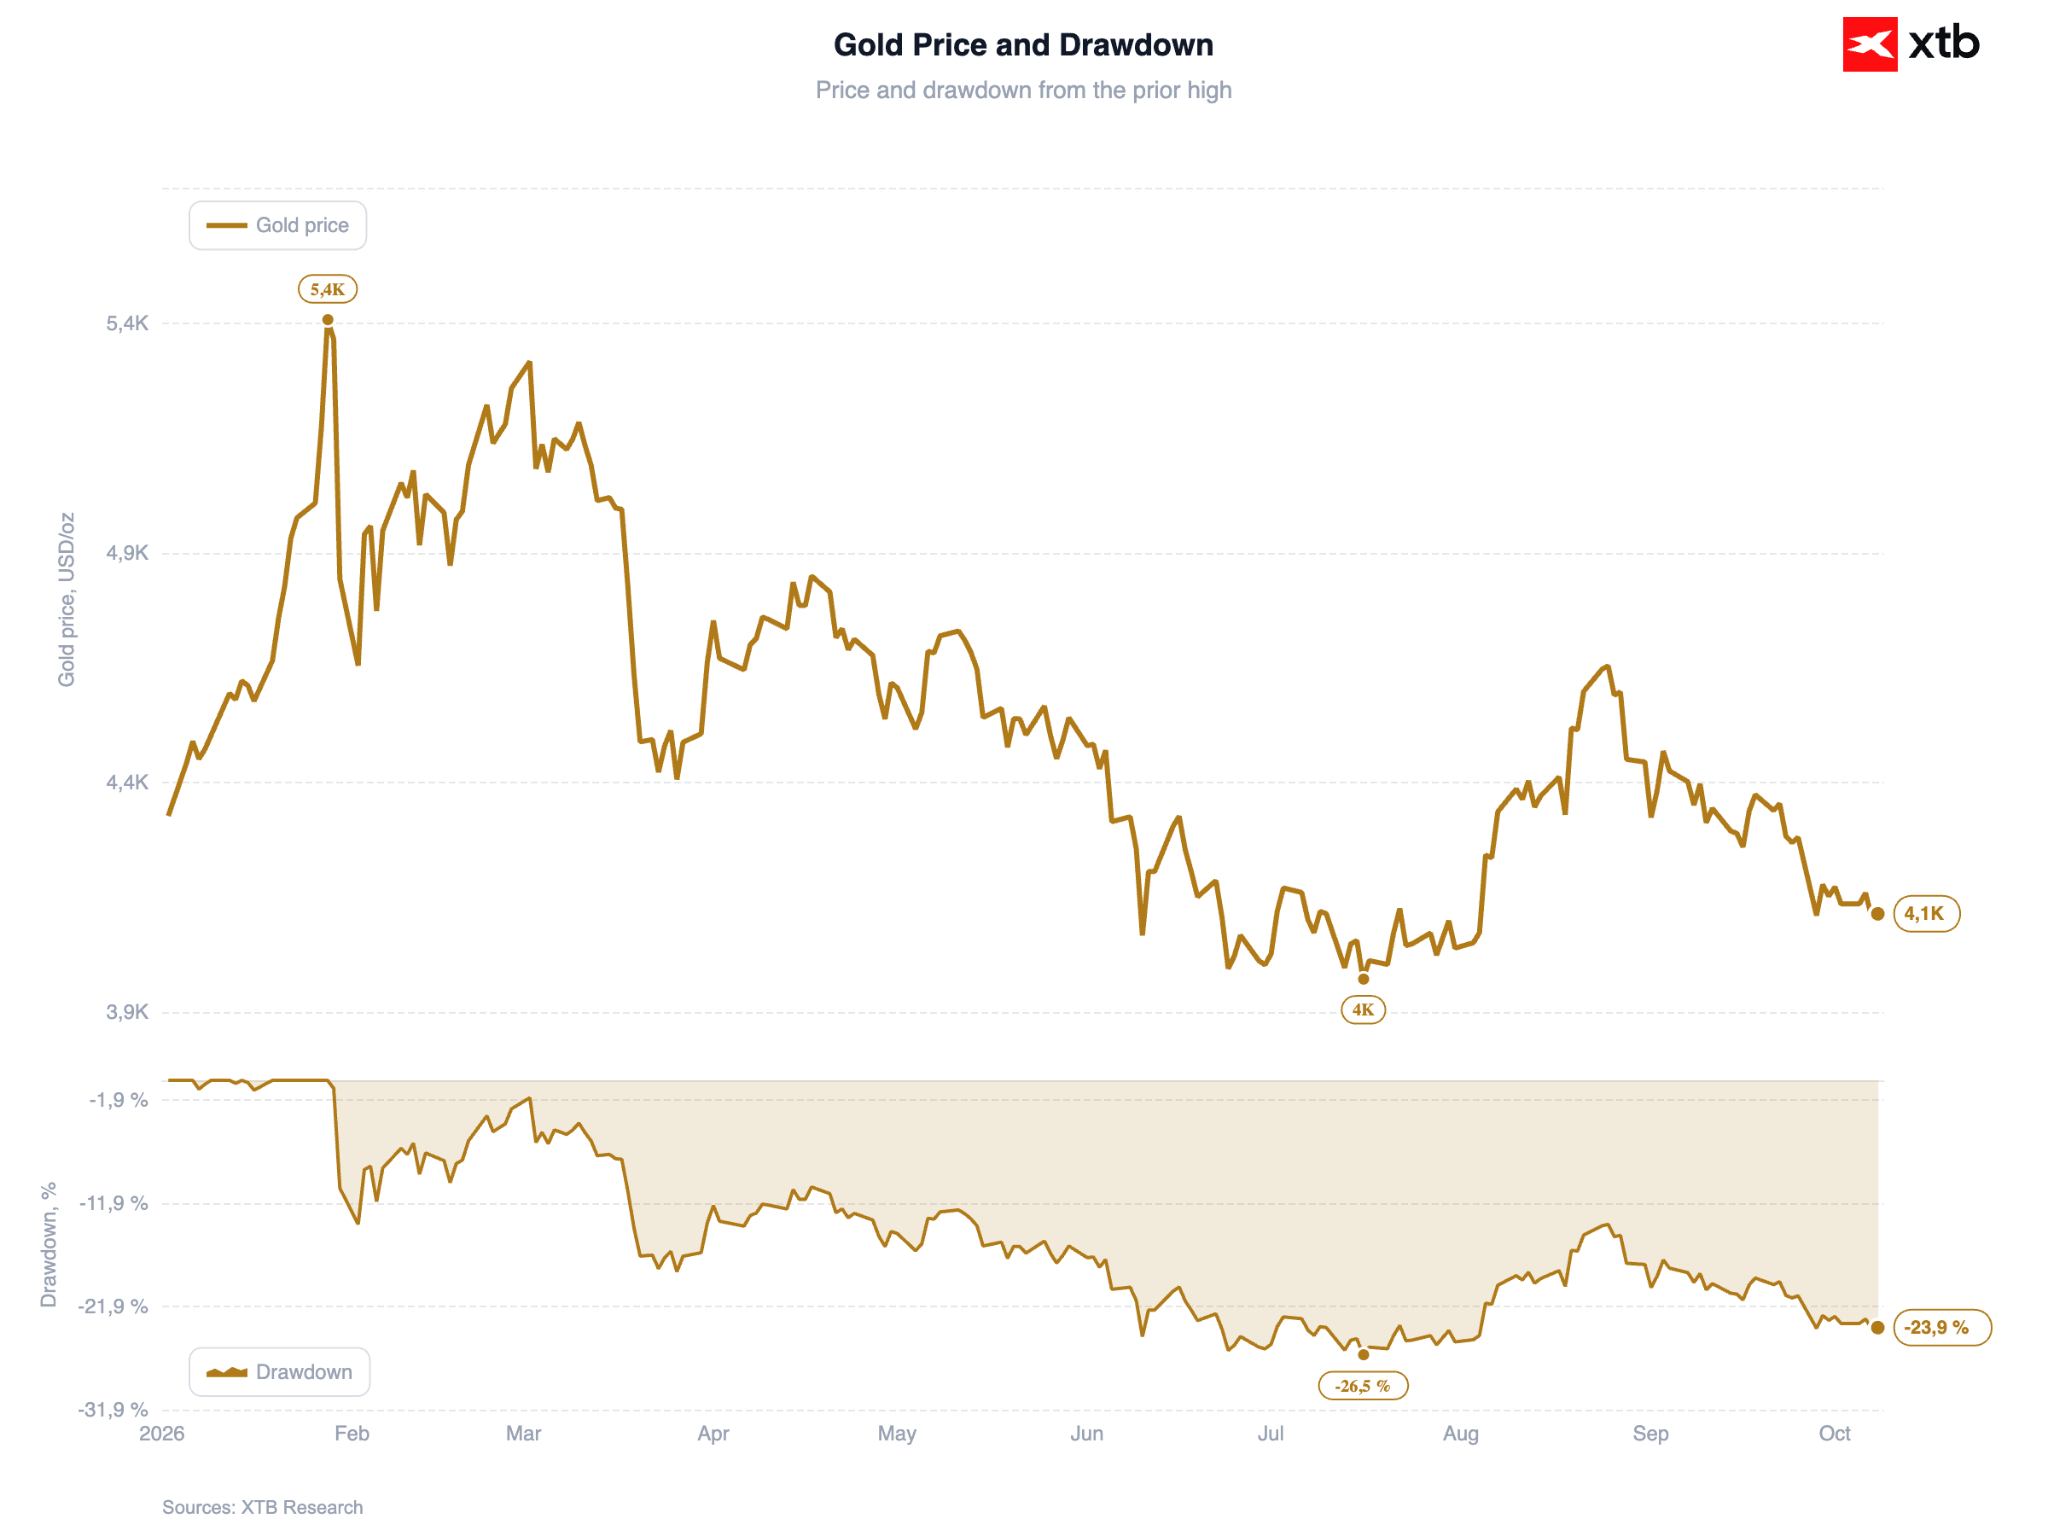
Gold is gaining around 0.3% today, climbing to approximately $4,120 per ounce, slightly above yesterday's 9-week low. Prices are supported by inflation concerns linked to surging oil prices, as well as the return of Chinese buyers following the Golden Week holiday. However, the recovery faces headwinds from a firmer US dollar, with the dollar index hovering near its year-to-date highs. Gold remains roughly one-fifth cheaper than prior to the outbreak of the US-Iran conflict. Silver is shedding about 1.4% today, whilst Bitcoin edges down by around 0.4%.
Figure 6: Gold (2026)
 Source: XTB Research, 08.10.2026
—
Michał Jóźwiak, Financial Markets Analyst at XTB



Market Wrap: Oil rises again, French fiscal concerns weigh on euro (07.10.2026)



Oil falls below $100🚨
💶Chart of the Day: EURUSD at Lowest Since May 2025 Amid French Fiscal Crisis
Morning Briefing: Dollar gains, oil falls. EURUSD at multi-month lows
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.