


📉 Equity Markets
- Friday’s session on European equity markets is marked by mixed sentiment. The UK’s FTSE 100 and France’s CAC 40 are leading modest gains, although their upside remains limited.
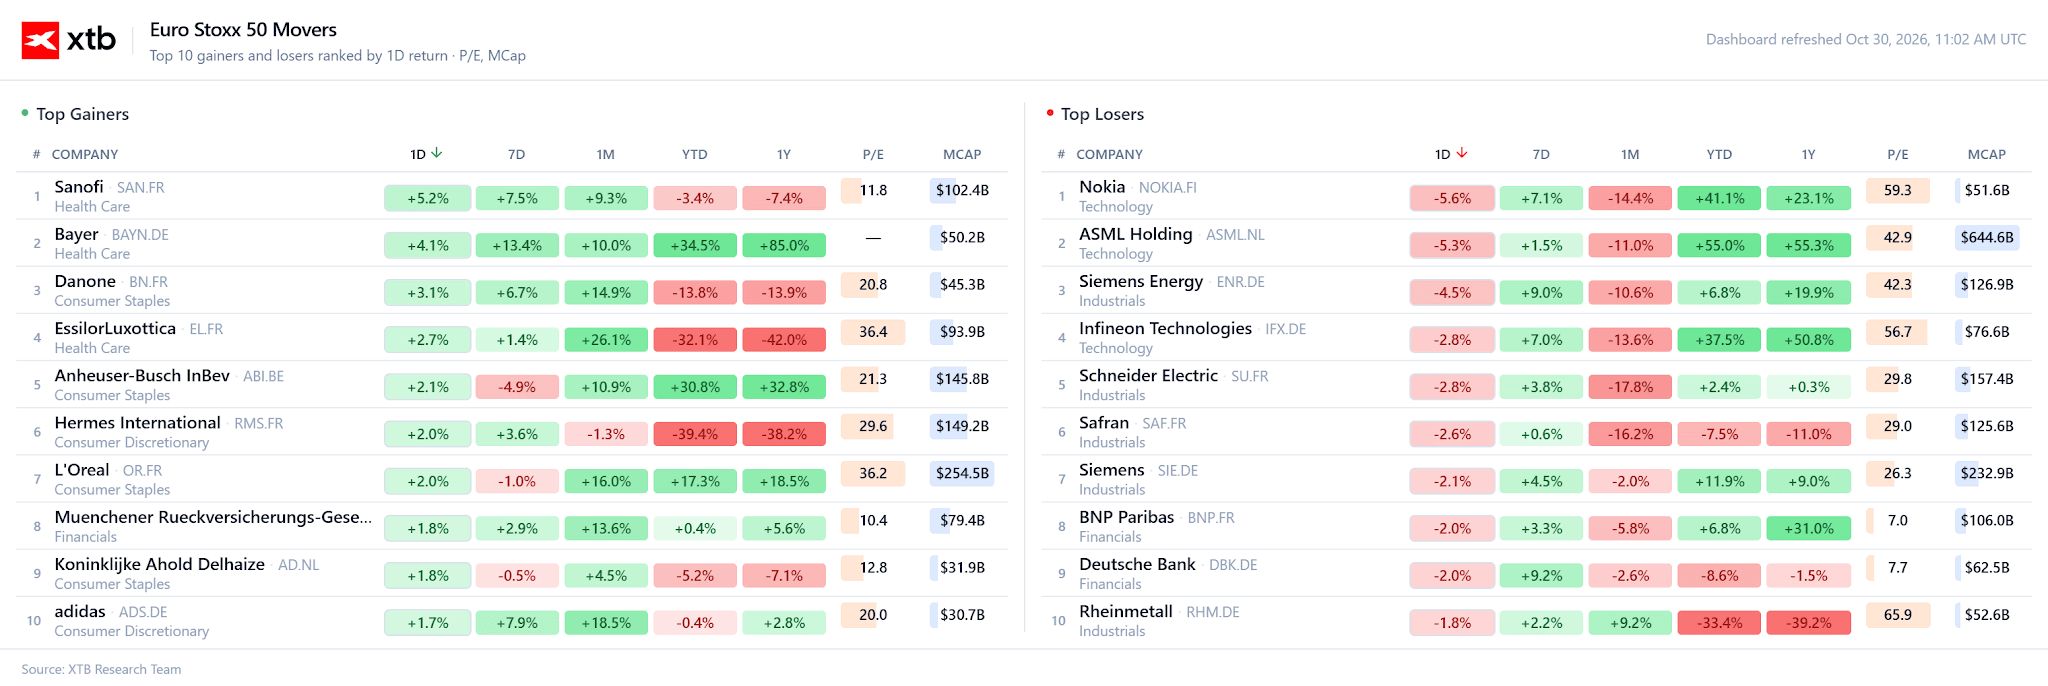
- At the other end of the performance table, Germany’s DAX and Spain’s IBEX 35 are both down around 0.5%, while the pan-European Euro Stoxx 50 is also facing notable selling pressure.
- Sentiment across European markets is being shaped by a global sell-off in technology stocks, initially triggered by Alphabet’s quarterly results and subsequently deepened by earnings reports from Amazon and Intel.
- Investor sentiment is deteriorating primarily amid growing concerns over the enormous capital expenditure required to develop AI infrastructure.
- Amazon is reporting negative free cash flow of $42.4 billion, while capital expenditure alone reached $77.3 billion in the third quarter.
- Intel’s results are also disappointing. The company has issued fourth-quarter revenue guidance below market expectations, pointing to a clear slowdown in demand across the personal computer segment.
- The sell-off is spilling over into Europe’s semiconductor and technology sectors, putting shares of ASML, ASM International and Infineon under significant pressure, particularly companies supplying infrastructure for data centres.
🏛️ Macroeconomics and Central Banks
- Macroeconomic data released during the session point to greater-than-expected resilience in the European economy. Eurozone GDP grew by 0.4% quarter on quarter and 1.3% year on year in the third quarter, exceeding market forecasts of 1.1% annual growth.
- Germany and Spain remain the main pillars of economic activity across the euro area, while Italy continues to stagnate and France is showing a marked slowdown in growth.
- In Germany, GDP expanded by 0.2% quarter on quarter, beating market expectations of 0.1%, bringing annual growth to 1.3%.
- Despite the positive headline figure, the German economy continues to face structural challenges. The third quarter saw a slowdown in export growth, which has traditionally been the main engine of the economy, alongside declining capital investment and only marginal increases in household consumption and public spending.
- Italy’s figures were considerably weaker. GDP was unchanged quarter on quarter, with annual growth standing at 0.8%. Positive contributions from the services and agricultural sectors were entirely offset by a sharp downturn in industrial activity and a negative contribution from net exports.
- Inflation remains a major concern across Europe, with price growth accelerating again in the eurozone’s largest economies and significantly complicating the European Central Bank’s policy outlook.
- The biggest negative surprise came from Italy, where CPI inflation rose to 5.4% year on year in October, up from 4.2% in September, while prices increased by 0.9% month on month. The acceleration was driven primarily by rising energy costs, with core inflation also climbing from 1.6% to 2.0% year on year.
- Inflationary pressures are also intensifying in France, where CPI accelerated to 3.4% year on year from 3.1% in September, driven by higher energy, gas and fuel prices, as well as rising costs across transport and hospitality services.
- Spain presents a more stable picture, with CPI inflation holding at 4.9% year on year and core inflation unchanged at 3.1%. Higher energy and gas prices are being partly offset by lower fuel prices and a slower pace of food price increases.
- The combination of relatively resilient economic activity and a renewed inflationary rebound leaves the European Central Bank in an especially difficult position.
- Stronger-than-expected GDP growth weakens the case for further aggressive monetary easing, while the return of price pressures raises the risk that inflation will remain elevated over the coming quarters.
- As a result, the ECB’s December meeting is emerging as a key source of market risk. Investors will be closely watching upcoming inflation data and developments in energy prices.
🛢️ Commodities
- Precious metals are firmly in negative territory during Friday’s session, with sellers clearly dominating trading.
- Gold is down by more than 1%, breaking below the psychologically important $4,000-per-ounce level.
- Silver is facing an even sharper sell-off, falling nearly 3% and testing a key support level around $50 per ounce.
- Sentiment is markedly different in energy markets, where crude oil prices are moving higher.
- Brent crude futures are up nearly 2%, testing the $114-per-barrel level, while WTI is gaining almost 1.5%, approaching $105 per barrel.
🪙 Cryptocurrency Market
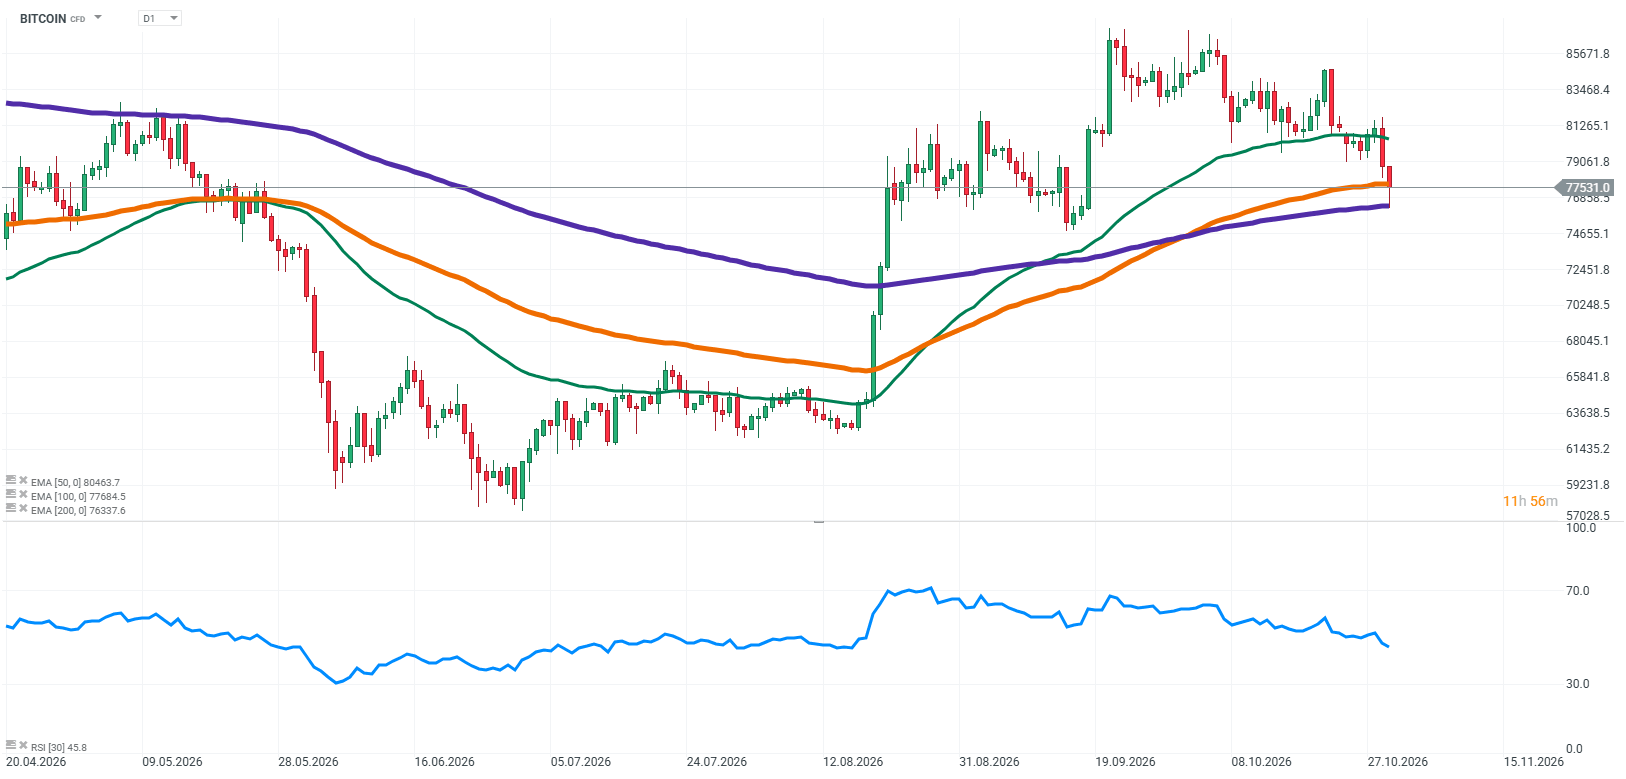
- Digital assets are under significant pressure following what is being described as the largest cyberattack in Binance’s history, with estimated losses of $6.3 billion.
- According to preliminary reports, the breach was made possible by the successful compromise of a work laptop belonging to one of the platform’s key engineers.
- In response to the incident, Binance has temporarily suspended deposits and withdrawals while implementing emergency procedures in cooperation with specialist blockchain security firms.
- Operational measures taken so far have resulted in approximately $3 billion worth of stolen assets being frozen. However, the recovery of the remaining funds remains uncertain.
- Concerns are mounting over whether customer claims can be fully covered. Binance’s Secure Asset Fund for Users (SAFU) holds reserves of approximately $1 billion, meaning the exchange may need to commit a substantial amount of its own capital to cover the shortfall.
Source: XTB Reseach

Chart of the Day: USDJPY After Fed and BoJ decisions. Is Japan getting closer to another rate Hhike?

Intel has come face to face with reality. A Turnaround is still a long way off.


Binance Hit by the Largest Hack in Cryptocurrency Market History. Losses Could Reach USD 6.3 Billion


Economic Calendar: Preliminary European GDP and German Inflation in Market Focus
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.