


The MSCI All Country World Index, which tracks large and mid-cap companies across more than 40 countries, is down for a seventh straight session, its longest losing streak since September 2023. The sell-off initially began in AI-related stocks, but today it is spreading across the entire market.
The stock market debut of Anthropic, whose shares surged 17% on Thursday, failed to halt the declines. Today, the company's shares are losing around 10% in pre-market trading.
Stock Market
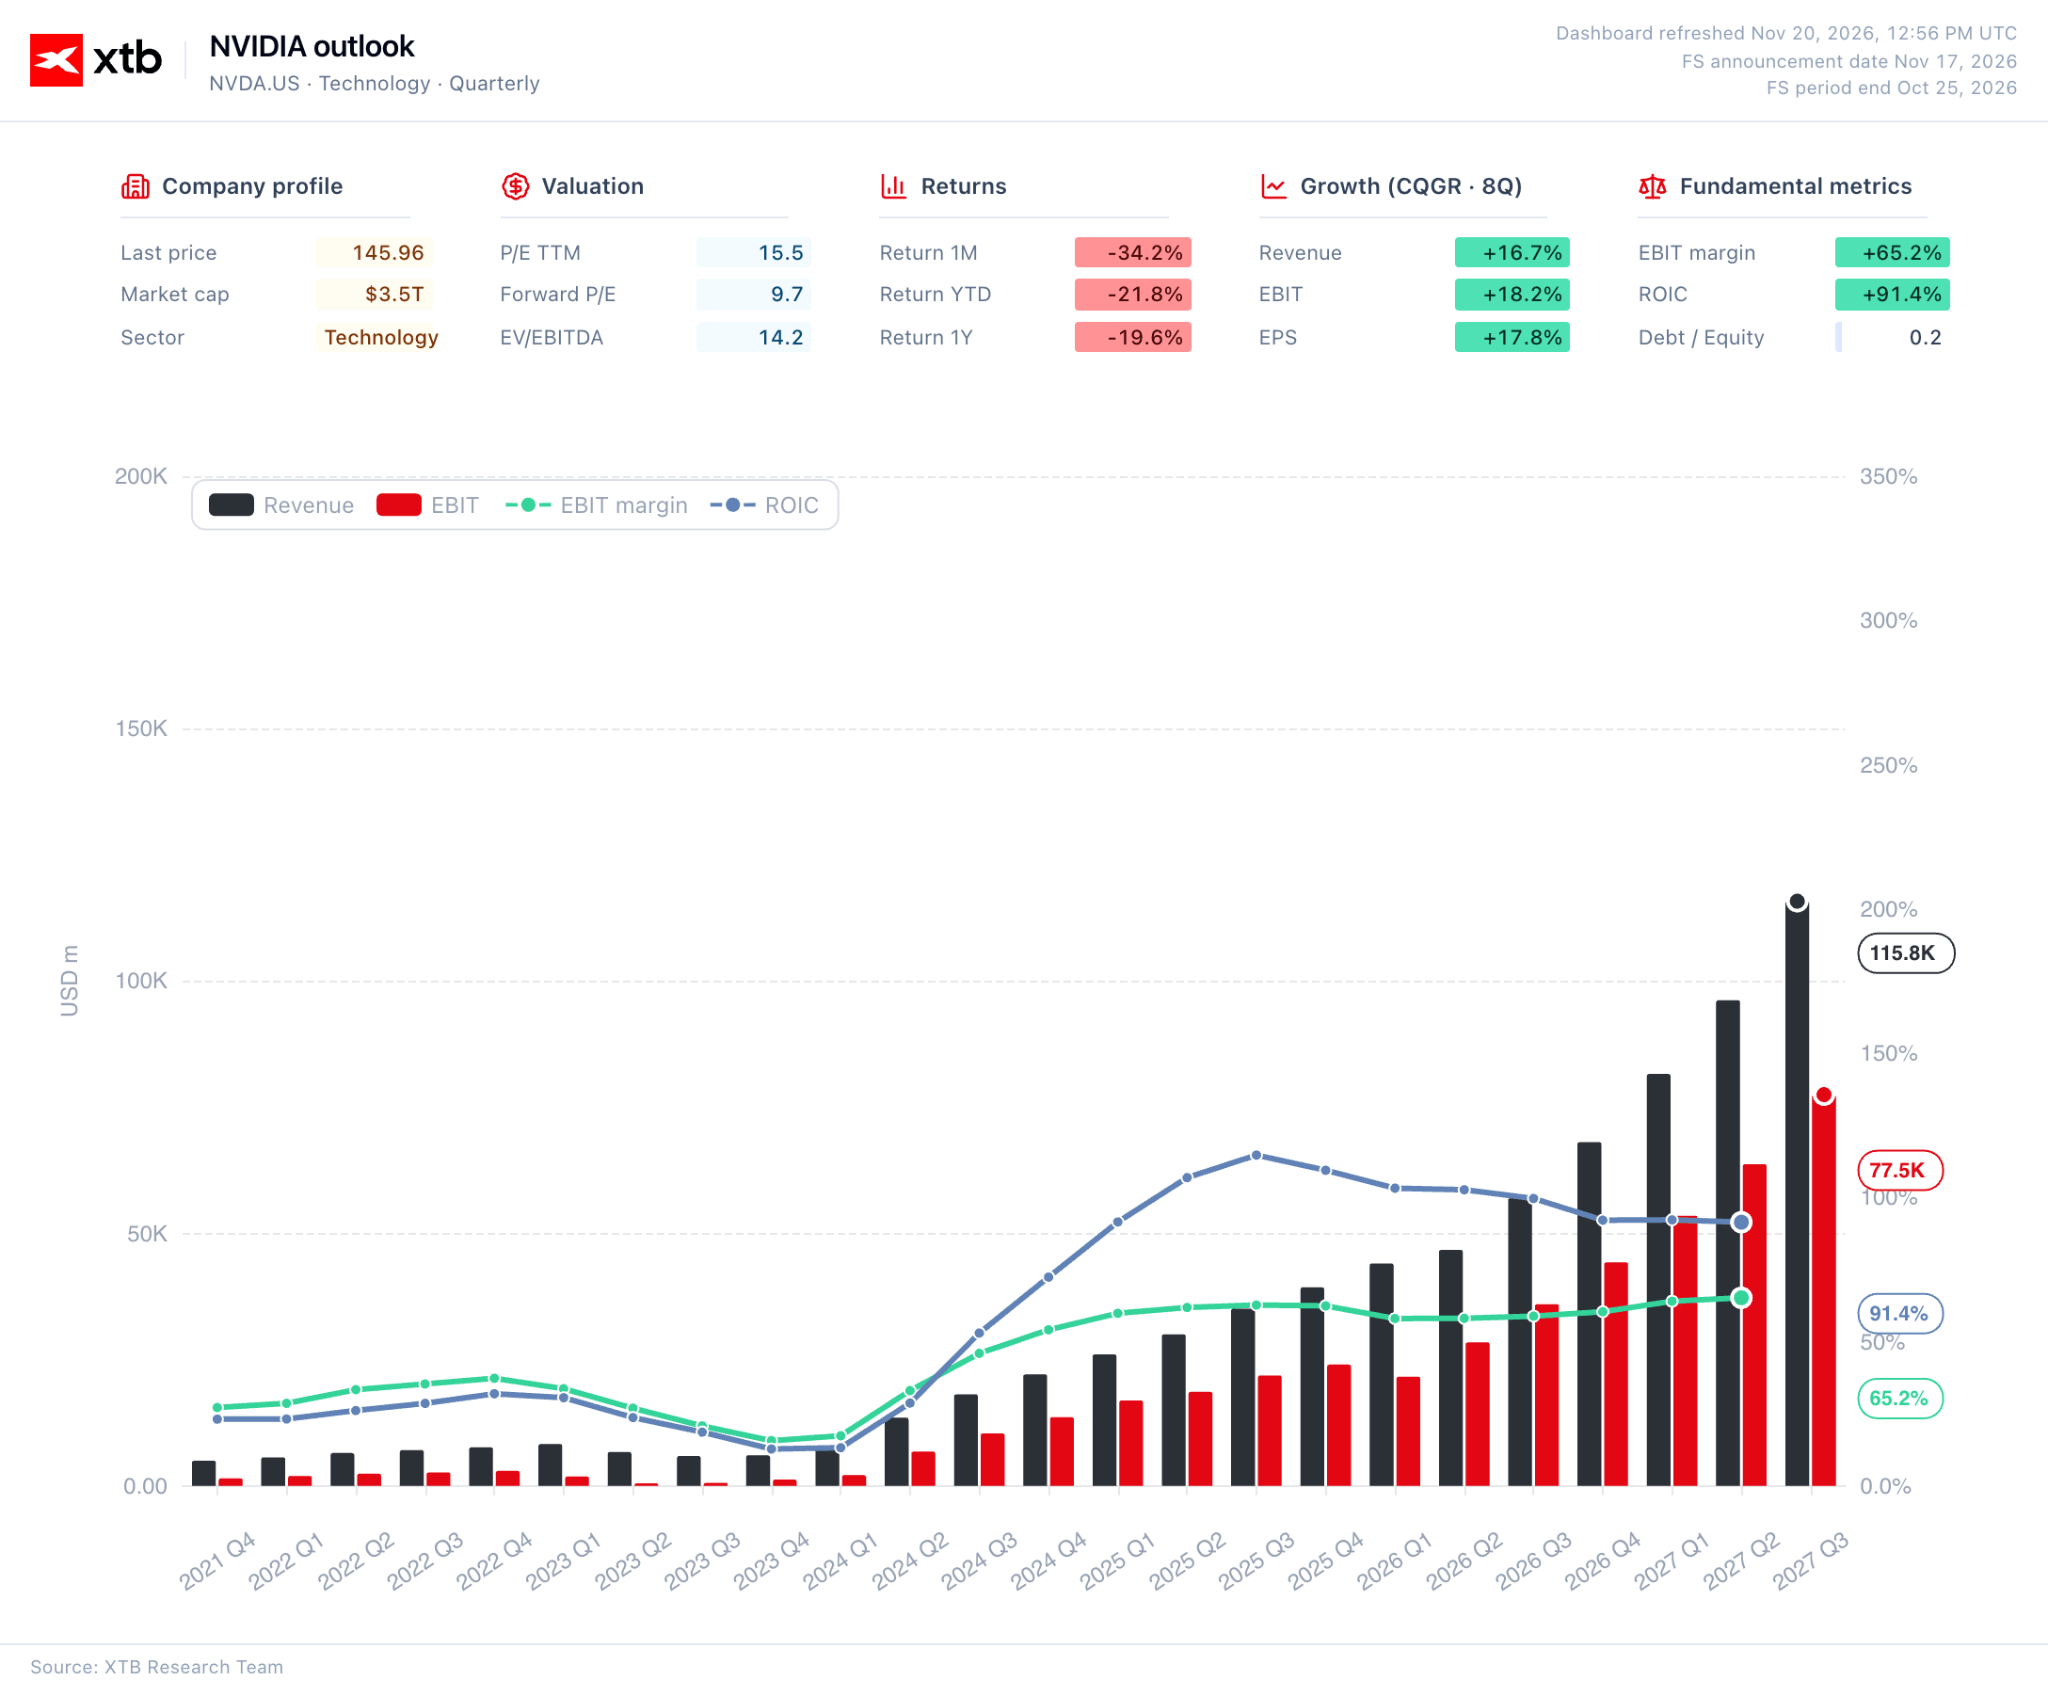
The main driver behind the deteriorating sentiment remains a growing scepticism regarding the vast sums being poured into artificial intelligence and when these investments will begin to yield returns. Added to this is the concern that the entire AI ecosystem is overly reliant on circular financing. Nvidia, which has hitherto driven the growth of many early-stage AI firms, may pull back from this role following the departure of Jensen Huang, potentially dampening demand for computing power. Borrowing costs are also rising: SpaceX issued $32 billion in bonds this week, with a portion yielding over 8%.
Figure 1: Nvidia Dashboard (2021–2026)
 Source: XTB Research, 20.11.2026
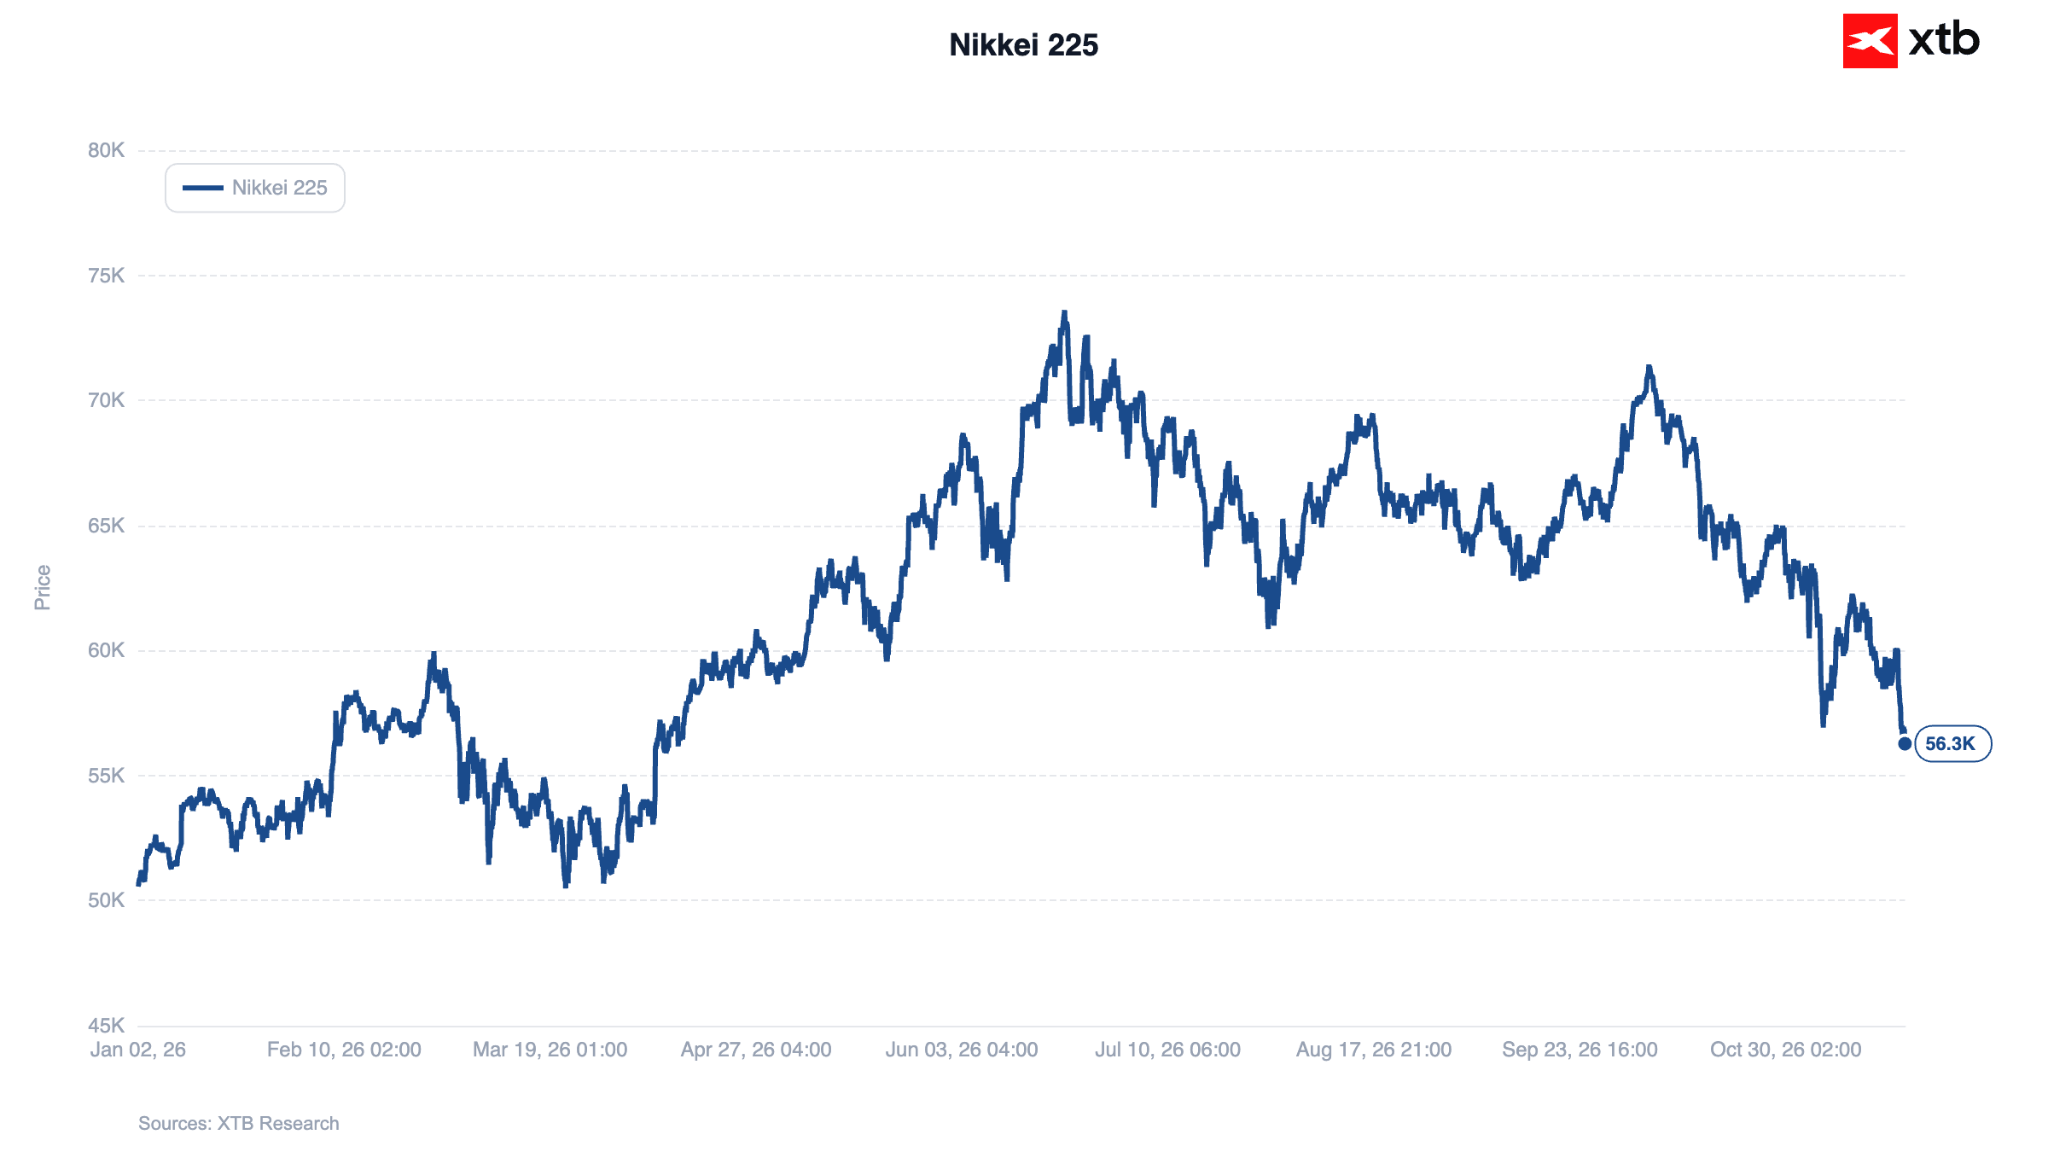
Yesterday's losses spilled over into Asian markets, particularly hitting economies heavily reliant on semiconductor manufacturers. Both the Korean KOSPI and Japan's Nikkei 225 fell by over 5% today. SoftBank, a major shareholder in OpenAI, dropped nearly 15%.
Figure 2: Nikkei 225 (2026)
 Source: XTB Research, 20.11.2026
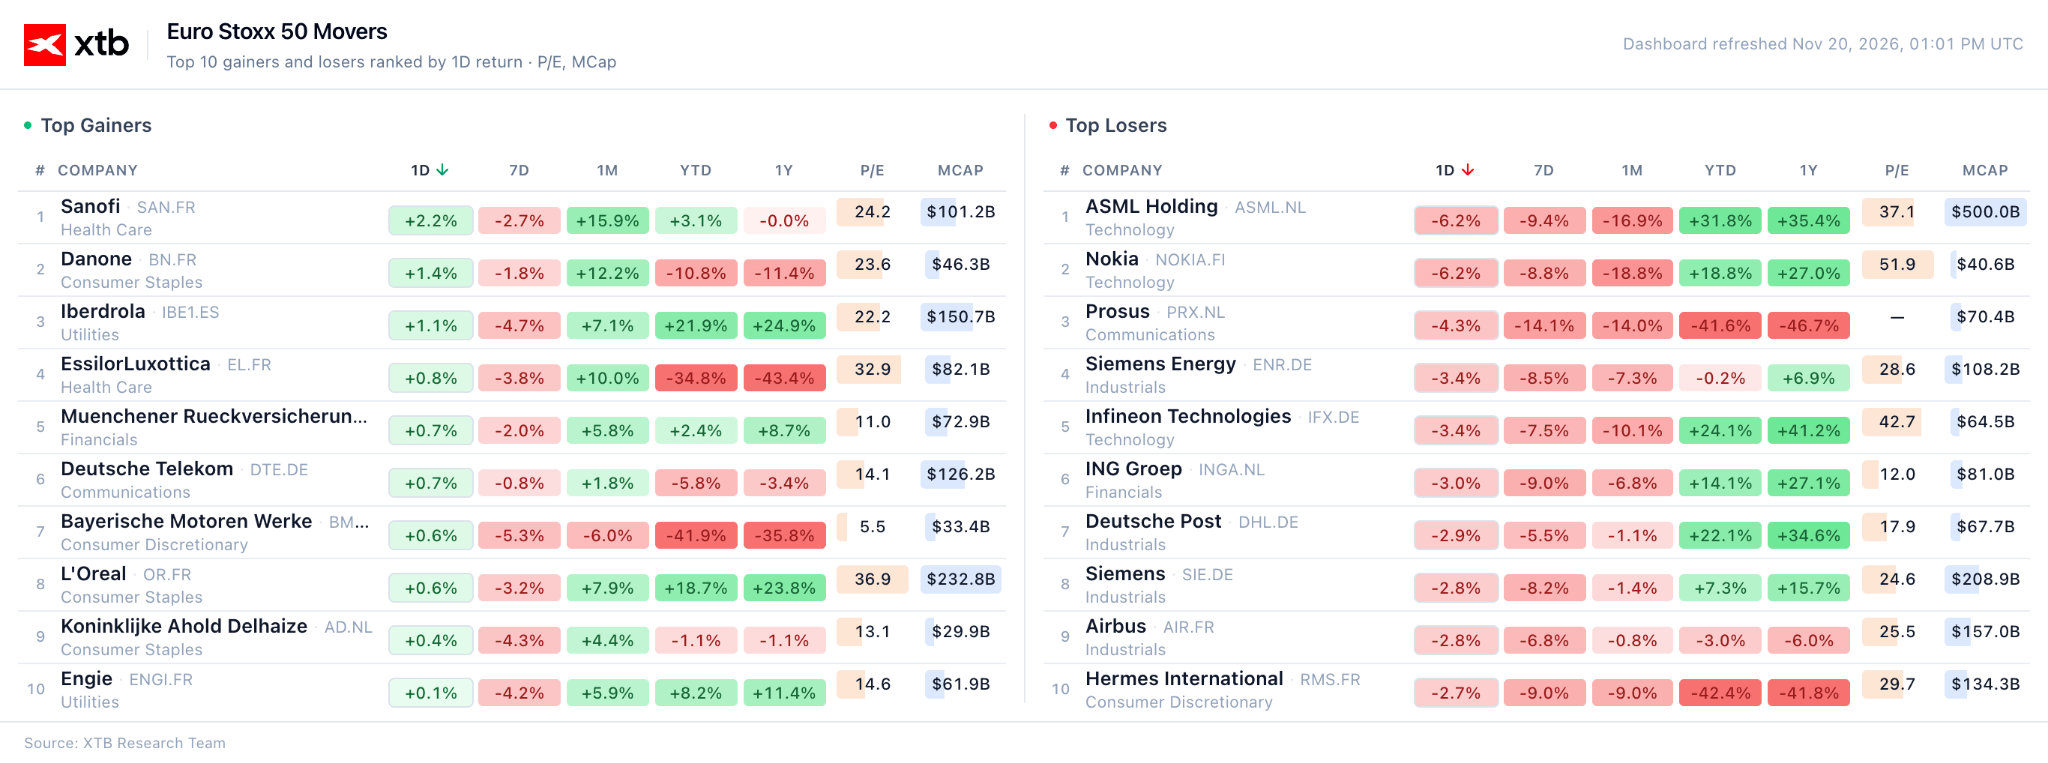
Losses across Europe are likewise substantial. Poland's WIG20 dropped 3.3%. Germany's DAX fell 2%, matching the decline seen in Italy's FTSE MIB. The pan-European Euro Stoxx 600 is down 1.5%.
Figure 3: Gainers and Losers in Euro Stoxx 50 (20.11.2026)
 Source: XTB Research, 20.11.2026
US indices are also trading in the red in pre-market transactions. The Nasdaq 100 experienced the sharpest fall, dropping over 1.5%. Chiptuning and AI sector stocks such as AMD, Micron, Intel, and Intuit remain the biggest losers. Apple posted modest gains following reports that the company may be working on its own proprietary AI agent.
Debt Market
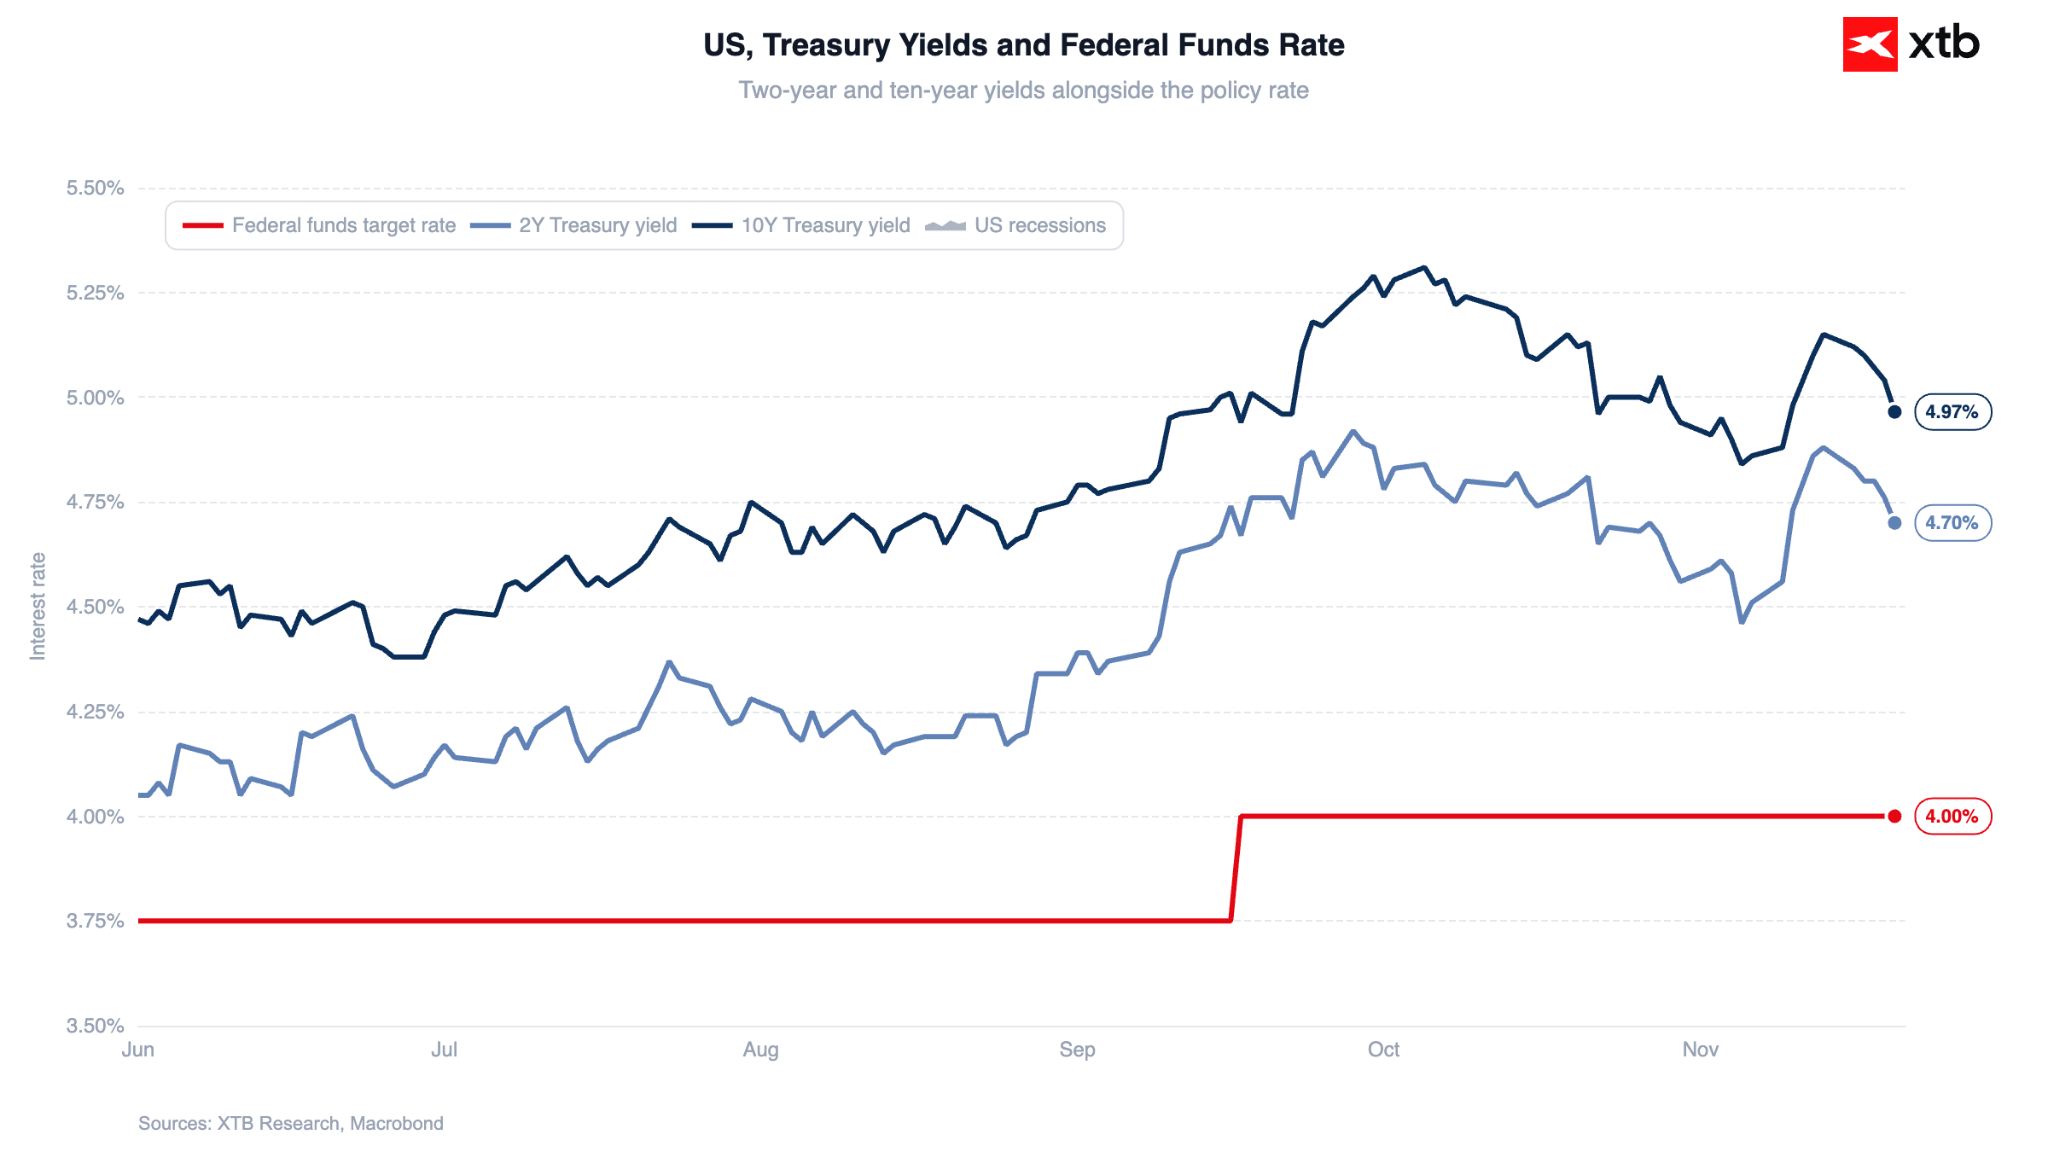
The yield on 10-year US Treasuries fell below 5%, ending a 27-day streak above that threshold. Two-year yields dropped 12 bps this week, marking their steepest weekly fall since August 2025 (currently standing at around 4.71%). Capital appears to be shifting out of equities into safe-haven government bonds.
Figure 4: US Treasury Yields (06.2026–11.2026)
 Source: XTB Research, 20.11.2026
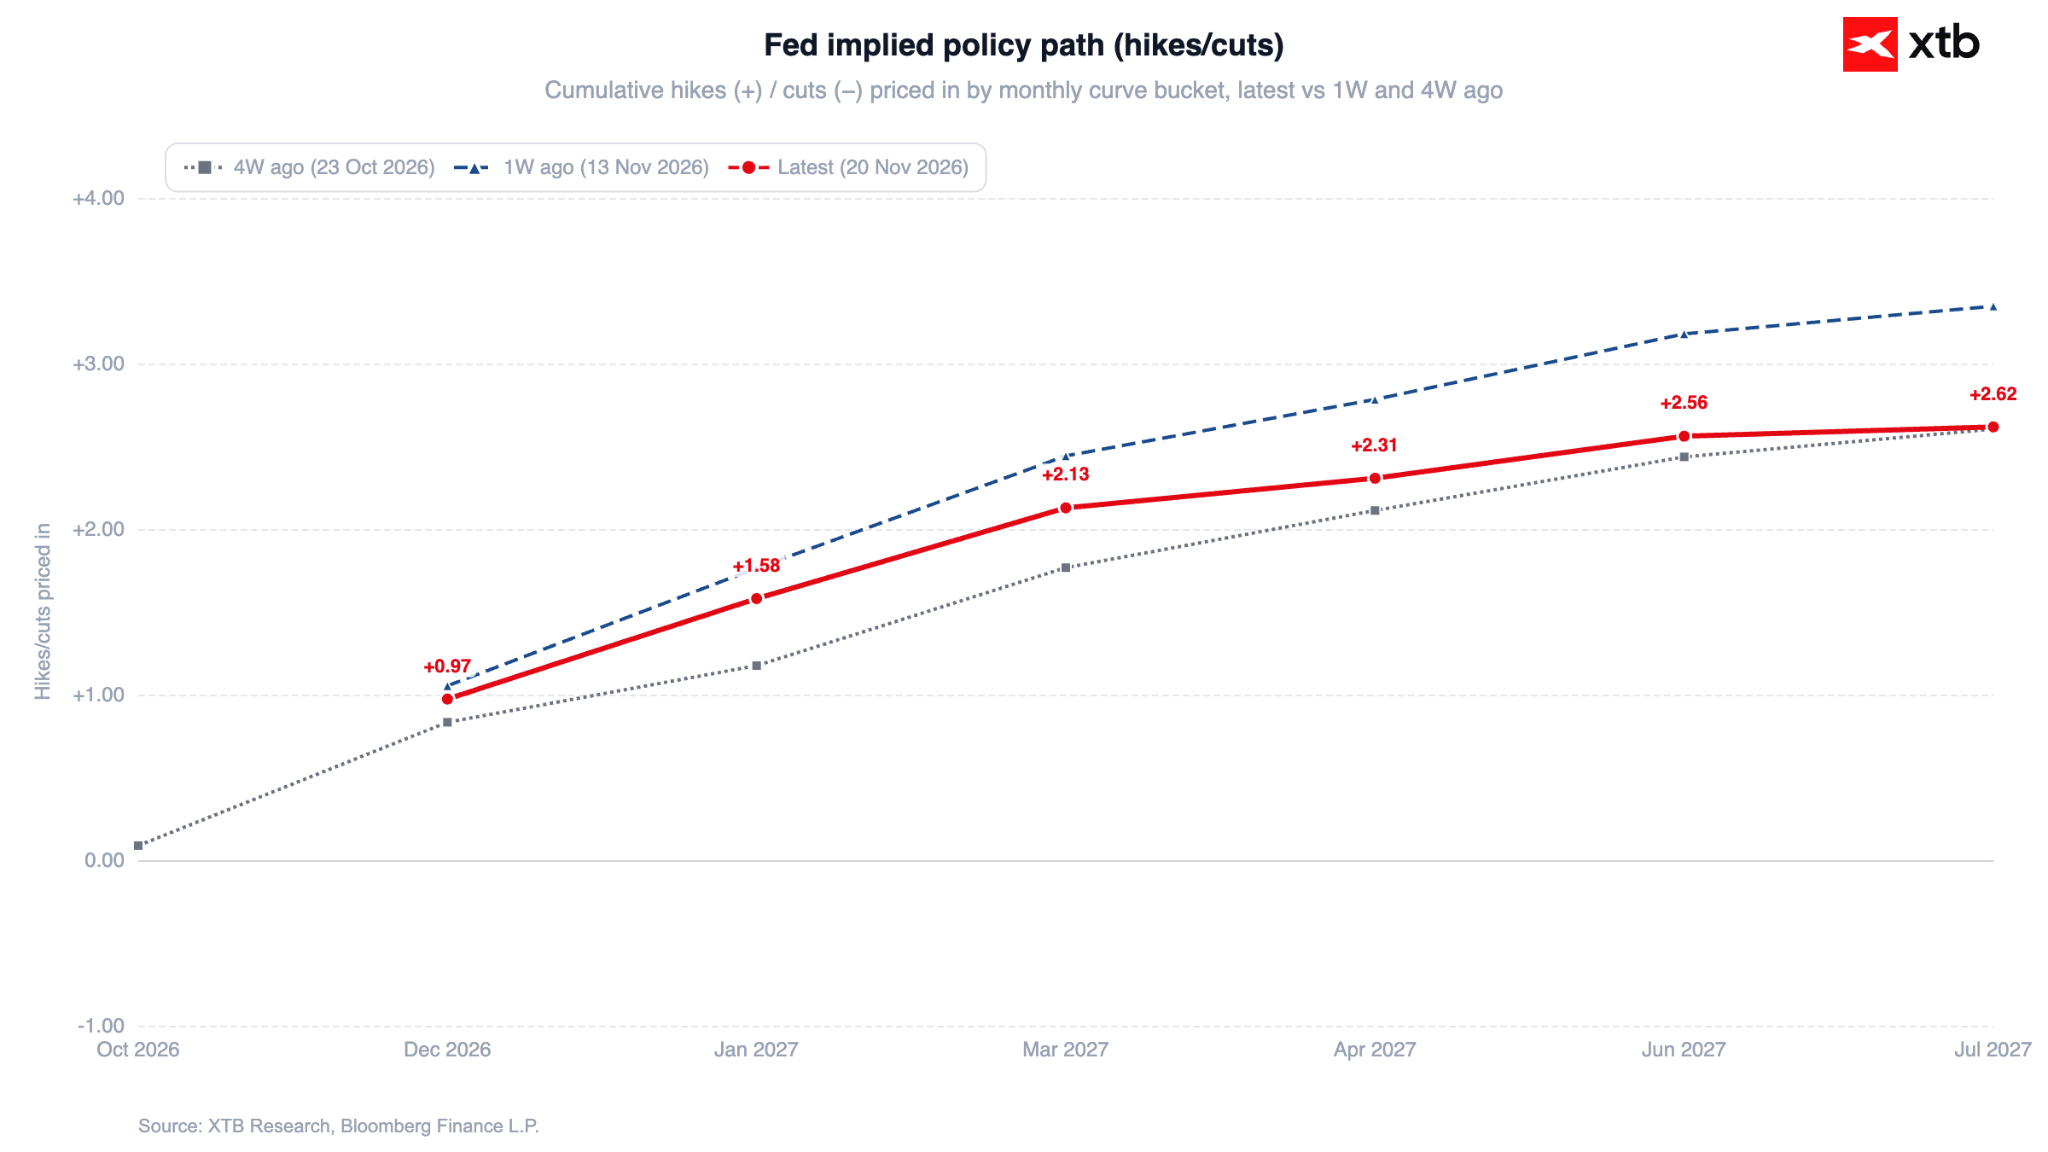
A December interest rate hike by the Fed remains fully priced in by markets. However, investors have pulled back from bets on continued aggressive tightening in the coming months.
Figure 5: Market-Implied Fed Policy Path (2026–2027)
 Source: XTB Research, 20.11.2026
Energy Commodities
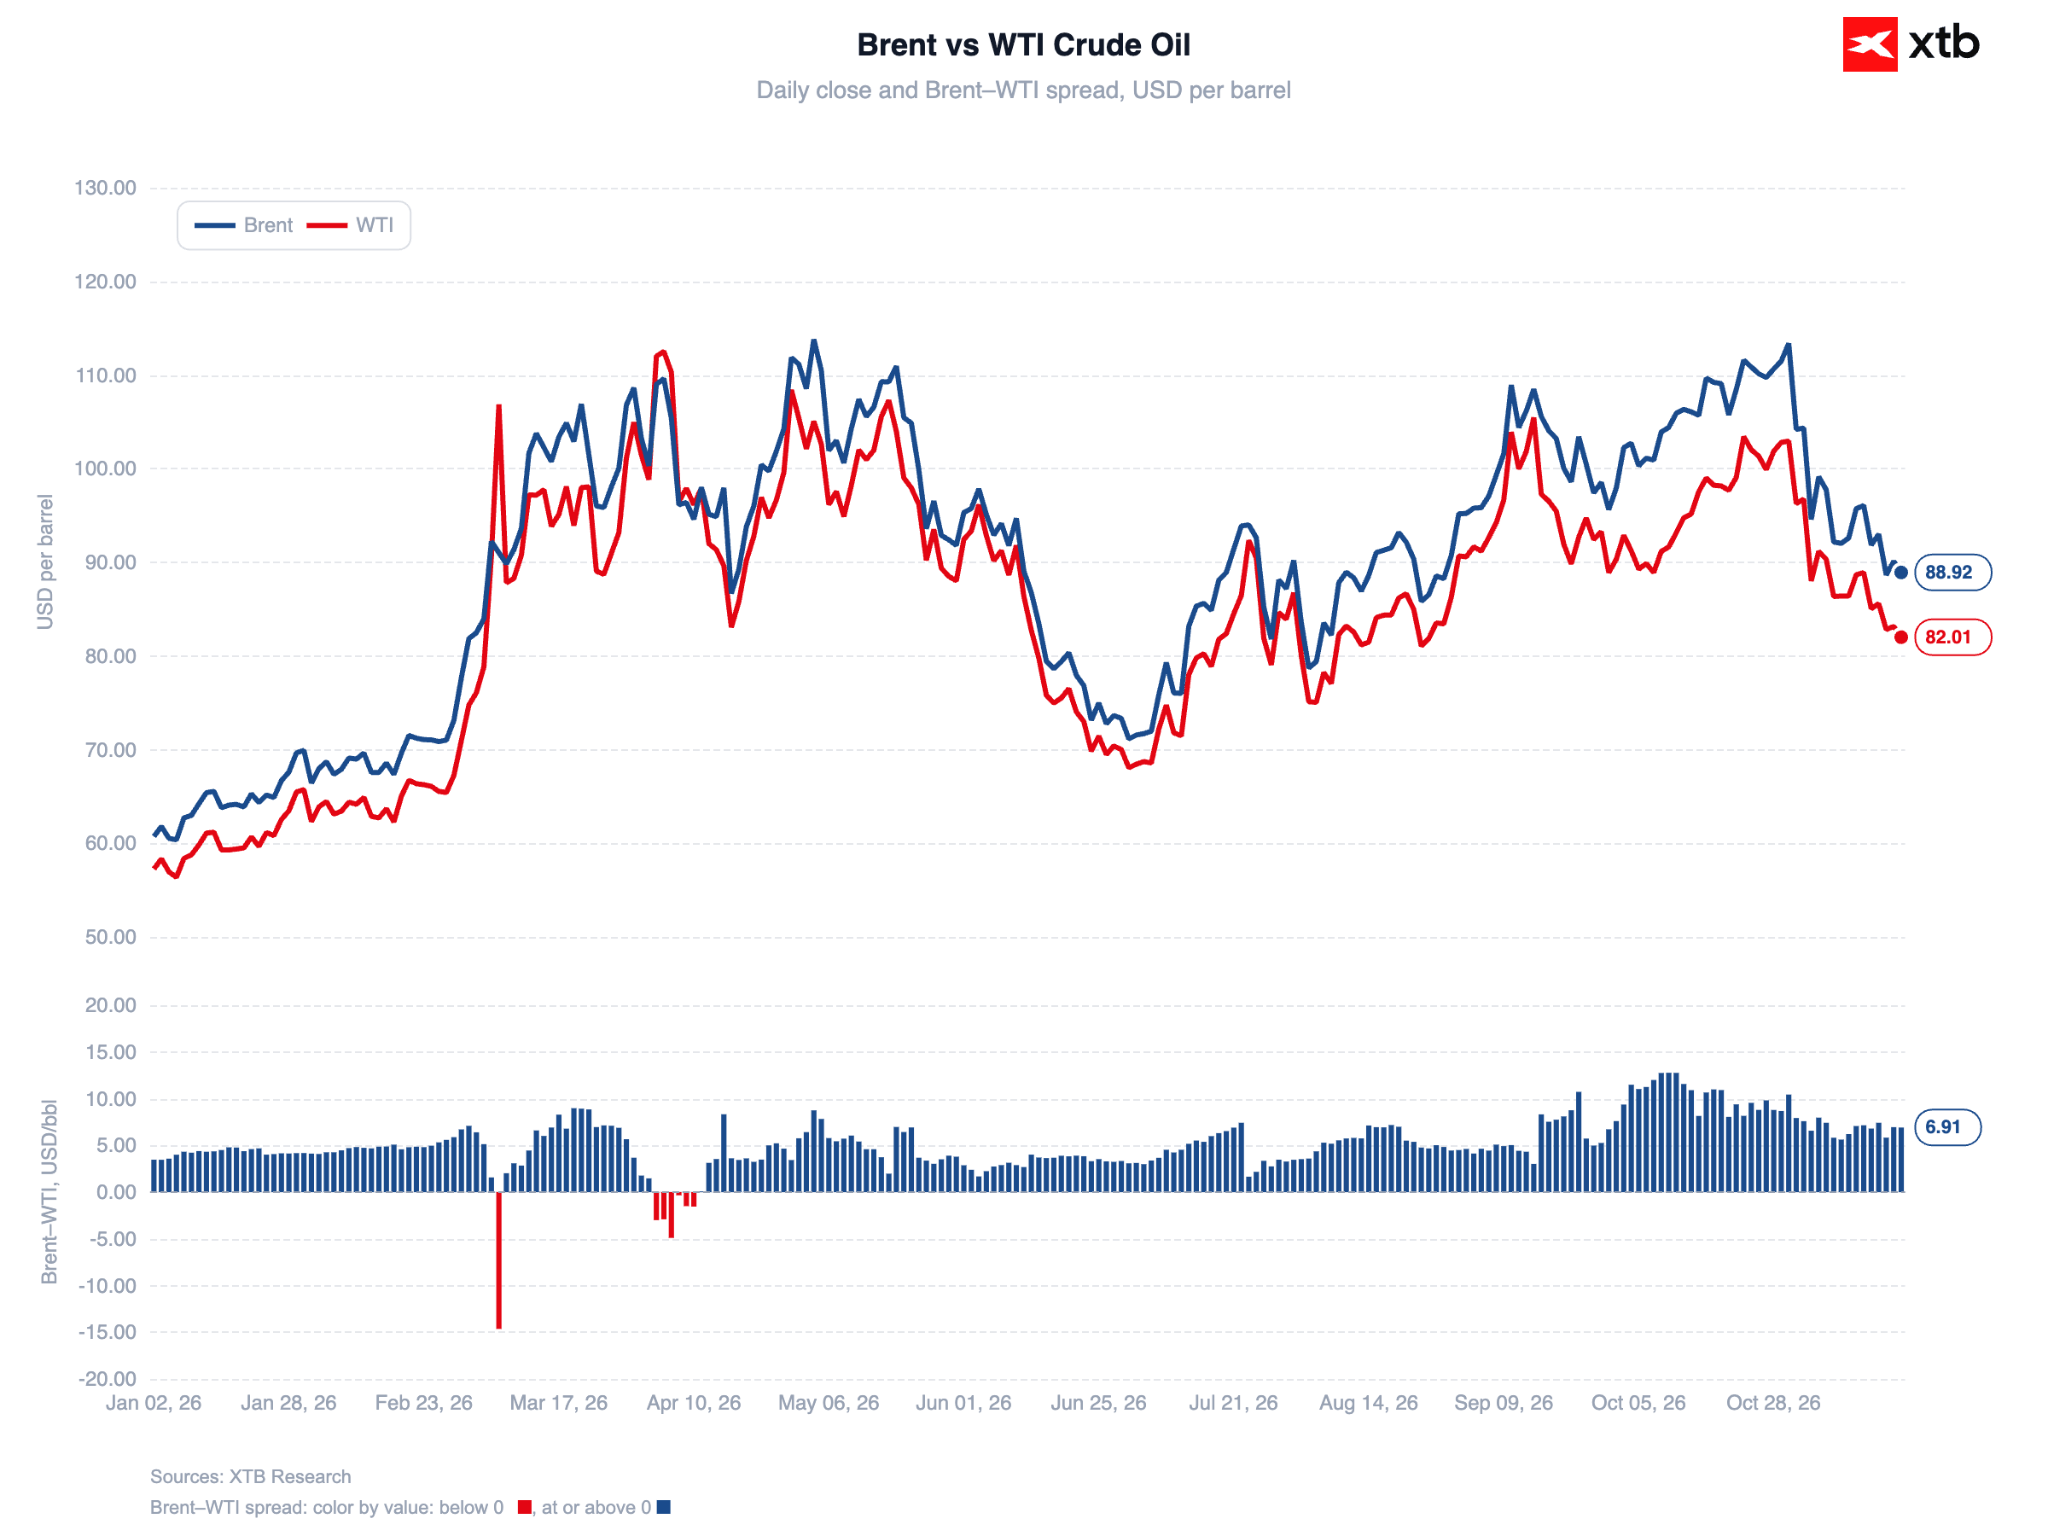
Brent crude is currently trading just under $90 per barrel, while WTI stands at around $82 (for February contracts following rollover). Oil is recording its third consecutive weekly decline. Since the beginning of the month, prices have dropped by more than 20%.
Figure 6: Brent and WTI Crude Oil (2026)
 Source: XTB Research, 20.11.2026
Oversupply is driving the decline. The International Energy Agency forecasts a surplus of around 2 million barrels per day for this quarter. Reports of armed incidents in the Middle East failed to halt the drop in oil prices.
Trump stated he is in no rush regarding a decision on Iran, while the US Energy Secretary reiterated that shipping flows through the Strait of Hormuz remain at record levels.
Precious Metals
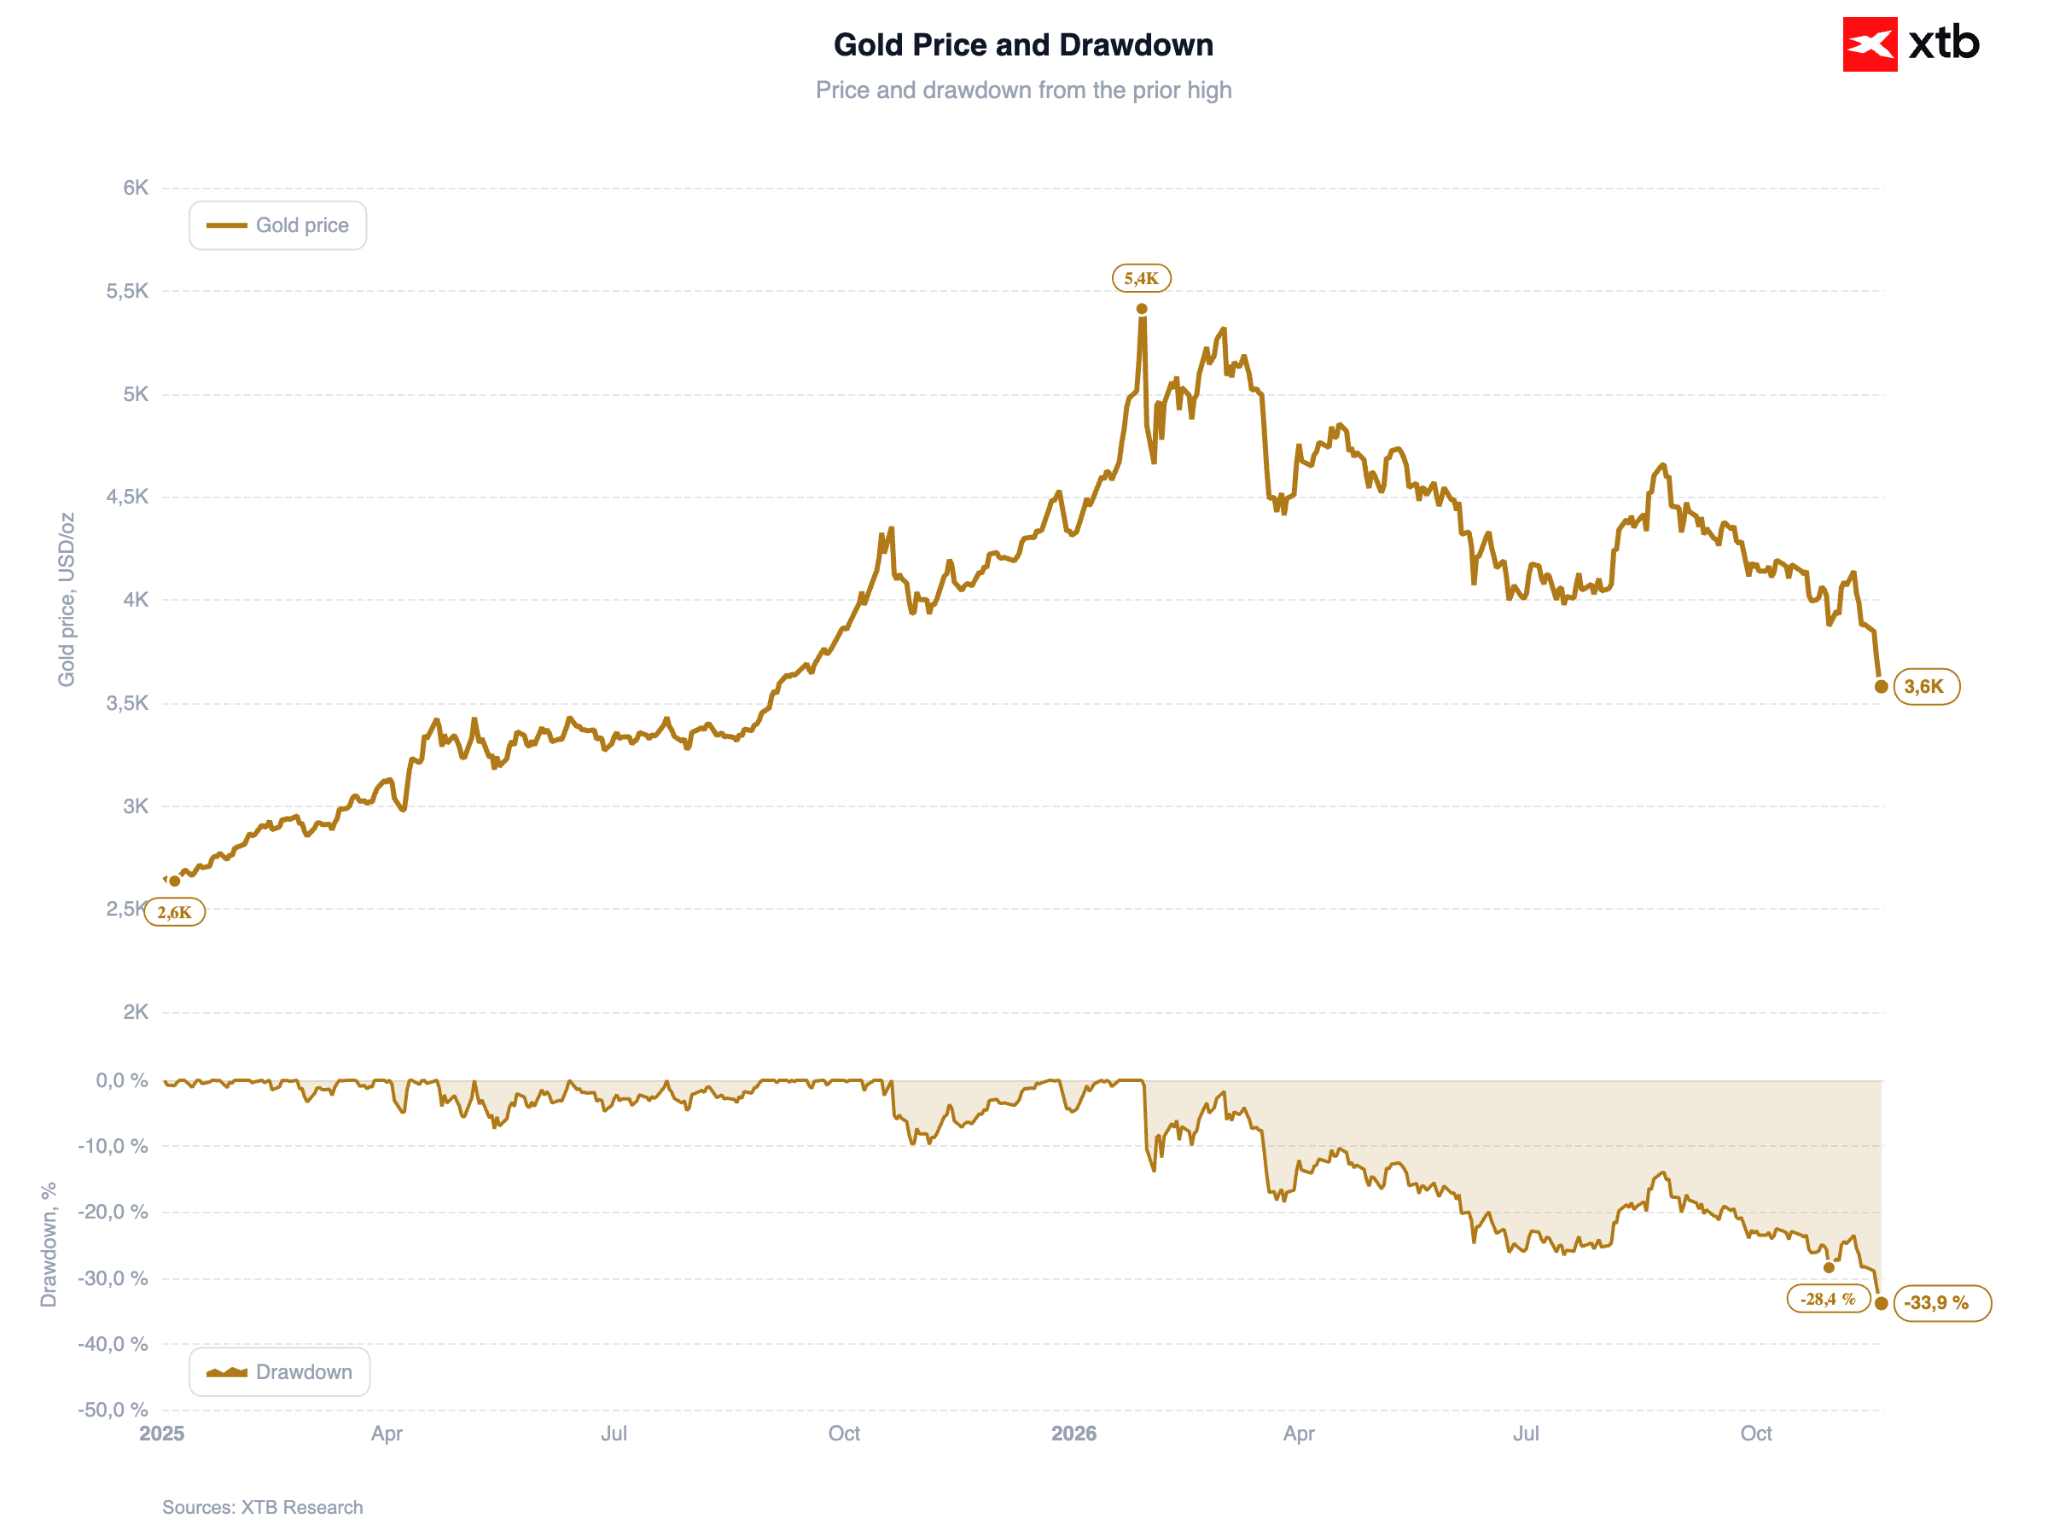
Gold fell below $3,600 per ounce, briefly touching $3,515 on Friday, its lowest level since September 2025. The metal is down nearly 9% this week, setting up its worst weekly performance since March. Silver, trading around $42 per ounce, is down nearly 14% on the week.
Figure 7: Gold (2025–2026)
 Source: XTB Research, 20.11.2026
Unusually hawkish signals from the Fed are maintaining pressure on precious metals. Further downward pressure comes from the stock market sell-off, as some investors liquidate metals positions to cover equity losses.
Currencies
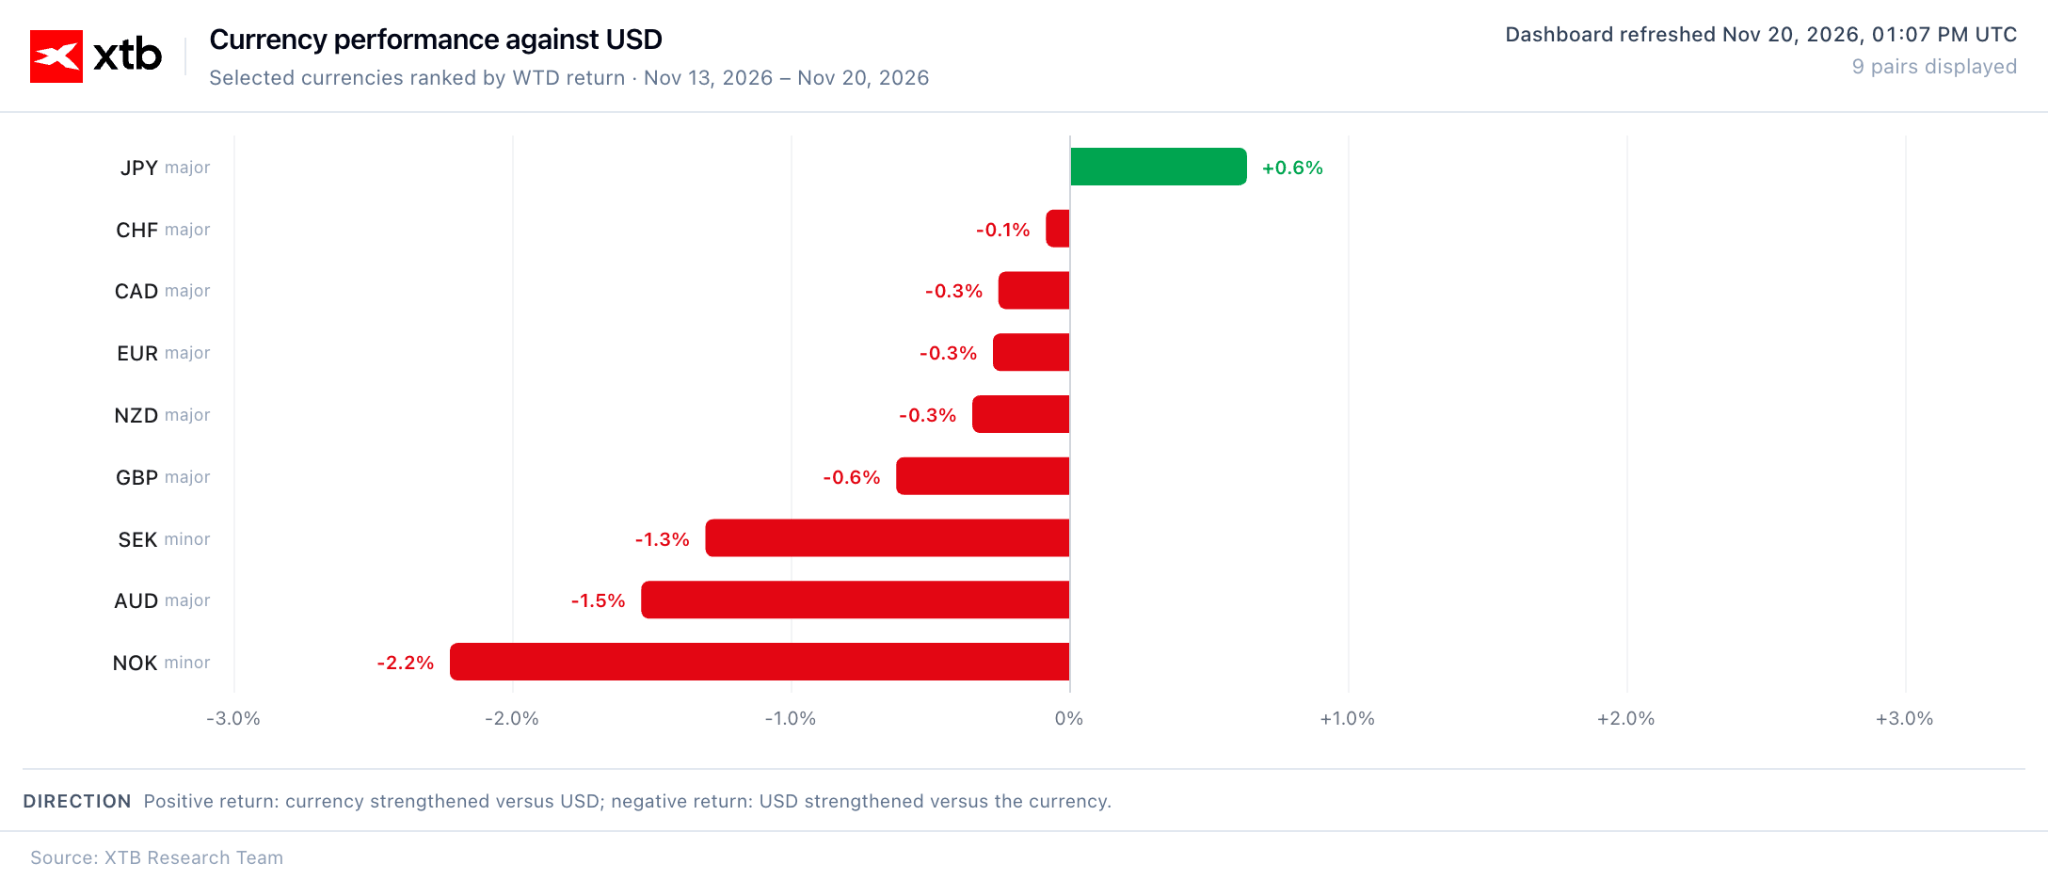
The Japanese yen is by far the strongest G10 currency today, benefitting from broader risk-off sentiment and a flight to traditional safe havens. USD/JPY is down 0.5% at 158.8. Emerging market currencies, including the Polish złoty, continue to post losses.
Figure 8: G10 Currency Performance (Current Week)
 Source: XTB Research, 20.11.2026
Cryptocurrencies
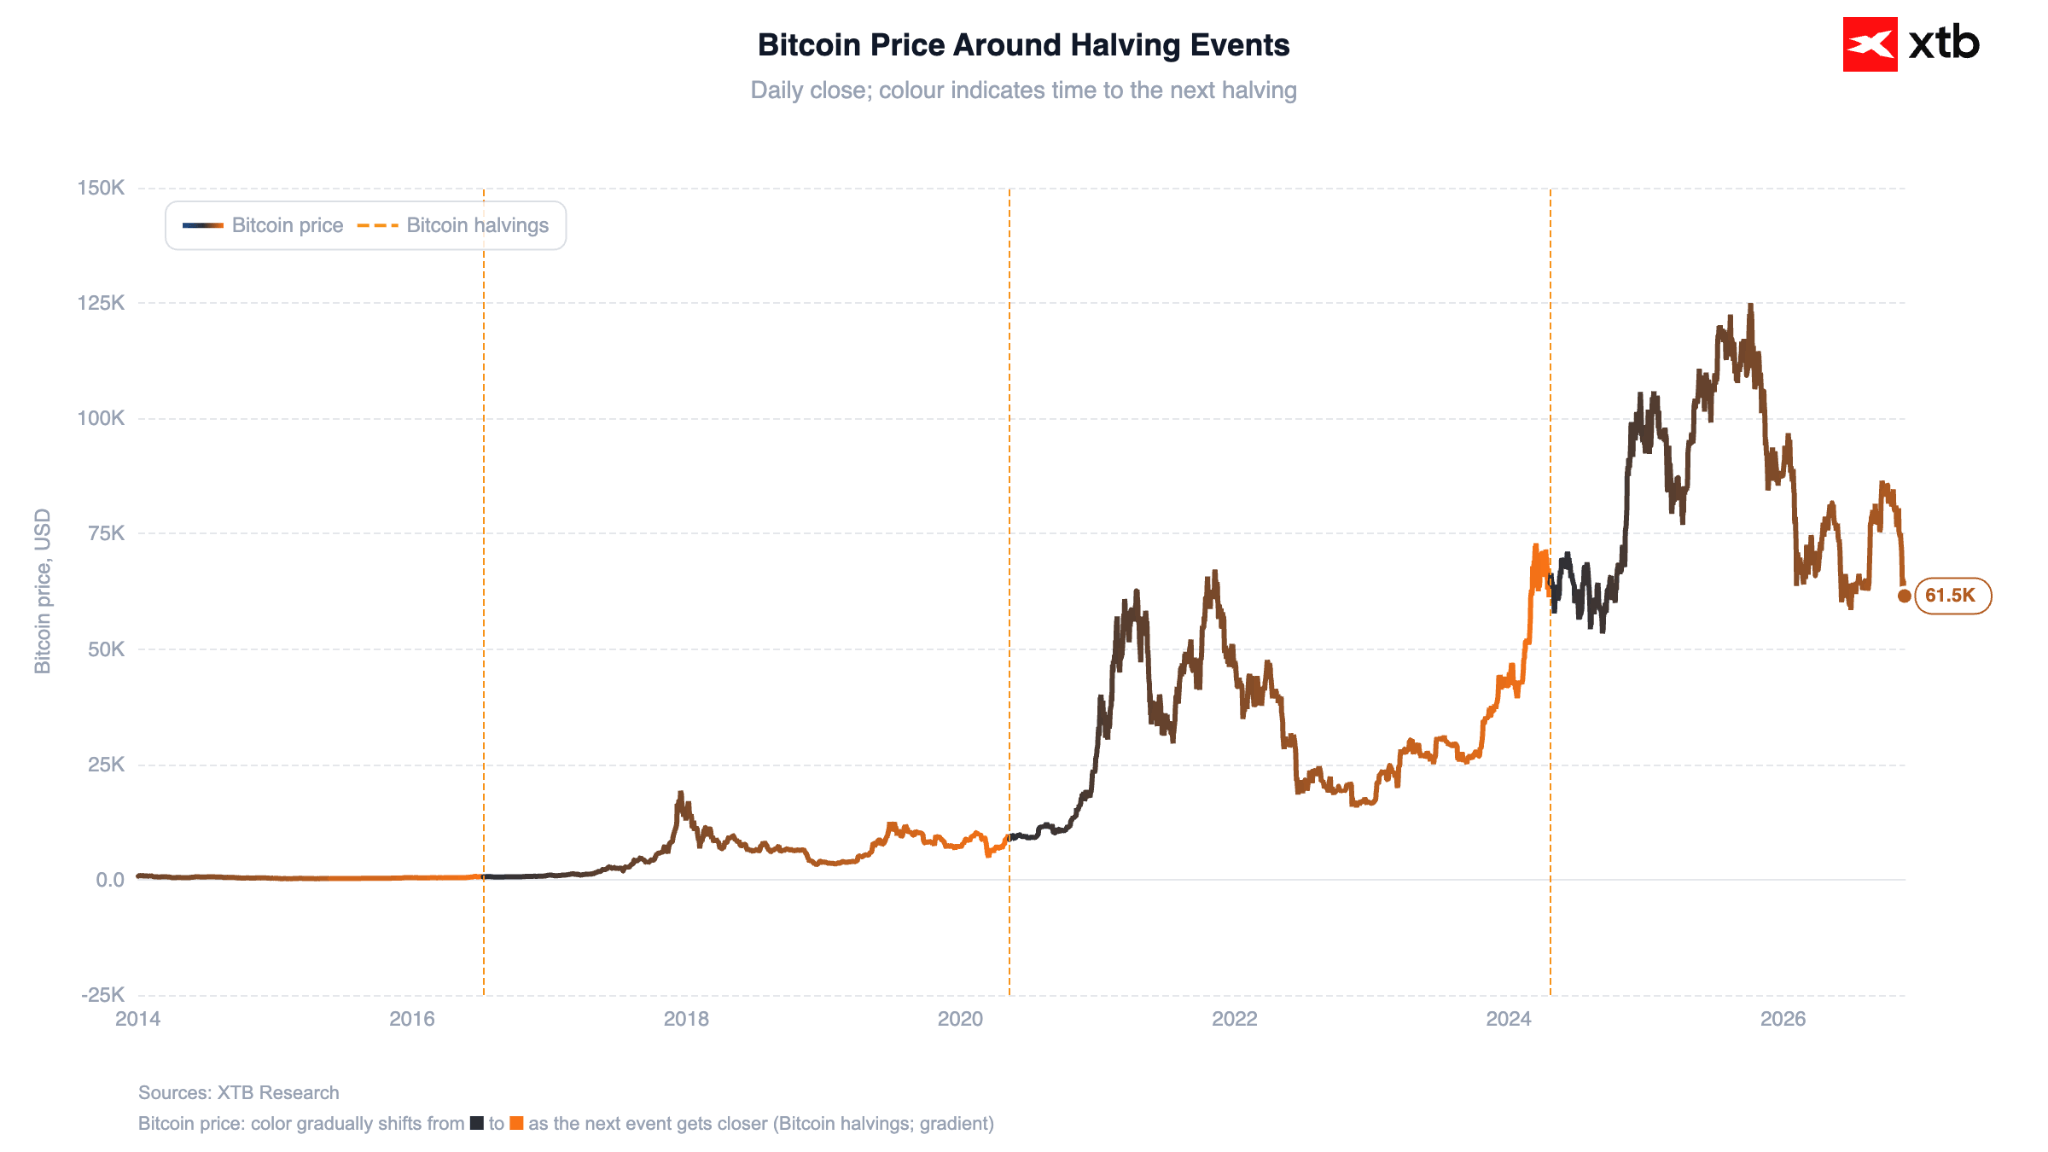
Bitcoin is trading around $61,500, while Ethereum stands at approximately $1,740. Both assets are losing less today than tech stocks, though they continue to follow the trajectory dictated by the AI sell-off.
Figure 9: Bitcoin (2014–2026)
 Source: XTB Research, 20.11.2026
—
Michał Jóźwiak, Financial Markets Analyst at XTB


Gold loses a third of its value. It's liquidity and the Fed, not peace in Shenzhen

Market Wrap: Anthropic Lifts Sentiment, but a Hawkish Fed Keeps the Dollar High


Palo Alto Earnings: Another Record Riding the Cybersecurity Crisis Wave


Economic Calendar: Trump-Xi Jinping-Putin summit ongoing, time for Walmart results (19.11.2026)
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.