


European stock indices continue to decline despite yesterday's sharp sell-off, as support from Nvidia's better-than-expected earnings proves insufficient to reverse the negative sentiment. The STOXX Europe 600 Index is edging lower, hovering near 651 points after Tuesday's 1.75% decline, its largest since March. Germany's DAX and France's CAC 40 remain close to flat, while the UK's FTSE 100 is down around 0.3%. Technology stocks remain in focus, with the sector index gaining 1.2% earlier in the session, supported by a 1.8% rise in ASML and an approximately 2% increase in ASM International, although some of these gains have since been erased. Nvidia's record results, including a 103% year-over-year increase in quarterly revenue to $115.8 billion, have eased concerns about the sustainability of AI infrastructure investment, but have not eliminated risks associated with elevated sector valuations and rising financing costs.
European mining stocks are performing considerably worse, with the sector index falling around 3% to its lowest level in nine months. Glencore is down approximately 3.5%, while German copper producer Aurubis is losing around 2.9%, reflecting further declines in industrial metal prices and a stronger US dollar. Against this backdrop, British data analytics company Experian stands out, with its shares rising approximately 3.7% following the release of its half-year results. Revenue exceeded analysts' expectations, while management announced an additional $500 million share buyback programme. Investors are also awaiting today's pricing of Anthropic shares as part of its IPO, which is expected to provide another important test of capital market appetite for the AI sector.
A key macroeconomic development today is the UK inflation report, which showed annual inflation accelerating to 3.6% in October from 3.5% in September, reaching its highest level in a year. Core inflation remained unchanged at 2.8%, while rising fuel prices added further pressure on household budgets. The figures reinforce expectations of additional monetary tightening by the Bank of England, complicating the outlook for the British economy. Investors are also awaiting the release of the minutes from the latest FOMC meeting, which could provide further insight into the Federal Reserve's willingness to raise interest rates again.
FX Market
-
EURUSD: The euro remains under pressure from a strong US dollar, with the pair trading around 1.0980–1.1000. Expectations of further Fed rate hikes are limiting the euro's recovery potential, while investors await today's FOMC minutes.
-
GBPUSD: The pound is down approximately 0.2–0.3%, retreating towards 1.3170. Higher-than-expected UK inflation supports the prospect of further Bank of England tightening, but has not been sufficient to strengthen sterling against the dollar.
-
USDJPY: The pair is stabilising near 159.2, recording a modest decline. The persistent yield differential between US and Japanese government bonds continues to favour the dollar, although the proximity of the 160 level is raising concerns about potential intervention by Japanese authorities.
-
USDPLN: The dollar remains near PLN 4.00–4.01. The prospect of persistently high Fed interest rates is limiting the zloty's appreciation potential, particularly amid elevated risk aversion.
Commodity Market
-
Gold: The metal is down approximately 2–2.5%, falling towards $3,770 per ounce. A stronger dollar and persistently elevated US Treasury yields are weighing on the precious metal's appeal despite ongoing geopolitical uncertainty.
-
Silver: Prices are falling by more than 3%, to around $45.7 per ounce. The metal is extending its multi-month sell-off, reflecting both hawkish expectations for Fed policy and weakening speculative demand for precious metals.
-
Natural Gas: US Henry Hub natural gas (NATGAS) is down approximately 0.6%, trading near $3.19 per MMBtu, while European TTF natural gas futures (NATGAS.EU) are also declining. Prices remain sensitive to weather forecasts, inventory levels and the outlook for winter gas demand.
EU50 and DE40 Charts (D1 Timeframe)
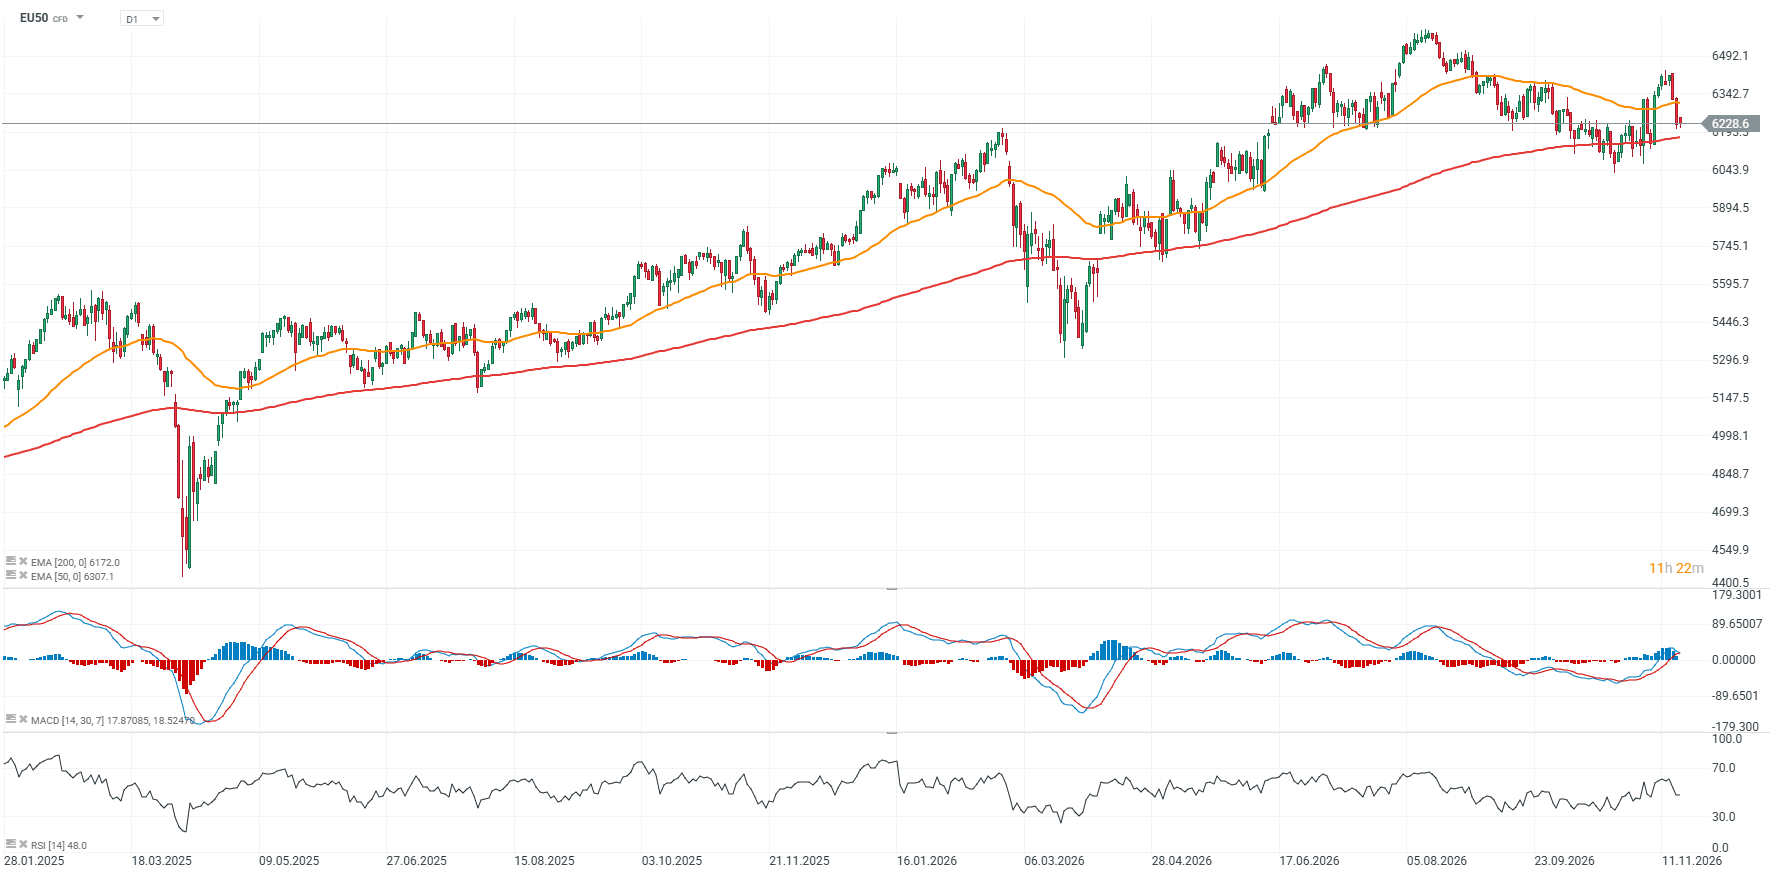 Source: XTB
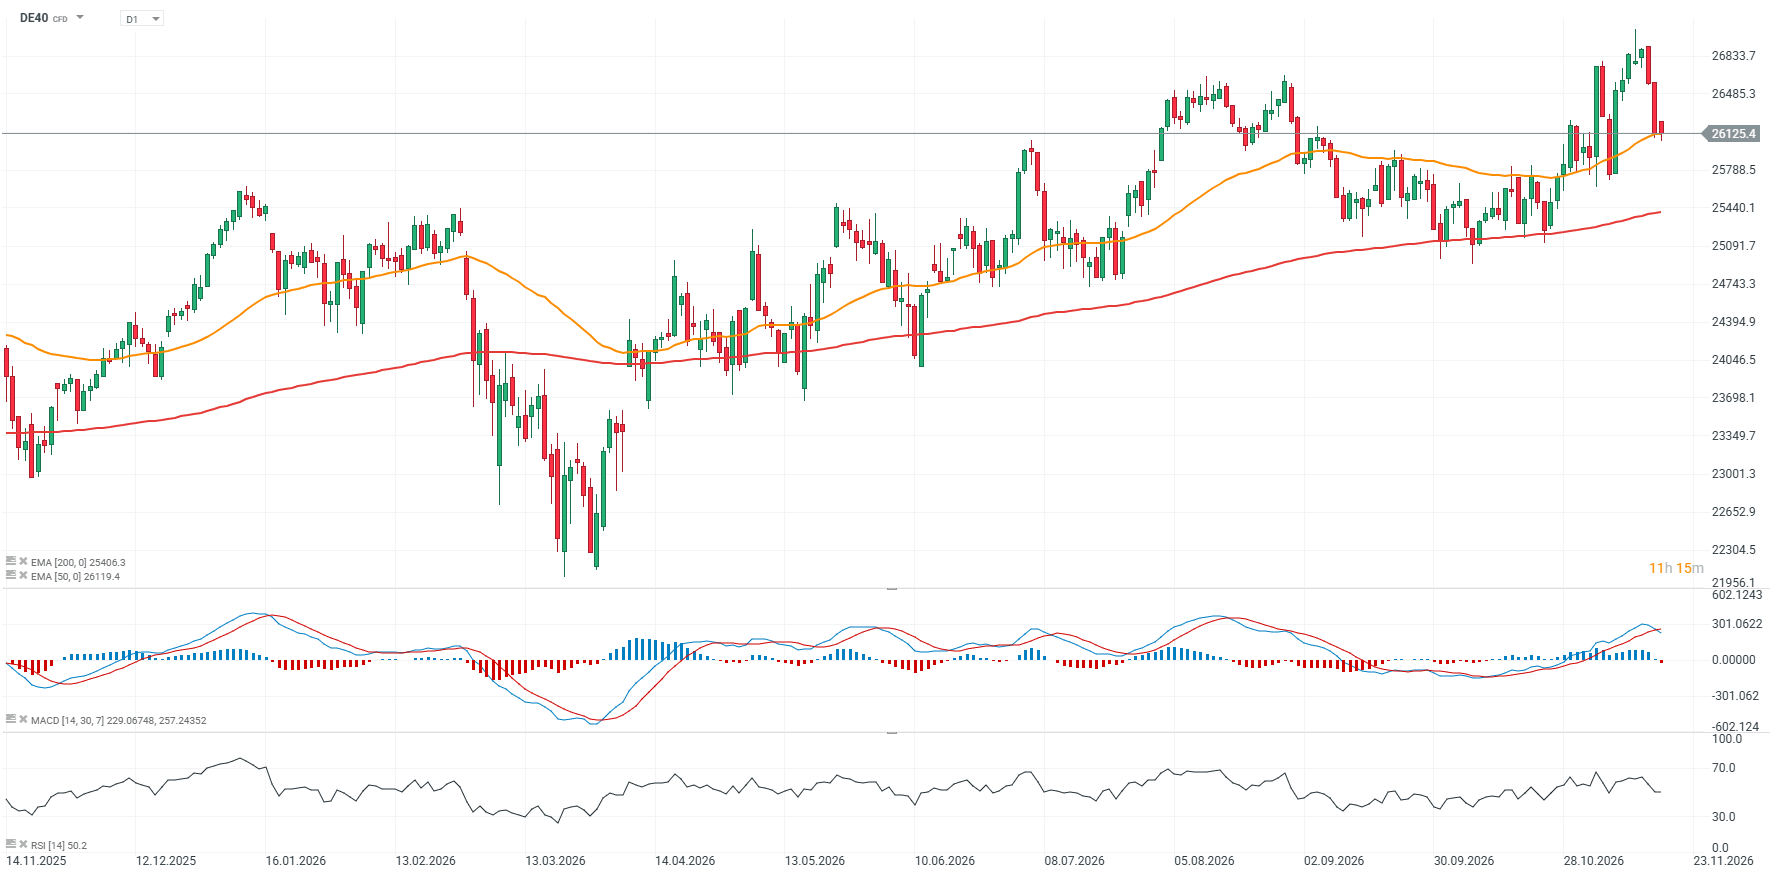 Source: XTB
Corporate News
-
ASML (ASML.NL) and ASM International (ASM.NL): European semiconductor equipment manufacturers are rebounding from yesterday's sell-off, supported by Nvidia's record earnings and optimistic outlook. The US chipmaker's report has improved sentiment across the AI sector, easing concerns about a potential slowdown in data centre investment. ASML is up approximately 1.8%, while ASM International is gaining nearly 2%.
-
Experian (EXPN.UK): Shares of the British credit data and analytics company are rising approximately 3.7% following better-than-expected half-year results. Revenue increased by 8% at constant exchange rates, while adjusted earnings per share rose by 15%. The company also announced an additional $500 million share buyback, bringing the total value of repurchase programmes announced in 2026 to $2.5 billion.
-
Glencore (GLEN.UK) and Aurubis (NDA.DE): European mining and metals companies are facing significant selling pressure amid falling copper prices and a strengthening US dollar. The STOXX 600 mining sector index is down around 3%, reaching its lowest level in nine months. Glencore is falling approximately 3.5%, while German copper producer Aurubis is losing nearly 2.9%.
-
Target (TGT.US): The US retailer reported significantly better-than-expected Q3 2026 results, with revenue reaching $27.07 billion versus forecasts of $26.53 billion and adjusted earnings per share of $2.65 compared with a consensus estimate of $2.08. Comparable sales increased by 5.6%, comfortably exceeding expectations of 3.66%, while gross margin improved to 30.5% from 28.2% a year earlier. The company raised its full-year adjusted EPS guidance to $10.65–$11.40 from the previous range of $9.90–$10.90. Management also expects net sales growth of approximately 6% and an operating margin of around 6.2%, indicating improving business profitability.
-
Lowe's (LOW.US): The US home improvement retailer delivered better-than-expected Q3 2026 results, reporting adjusted EPS of $3.10 versus analysts' expectations of $2.92. Comparable sales rose by 1.8%, significantly above the consensus forecast of just 0.37%. The company raised its full-year comparable sales growth outlook from 0% to 0.5%, while its projected annual revenue now stands at $92.5 billion. However, management maintained its adjusted EPS guidance at approximately $12.25, slightly below analysts' expectations of $12.35, and lowered its operating margin forecast from 11.6% to 11.5%, signalling continued pressure on profitability.
ASML Stock Chart (D1 Timeframe)
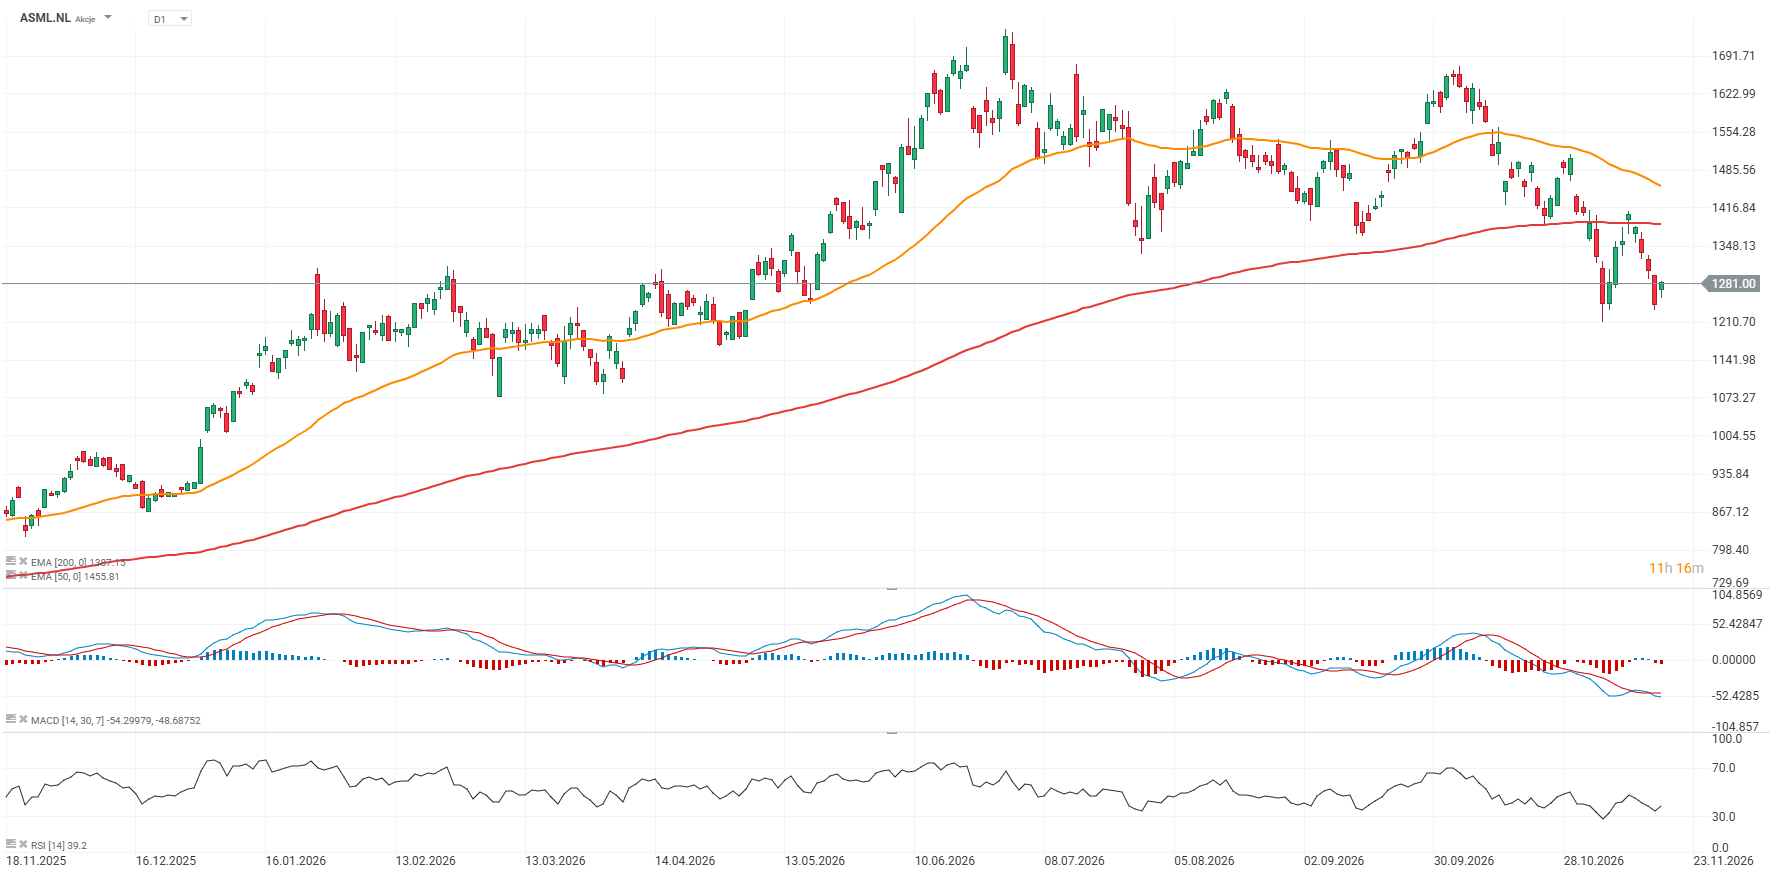 Source: XTB


Morning wrap (18.11.2026)

Nvidia rebounds 4% after earnings 🔼 Can the AI giant lift Wall Street?
Daily summary: Wall Street slips ahead of the Nvidia quarterly earnings report


Shares of Nike drop despite business turnaround 🚩Disney and Home Depot after earnings reports
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.