

- Global equity indices are rebounding as renewed confidence in artificial intelligence drives buying interest.
- Asian markets surged significantly, led by strong gains in semiconductor manufacturers and memory chip producers.
- The Fed interest rate decision and upcoming earnings reports from Alphabet and Microsoft pose key tests.
- Crude oil prices hold near 110 USD per barrel amid diplomatic talks regarding the US-Iran conflict.
Markets are rebounding from the recent sell-off in technology shares. After weeks of investors dumping anything associated with artificial intelligence, buying interest has returned today, with equity indices from Tokyo to New York trading in positive territory.
However, the recovery faces an immediate test tomorrow when the Fed announces its interest rate decision and both Alphabet and Microsoft publish their quarterly earnings results.
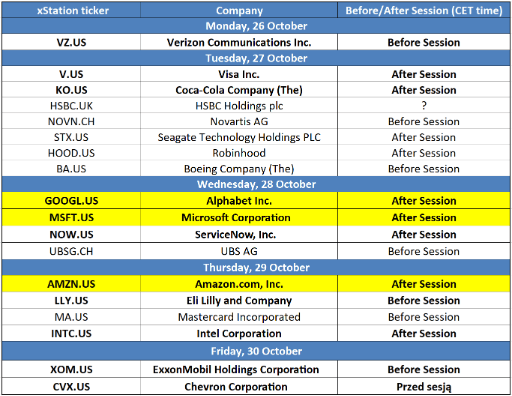
Table 1: Earnings Calendar for This Week (26.10.2026 - 30.10.2026)
 Source: XTB Research, 27.10.2026
Stock Market
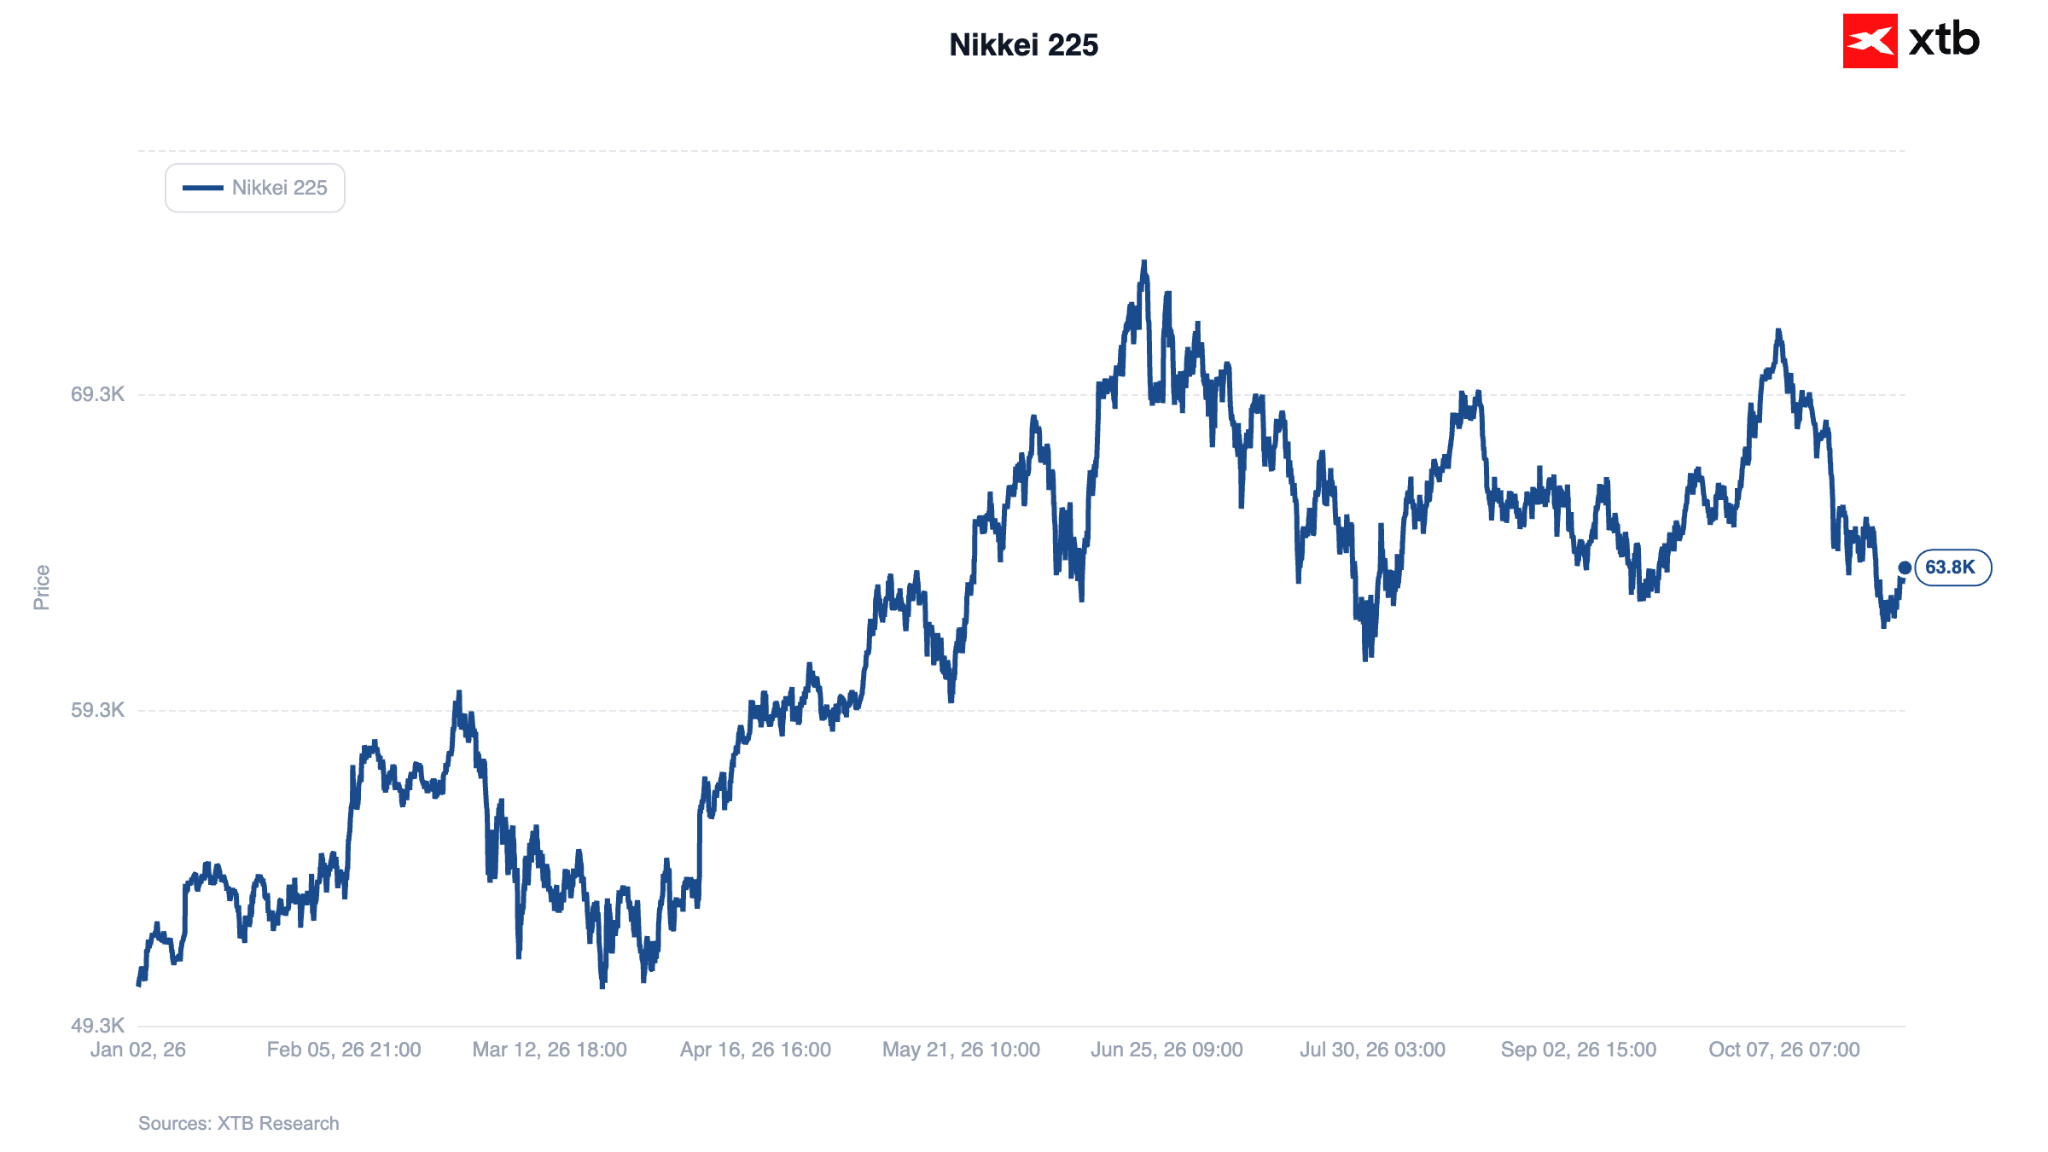
An improvement in market sentiment was already evident during Asian trading hours. South Korea's KOSPI surged by 3.1%, driven by local memory chip manufacturers SK Hynix and Samsung ahead of their quarterly reports scheduled for this week. Meanwhile, Japan's Nikkei 225 gained 1.7%, supported by rallies in semiconductor equipment suppliers such as Tokyo Electron and Advantest.
Figure 1: Nikkei 225 (2026)
 Source: XTB Research, 27.10.2026
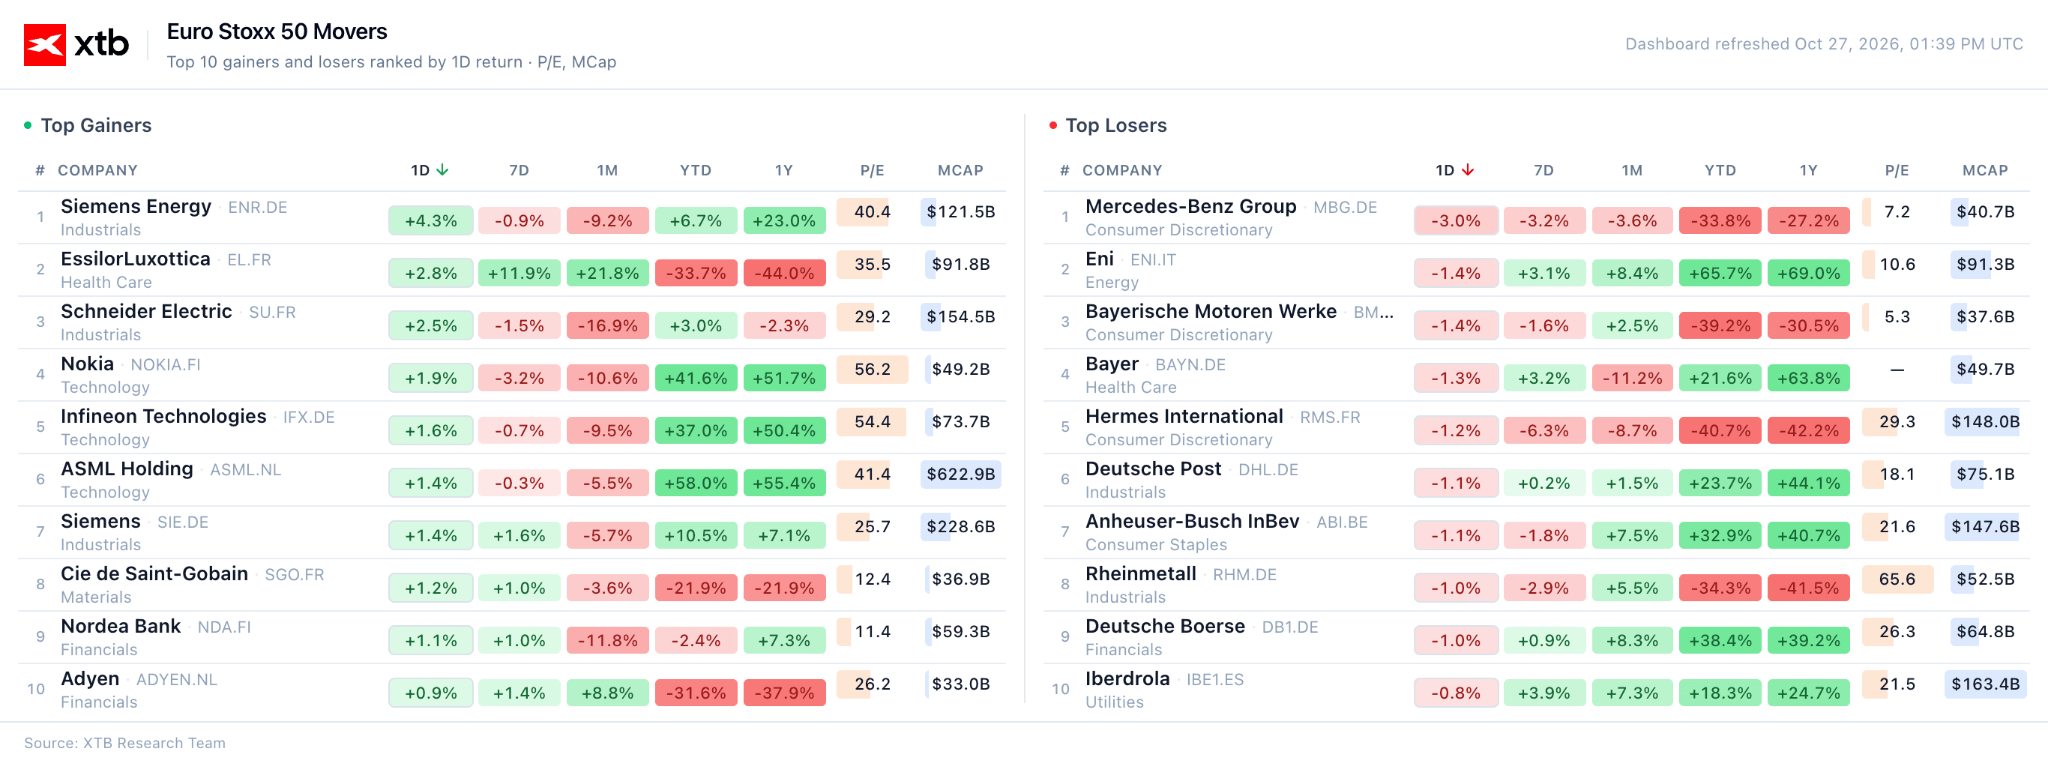
Gains across the European continent remain considerably more muted. The Stoxx 600 edged up slightly (+0.2%), while the DAX and CAC 40 rose by around 0.3% to 0.4%. The UK's FTSE 100 noticeably lagged (-0.9%), dragged down by a 6% drop in HSBC following its results (more on this below).
Table 2: Gainers and Losers in Euro Stoxx 50 (27.10.2026)
 Source: XTB Research, 27.10.2026
Nasdaq 100 futures point to a continued recovery in the US.
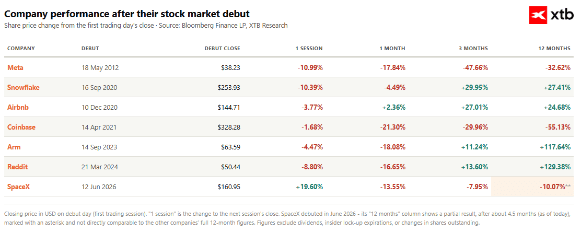
The turnaround was sparked by a series of major AI-related transactions, which the market interpreted as proof that demand for the technology remains robust. Three substantial deals surfaced within days: Anthropic's IPO filing, Meta's equity offering of up to $95 billion, and $63 billion secured by Broadcom from four Wall Street banks to fund proprietary chips and lease them to Anthropic.
Just a week ago, sums of this magnitude might have triggered a sell-off as further evidence of reckless spending; this time, investors viewed them as a signal of genuine demand. Semiconductor stocks benefited, with the Philadelphia Semiconductor Index rising 2.8% yesterday, its largest single-day gain in a month, despite Anthropic reporting a net loss of nearly $81 billion for the first half of the year in its IPO filing.
Table 3: Post-IPO Stock Performance (2012 - 2026)
 Source: XTB Research, 27.10.2026
In US pre-market trading, chipmakers lead the gains today: Broadcom +3.3%, Micron +2.6%, Intel +2.1%, AMD +1.6%, and Nvidia +1.1%. Microsoft (-0.6%) is underperforming as it awaits the release of its Q3 financial results.
Sentiment was also boosted by today's earnings reports from non-tech sectors.
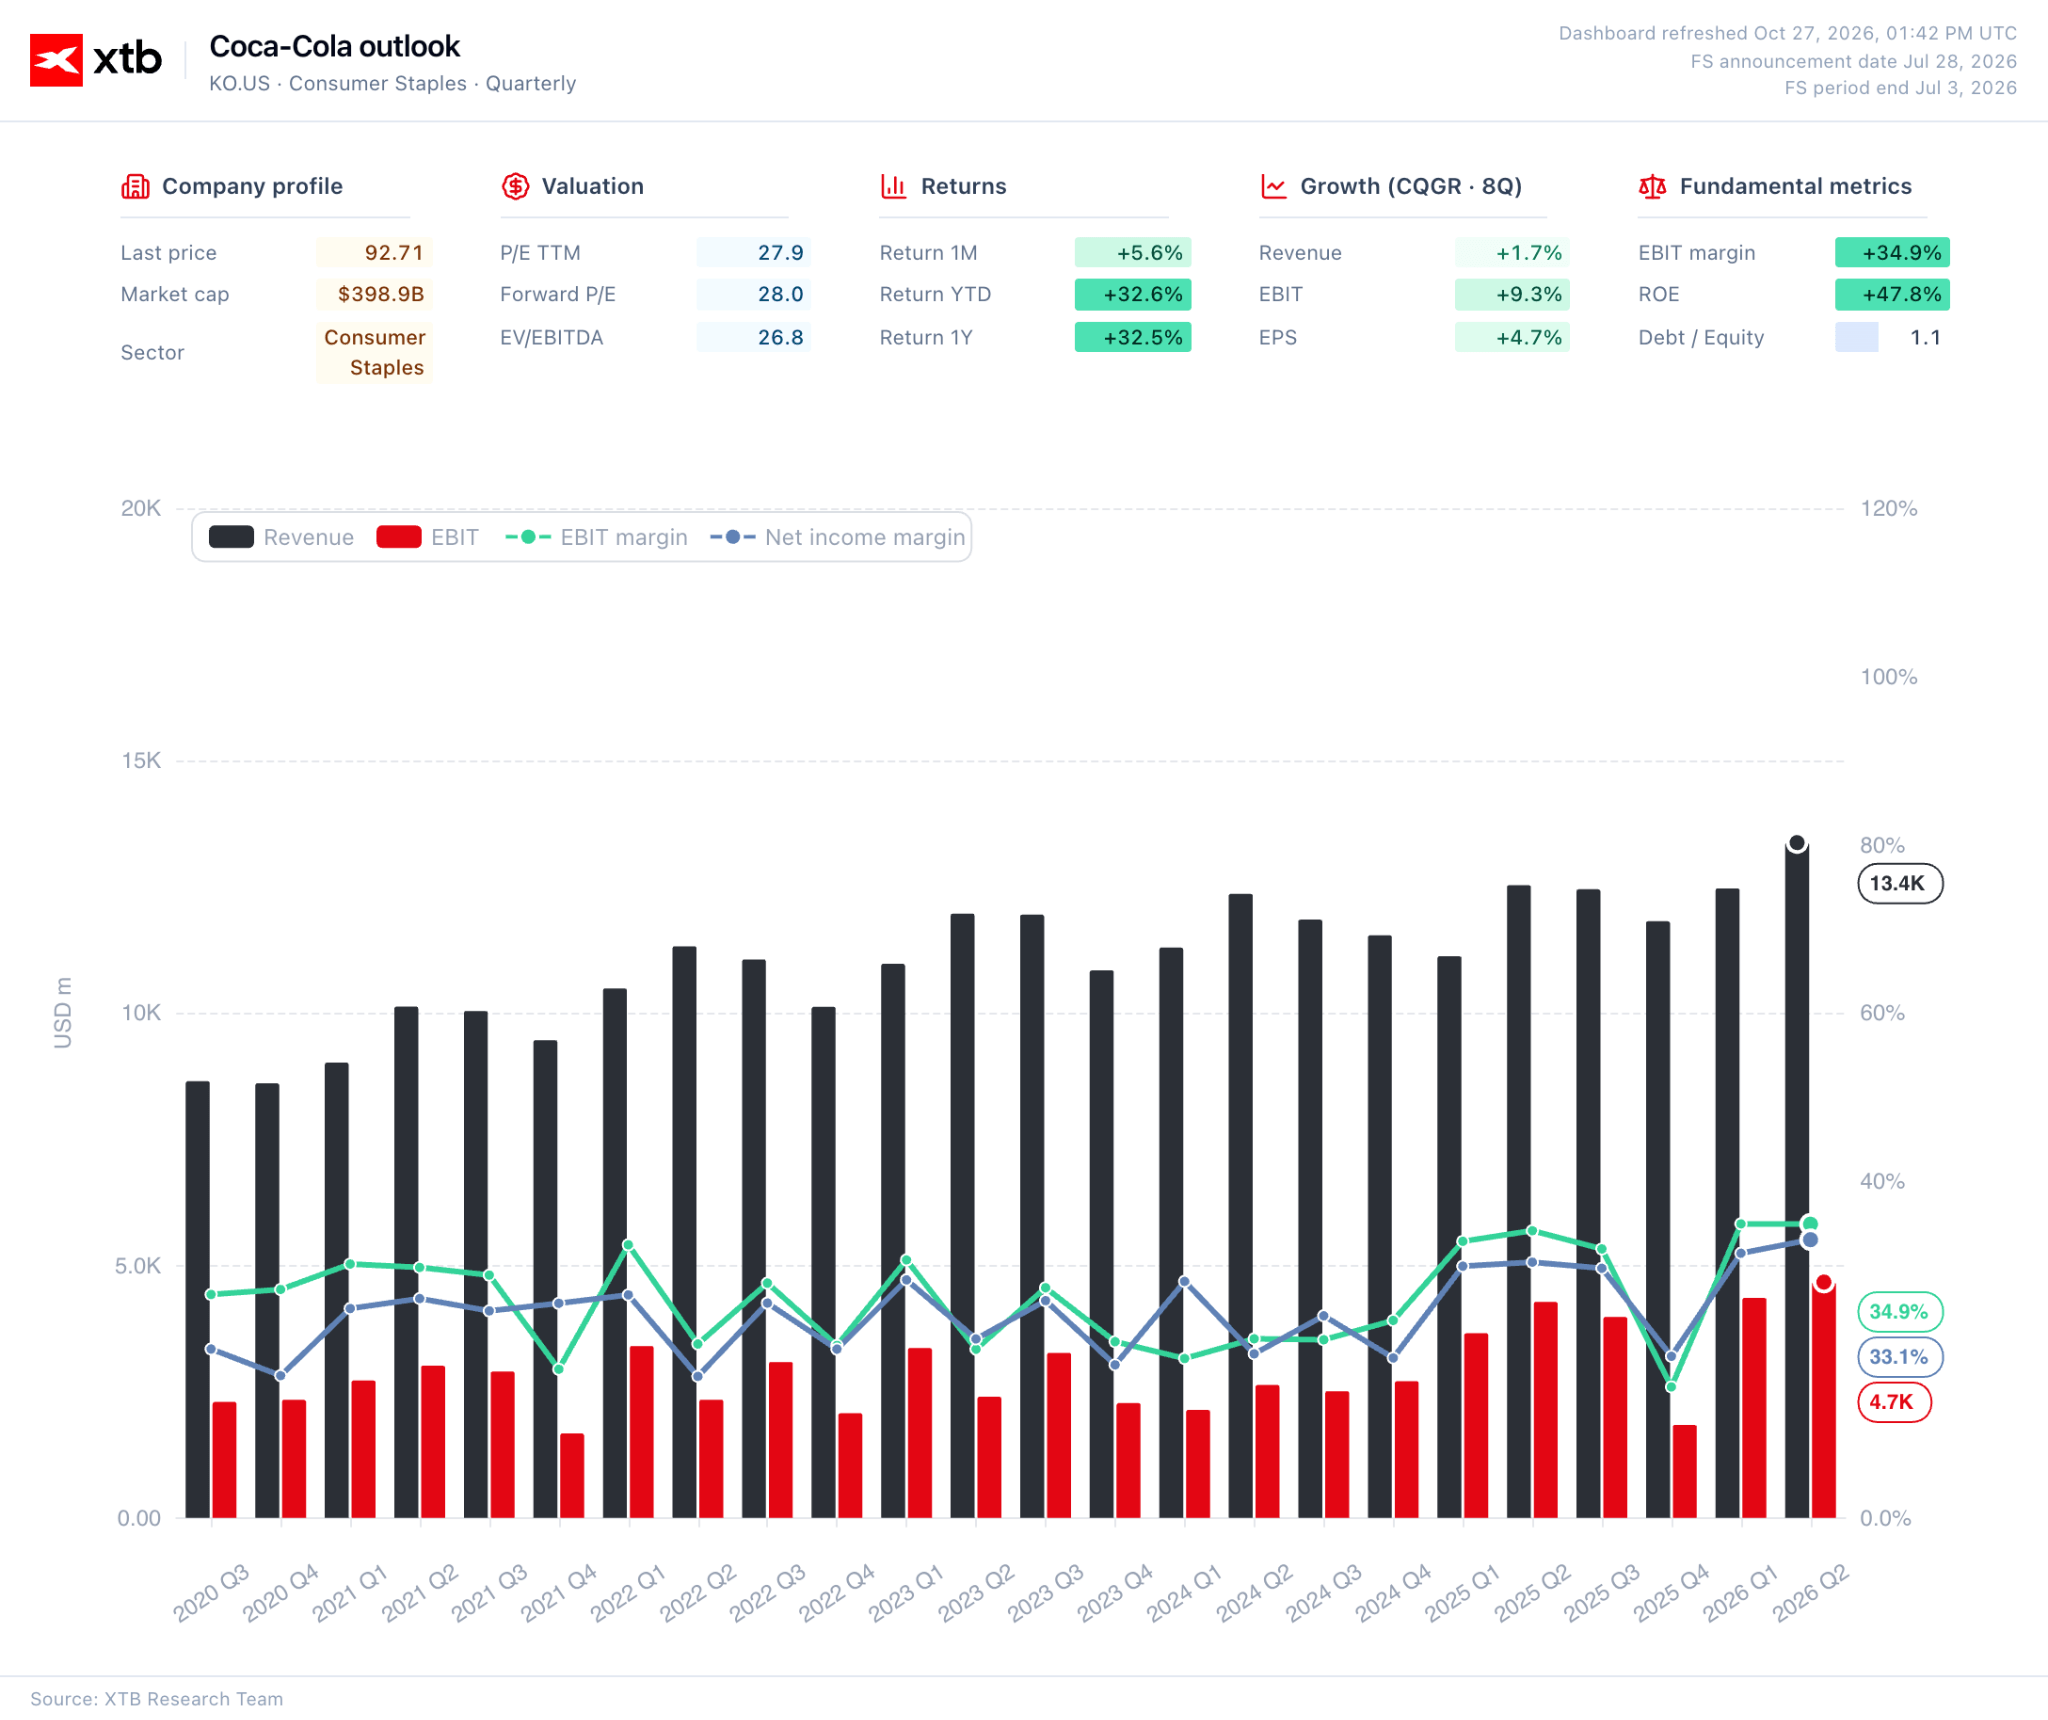
- Coca-Cola increased revenue by 7% to $13.4 billion, while its adjusted earnings per share rose 11% to $0.91, supported by a 5% increase in global sales volume. The company also raised its full-year guidance.
Figure 2: Coca-Cola Outlook (2020 - 2026)
 Source: XTB Research, 27.10.2026
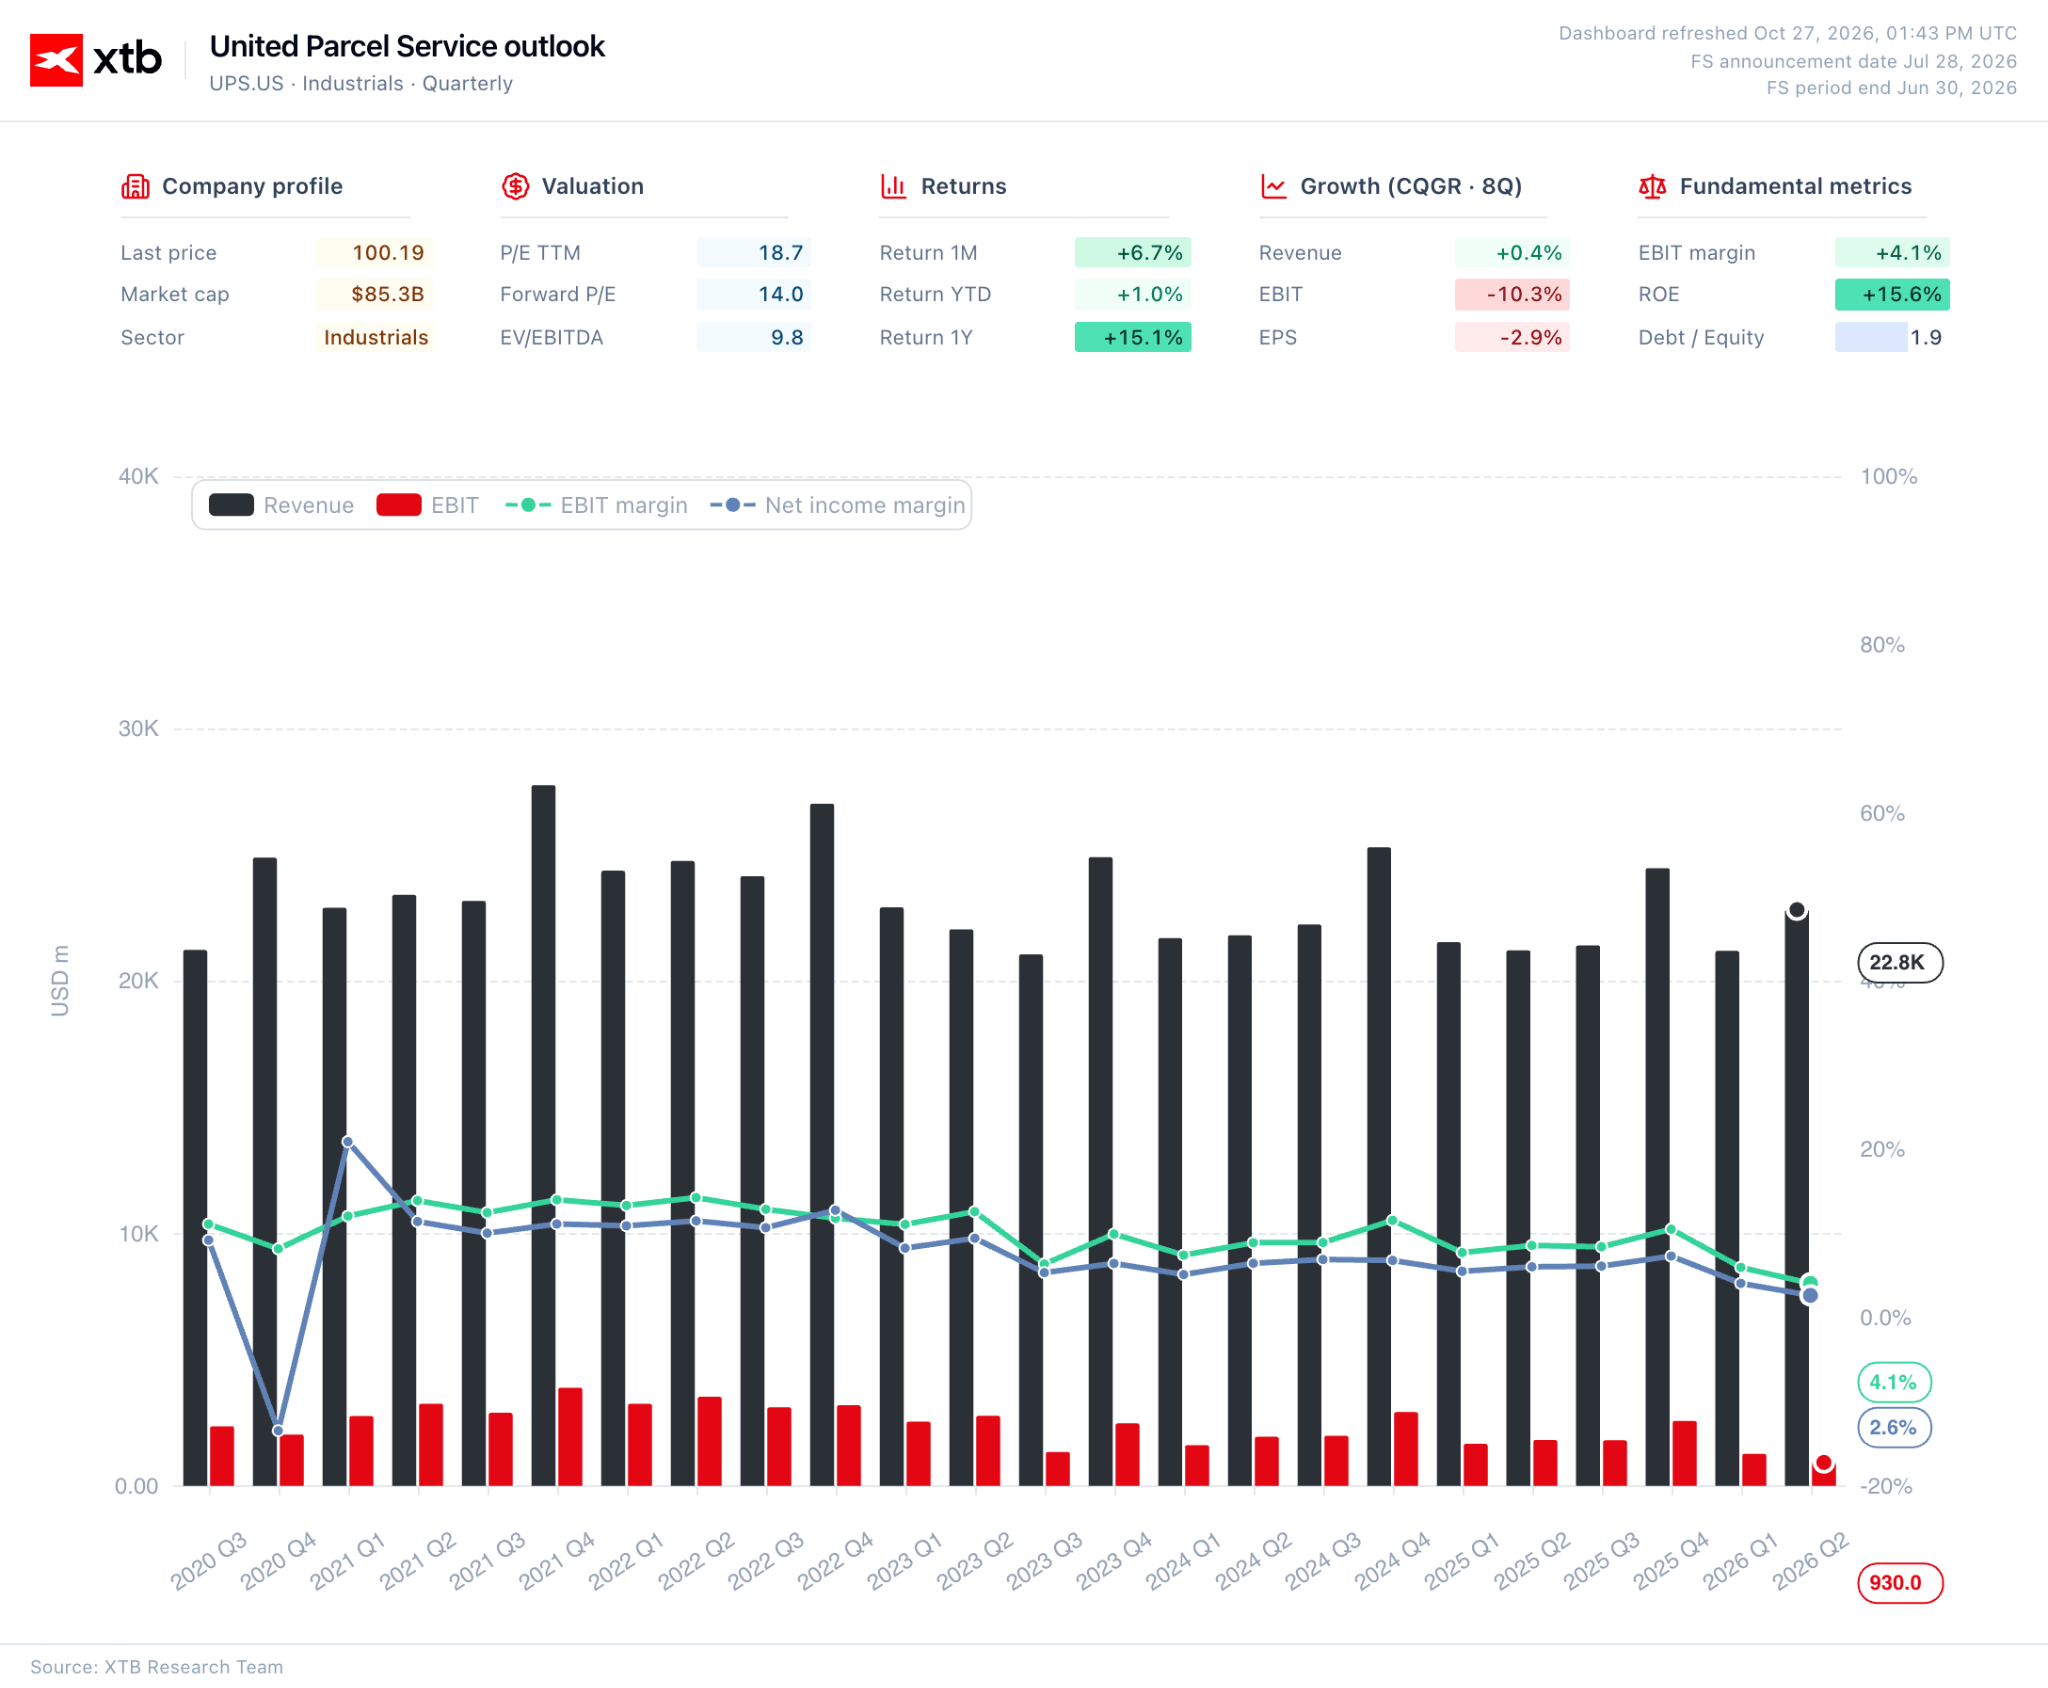
- Similarly, UPS, widely viewed as a bellwether for trade and economic health, grew revenue by 6.7% to $22.9 billion, delivered adjusted EPS of $1.69, and likewise upgraded its outlook ahead of the peak holiday season.
Figure 3: UPS Outlook (2020 - 2026)
 Source: XTB Research, 27.10.2026
However, performance was not uniformly positive across all sectors.
- In Europe, HSBC disappointed as profit fell short of expectations and the bank failed to raise its net interest income forecast despite high interest rates, leading to a share price drop of around 6%.
- Porsche fared better (+4.1%), maintaining profitability despite a further decline in vehicle sales.
Energy Commodities
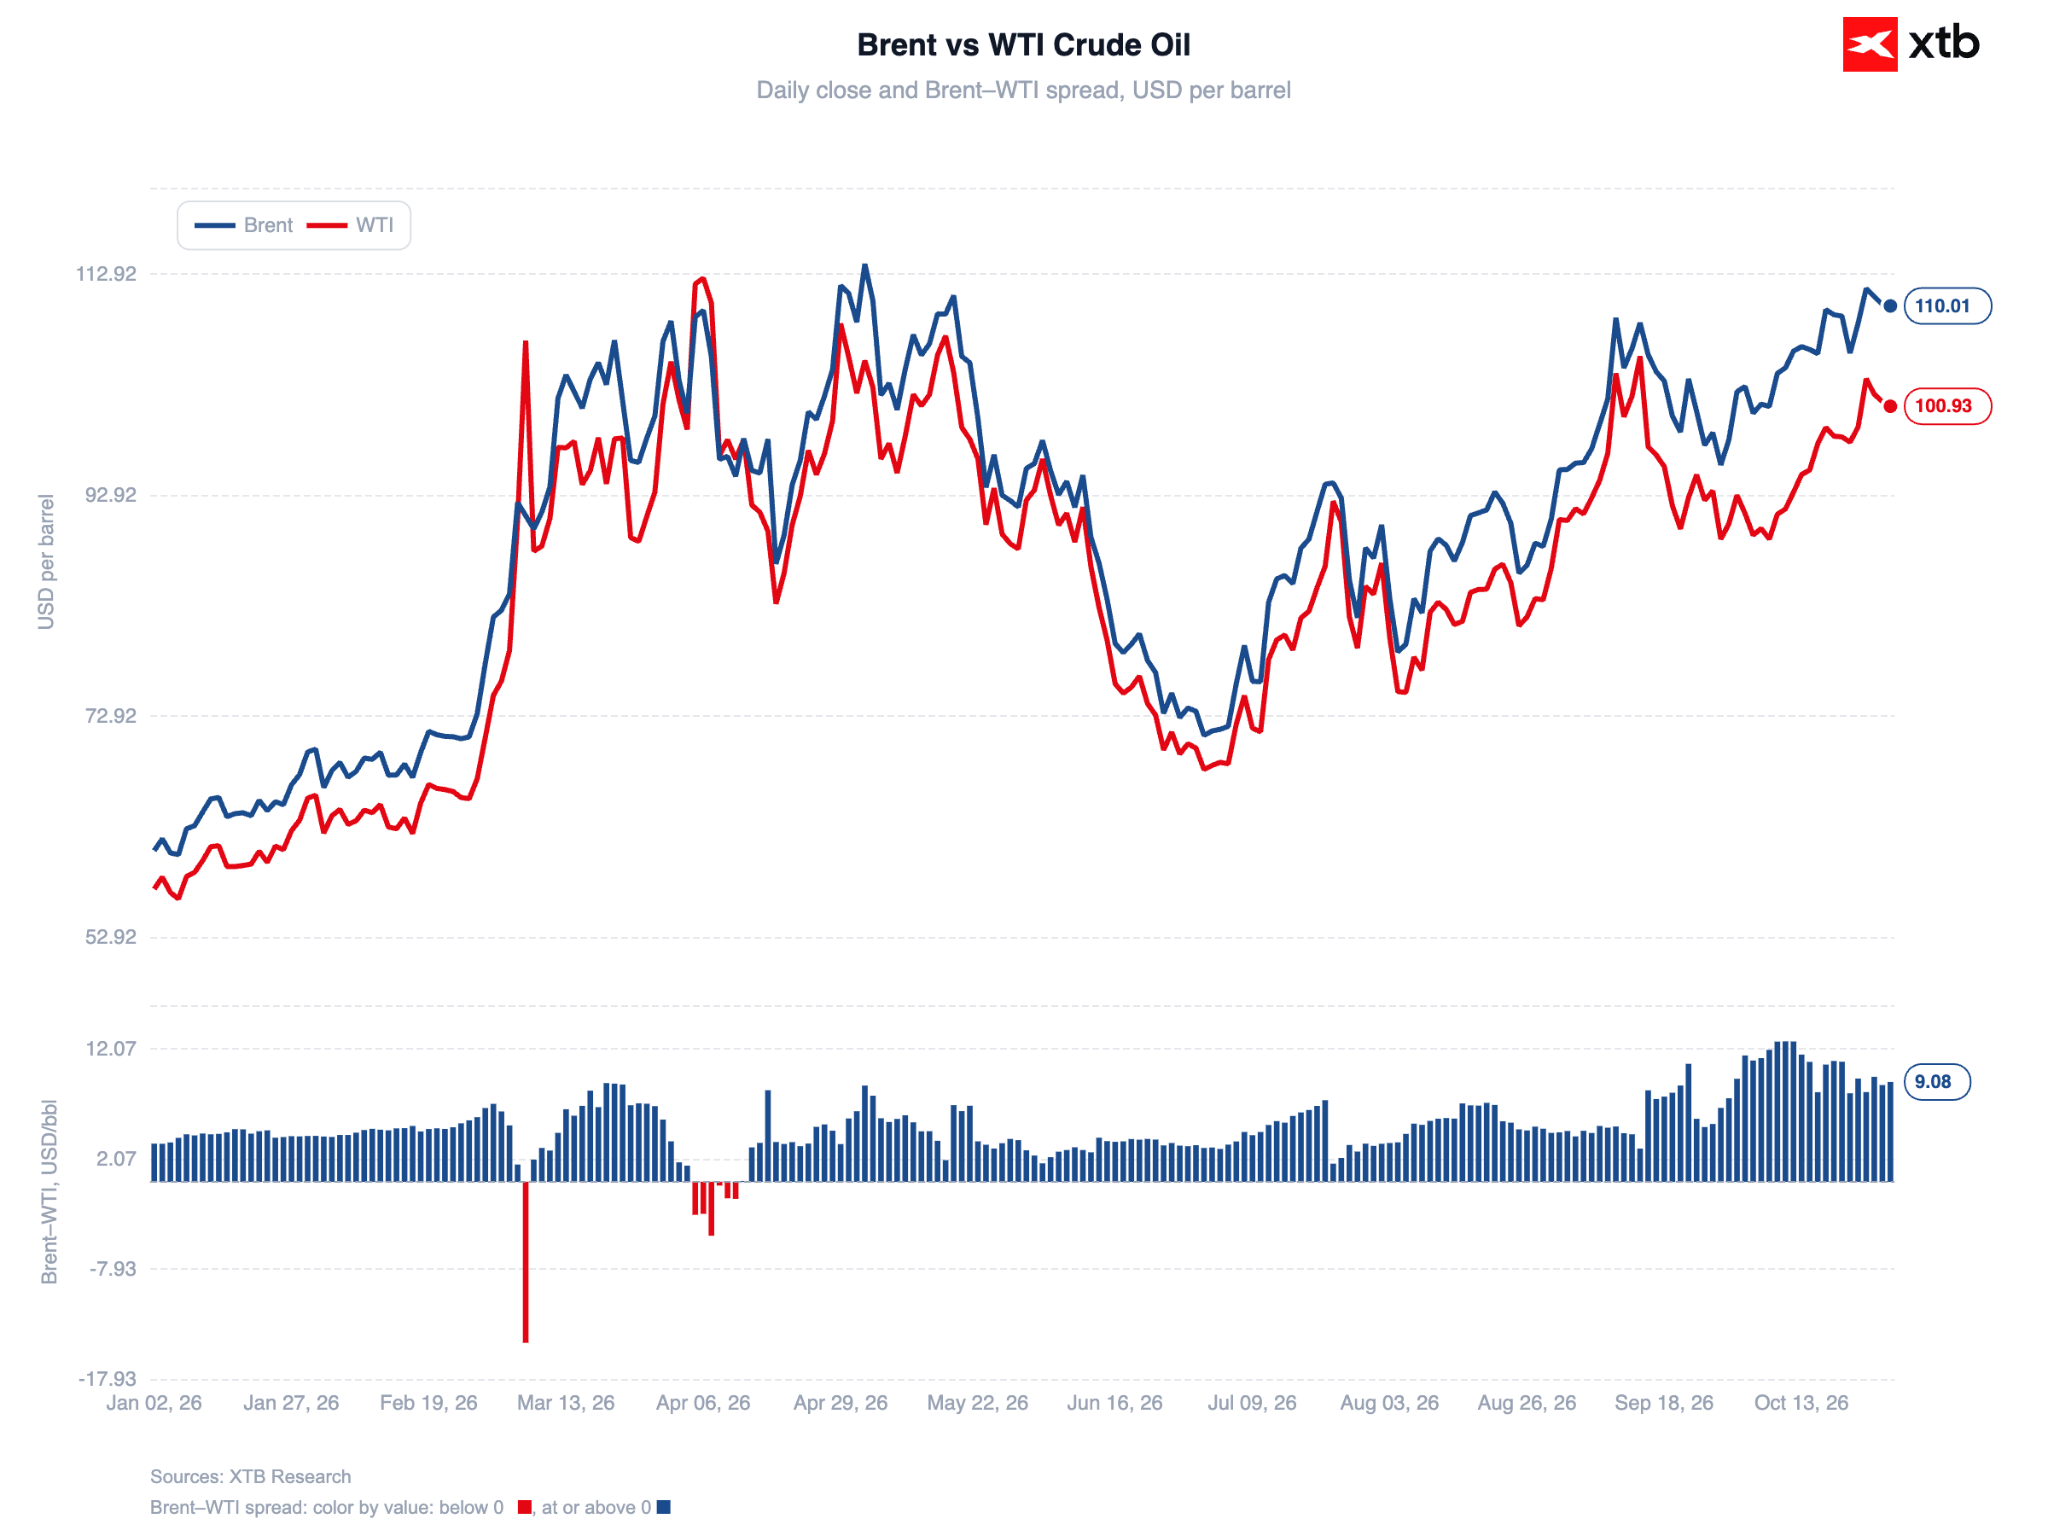
Against the backdrop of the stock market rally, crude oil remains surprisingly calm today. Brent crude (January contract) is holding around $110 per barrel, recording a modest decline of about 0.6% following recent sharp gains.
Figure 4: Brent and WTI Crude Oil (2026)
 Source: XTB Research, 27.10.2026
This slight pullback can be attributed to initial, tentative diplomatic signals: representatives from Saudi Arabia, Pakistan, and Turkey travelled to Tehran to discuss ending the US-Iran war. However, the talks yielded no breakthrough, with the parties agreeing only to continue discussions, while Iranian Supreme Leader Mojtaba Khamenei reiterated Iran's firm conditions.
Geopolitics
In Israel, elections are underway today, the first since the Hamas attack in October 2023. Opinion polls indicate a very tight race between Prime Minister Benjamin Netanyahu and former armed forces chief Gadi Eisenkot. The outcome could shape Israel's future policy in the region, so the market will closely monitor the exit polls this evening.
—
Michał Jóźwiak, Financial Markets Analyst at XTB



📈Daily Summary: Falling Oil Prices and Anthropic Prospectus Drive Markets



US OPEN: Anthropic filing and Iran talks support the market
Anthropic files prospectus ahead of IPO with "ANT" ticker on Nasdaq. The launch date and price remain a mystery

Chart of the day: European gas ever closer to 100 EURMWh
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.