


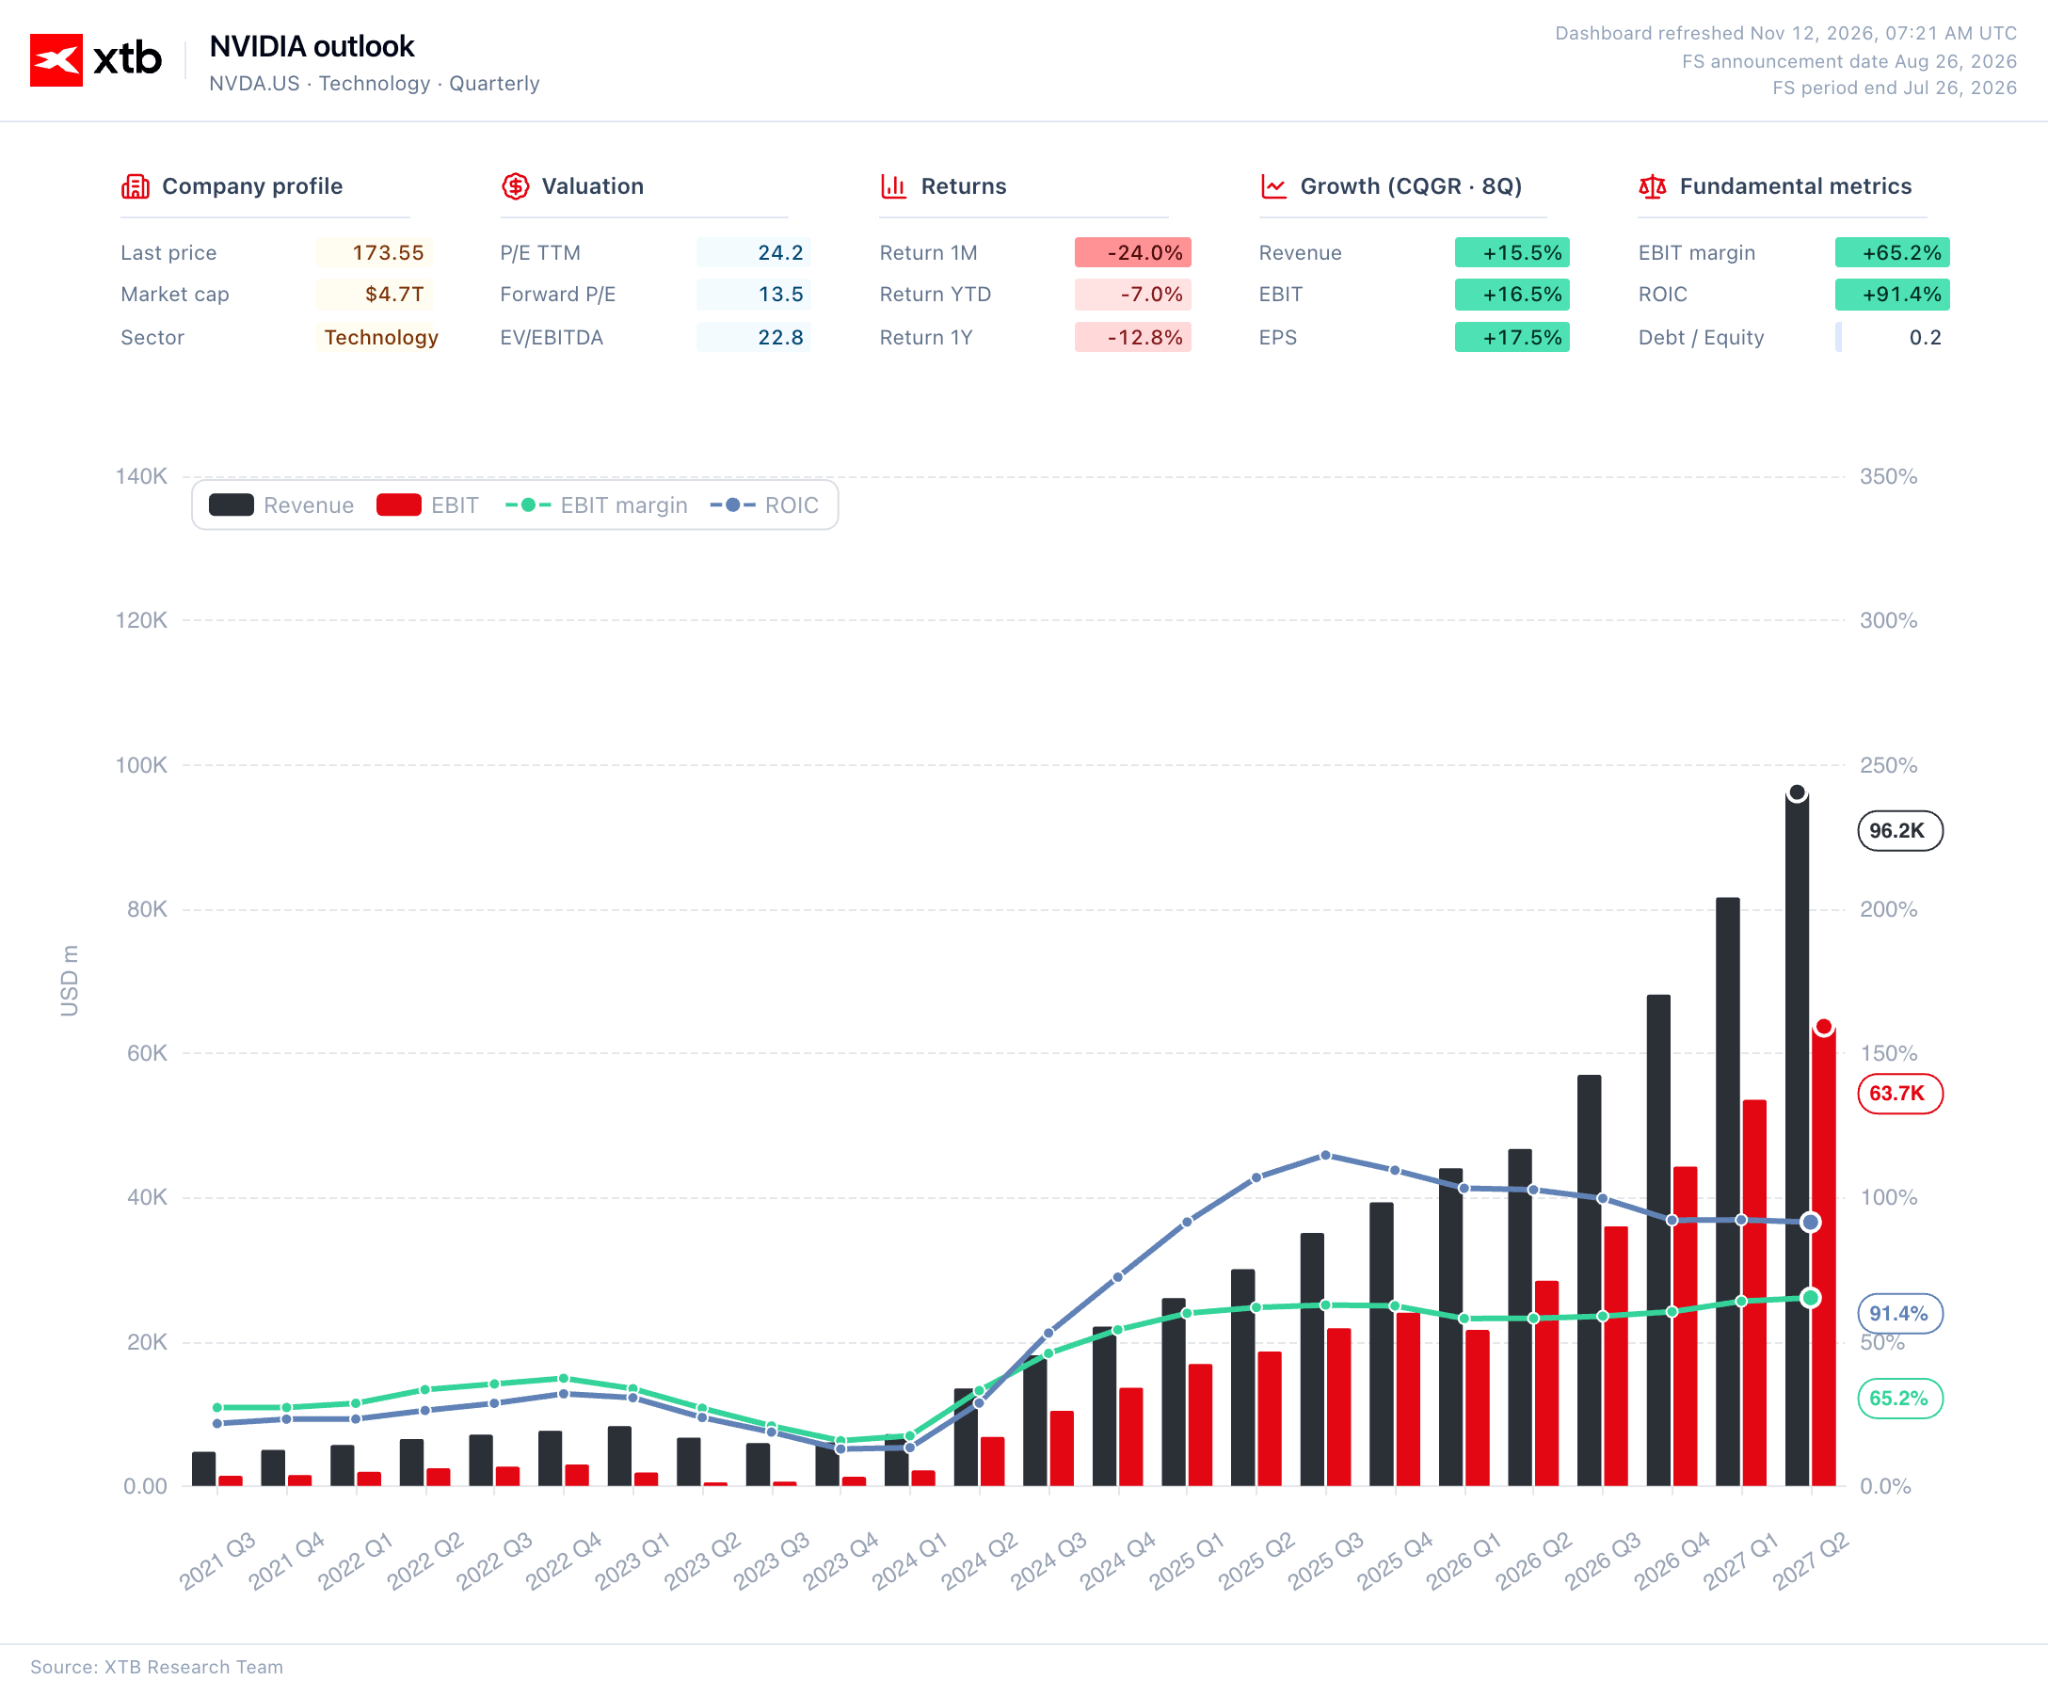
Market sentiment is sharply negative this morning. In pre-market trading, the Nasdaq 100 is down by around 1%, while the S&P 500 has fallen 0.5%. Indices are being dragged down primarily by a further decline in Nvidia shares (-7.5%), which account for over 10% of the key tech benchmark (and roughly 5% of the S&P 500). The sell-off is being driven by reports that the company's board is preparing to remove Jensen Huang from his role as chief executive.
Figure 1: Dashboard for Nvidia (2021 - 2026)
 Source: XTB Research, 12.11.2026
Uncertainty surrounding the AI-driven bull market, in which Nvidia plays a central role, is being compounded by concerns over potentially stricter regulations on data centre construction after Democrats secured control of both Houses of Congress.
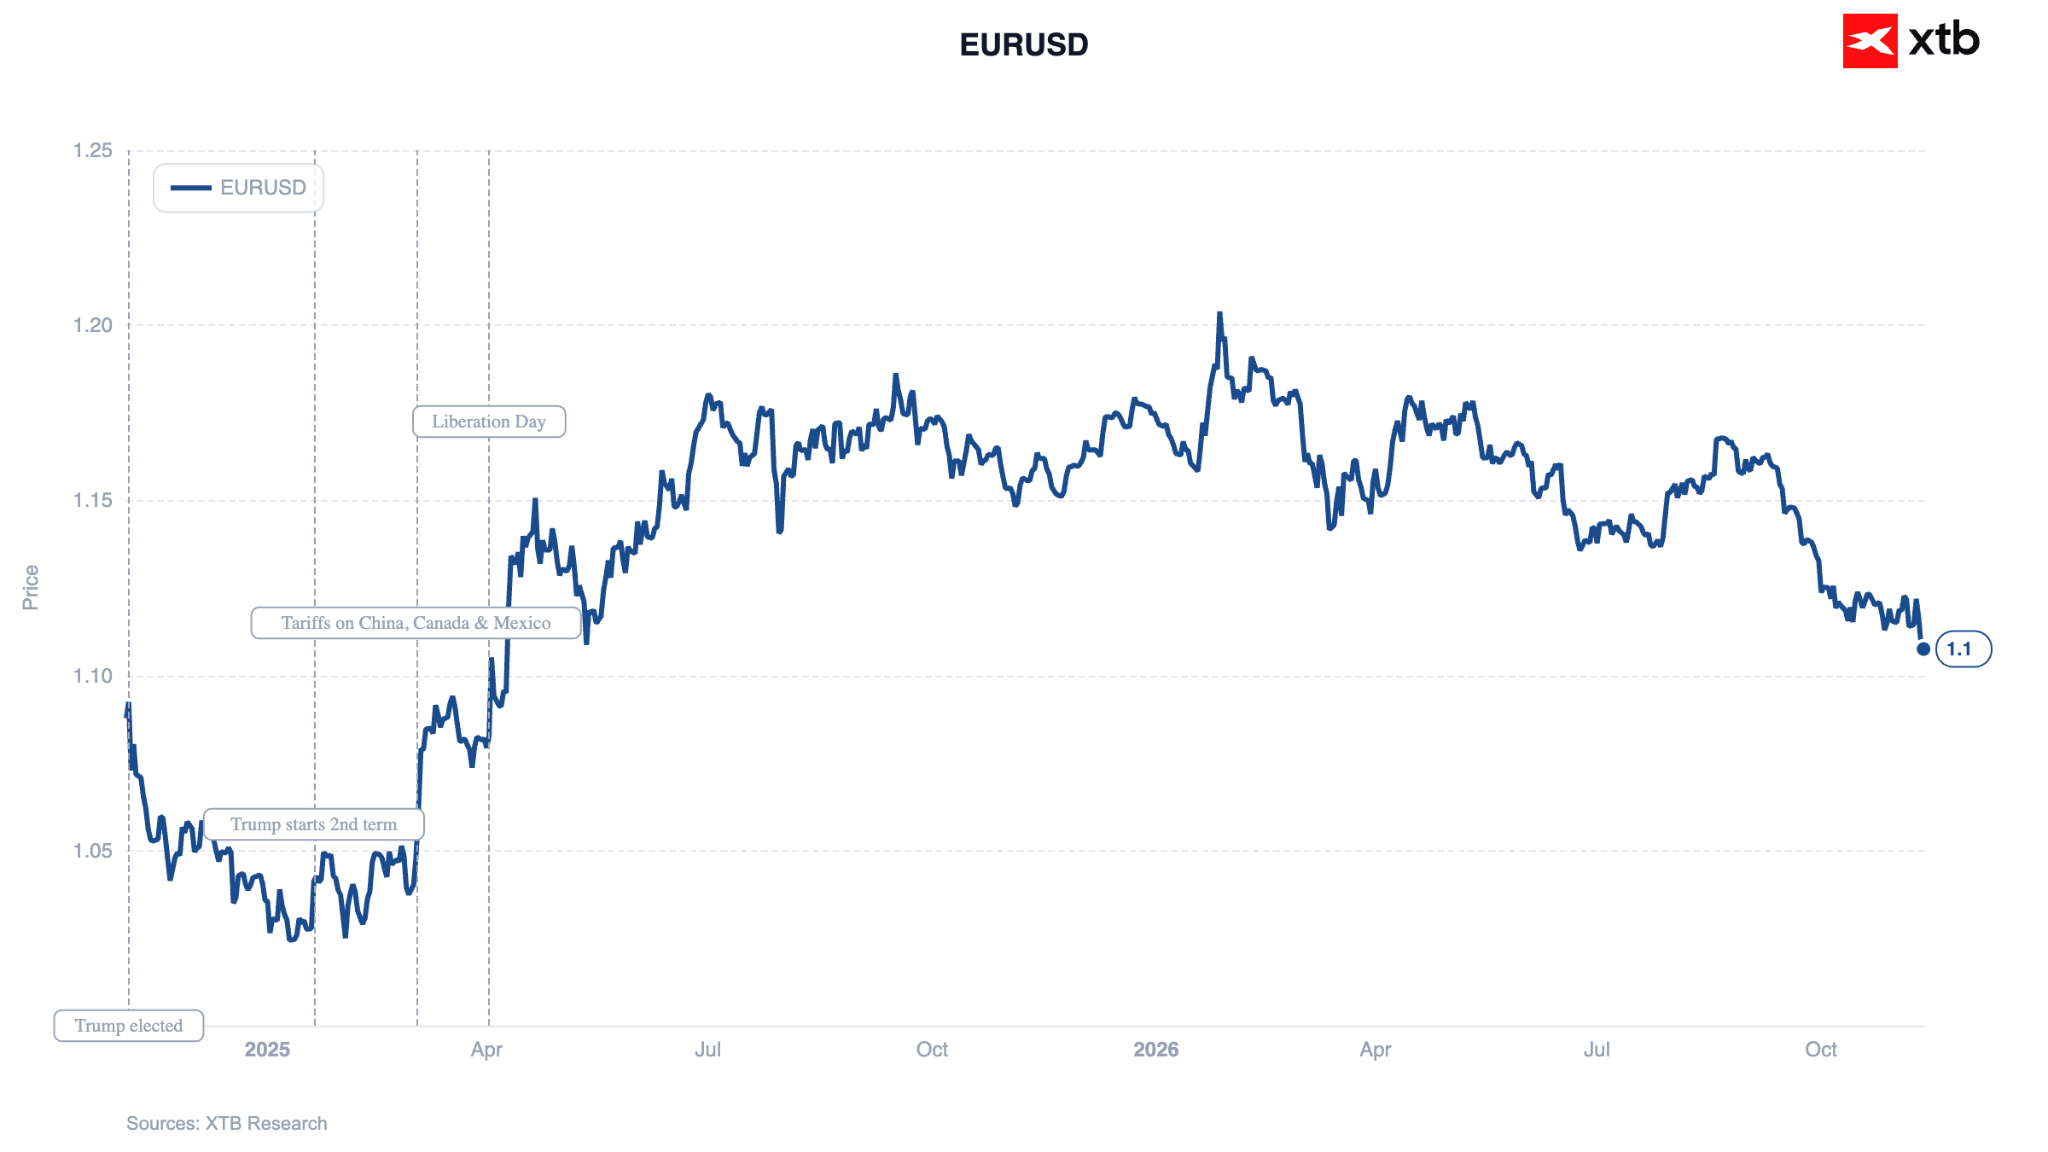
Beyond AI-related developments, the strength of the US dollar is drawing attention. EURUSD has broken below the 1.11 level since midnight, touching its lowest level since May 2025.
Figure 2: EURUSD (2024 - 2026)
 Source: XTB Research, 12.11.2026
📈 Equities
As mentioned earlier, Nvidia's board is considering removing Huang. The company is reportedly working with an executive search firm to identify a successor and is contemplating appointing an interim CEO while the search for a permanent replacement takes place.
The crisis erupted on Sunday when Huang admitted to an affair with Alice Huang, a woman suspected of acting on behalf of Chinese intelligence. Yesterday, further reports emerged of another affair involving the CEO, this time with Kimberly Powell, Vice President of Healthcare at Nvidia.
The stock closed yesterday at USD 173.73 and is currently trading approximately 7.5% lower in pre-market dealings. If post-market losses persist, the company's market capitalisation will fall below USD 4tn. Bernstein downgraded its recommendation to market perform from outperform, Baird cut its rating to neutral, and Morgan Stanley removed the stock from its top picks list.
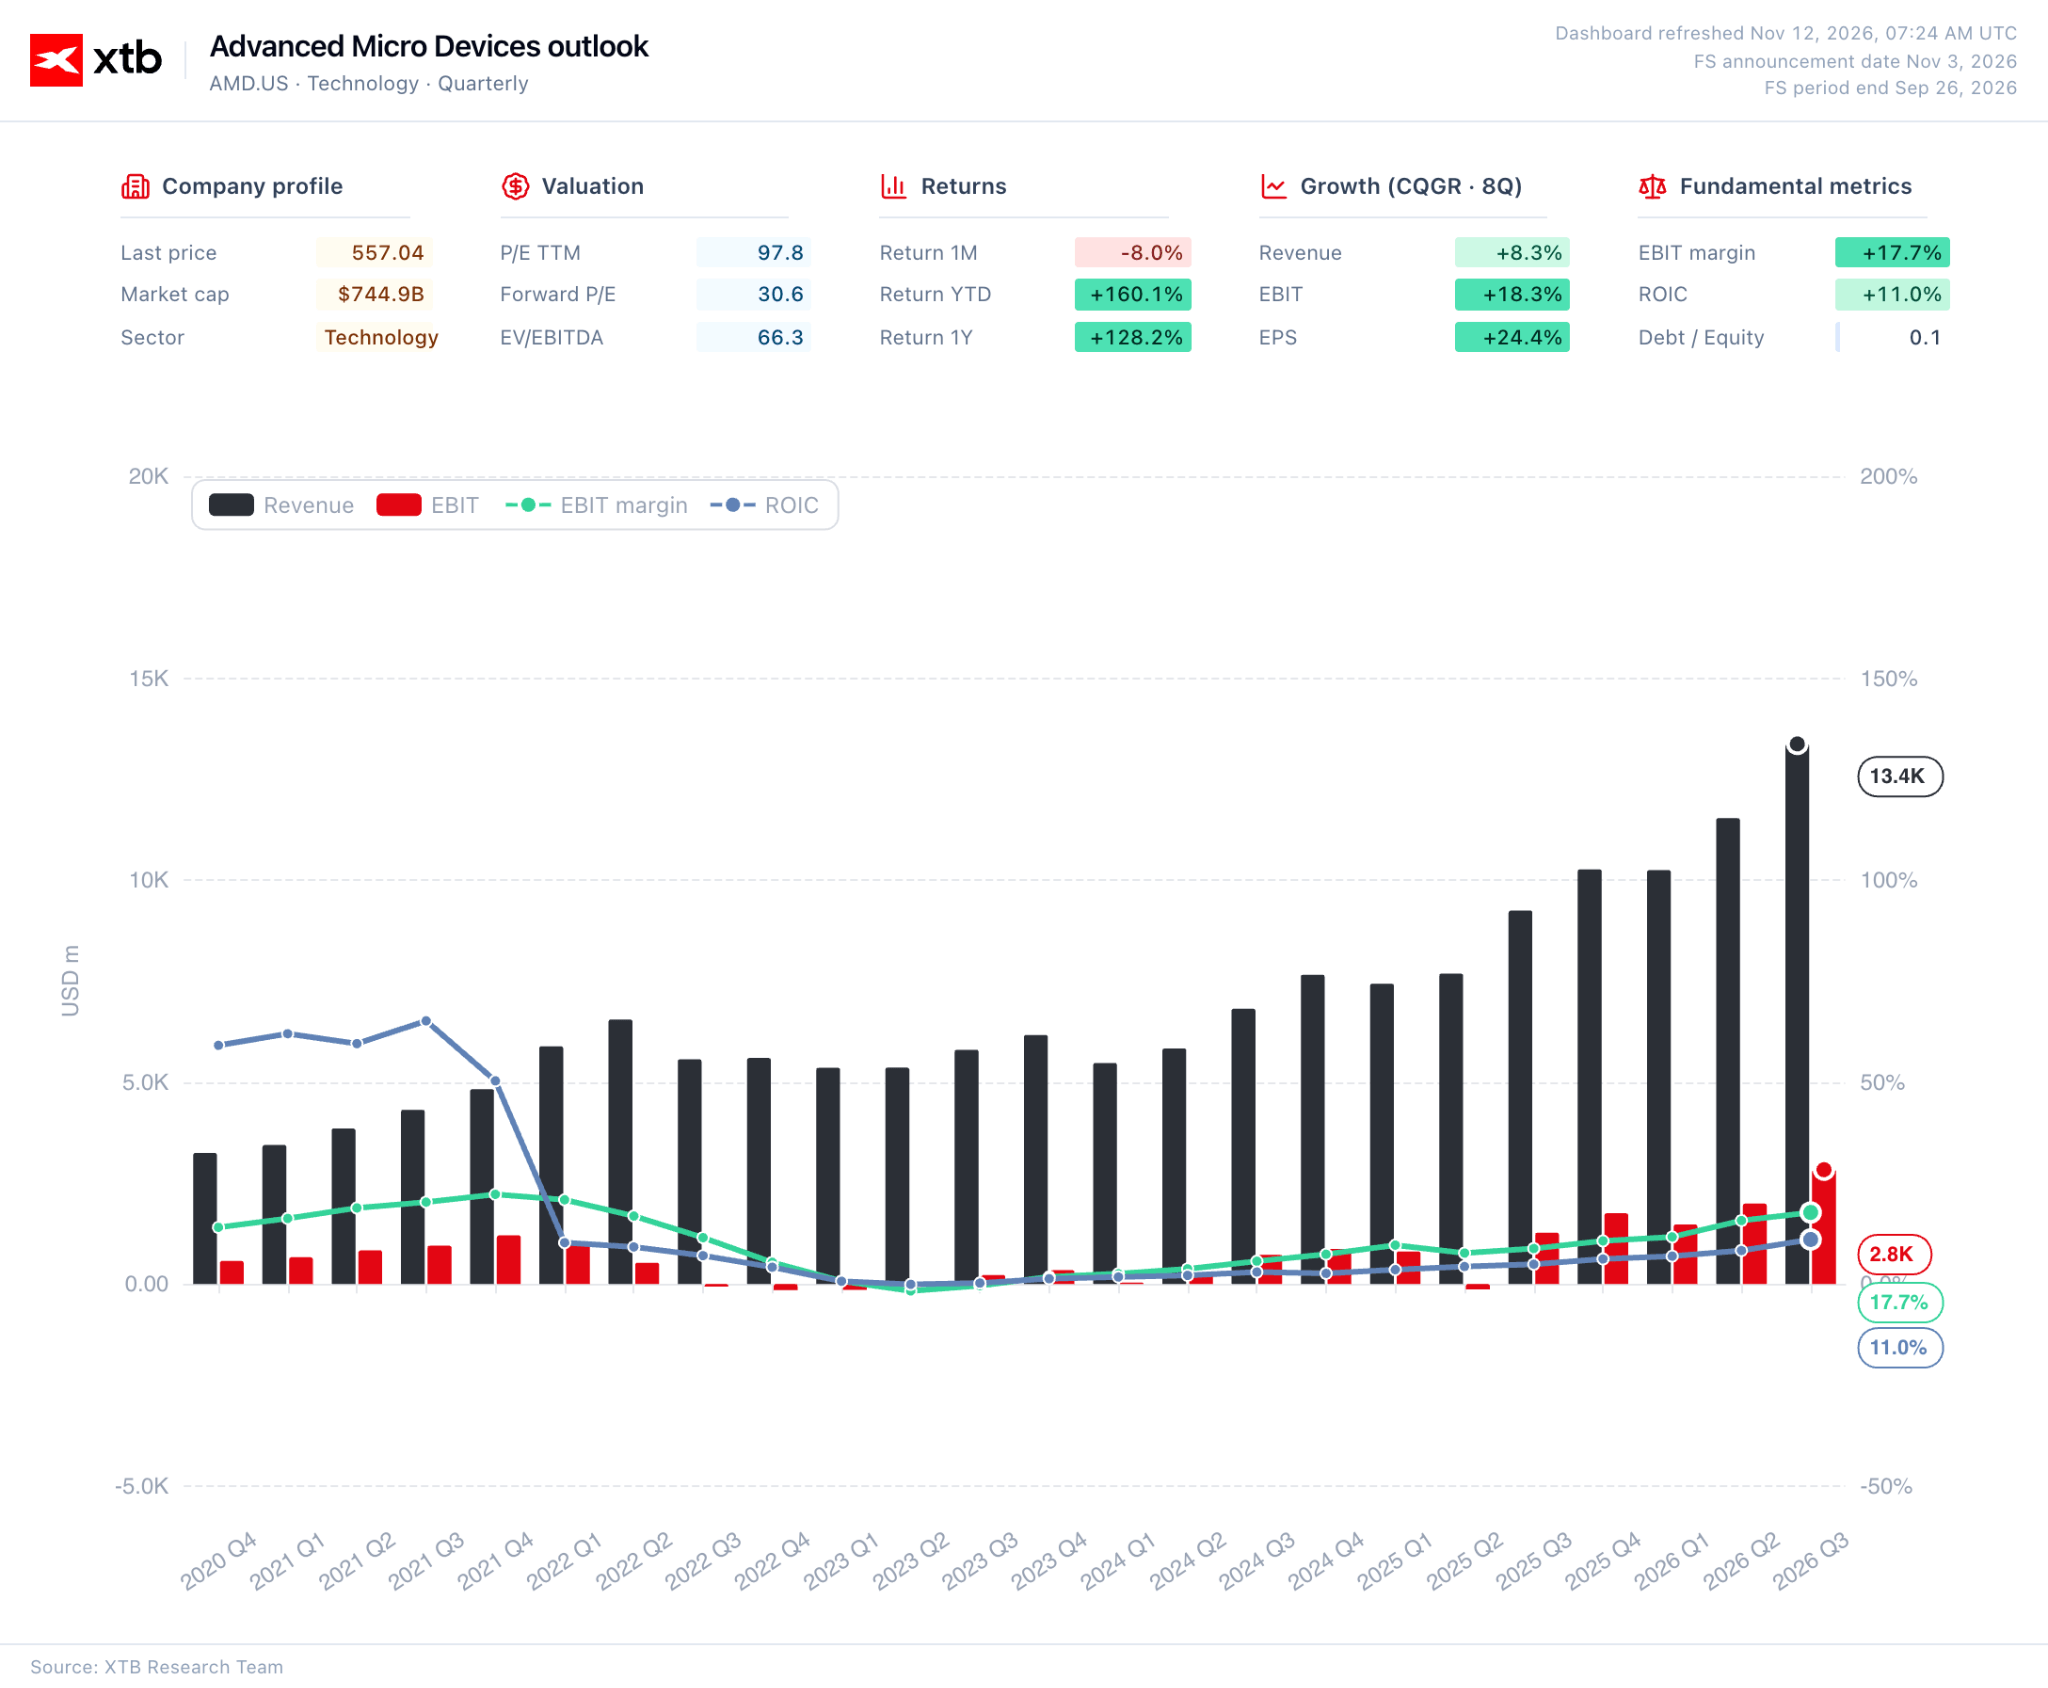
Competitors are capitalising on the crisis. AMD and Broadcom are up by 1-2% in post-market trading.
Figure 3: Dashboard for AMD (2021 - 2026)
 Source: XTB Research, 12.11.2026
The turmoil also carries political ramifications. The company could face government investigations over espionage concerns, alongside inquiries into how its chips reach China via Singapore.
Looking at the broader picture, the Nasdaq 100 is now 9% below its October peak. Its Forward P/E ratio has dropped to around 17x, moving below the level of the S&P 500 (approx. 18x).
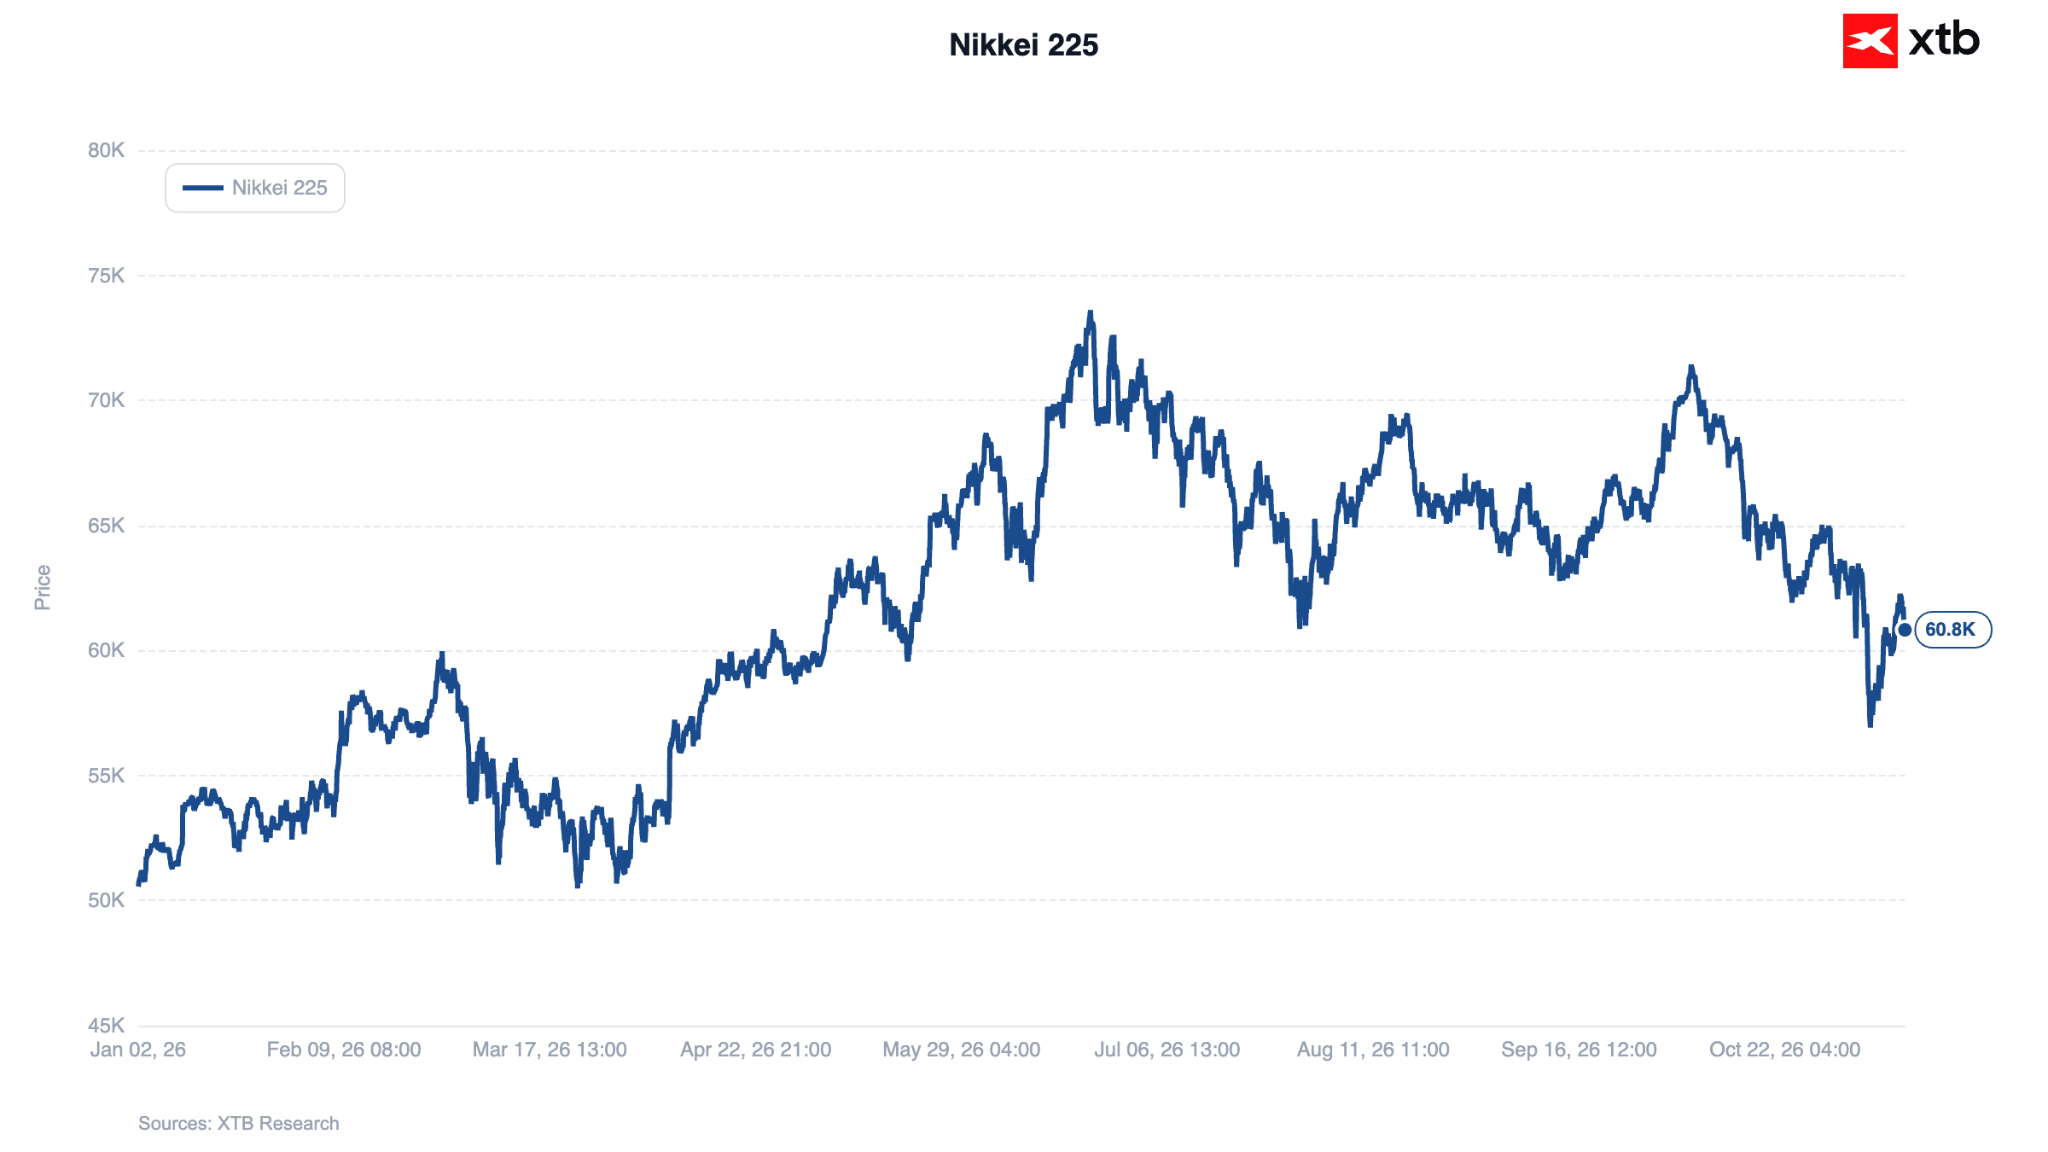
The scale of the sell-off in Asian markets remains contained, though far from negligible. The sharpest declines were recorded by the Hang Seng (-1.2%), the Kospi (-0.6%), and the Nikkei 225 (-0.7%).
Figure 4: Nikkei 225 (2026)
 Source: XTB Research, 12.11.2026
📈 Monetary policy and macroeconomic data
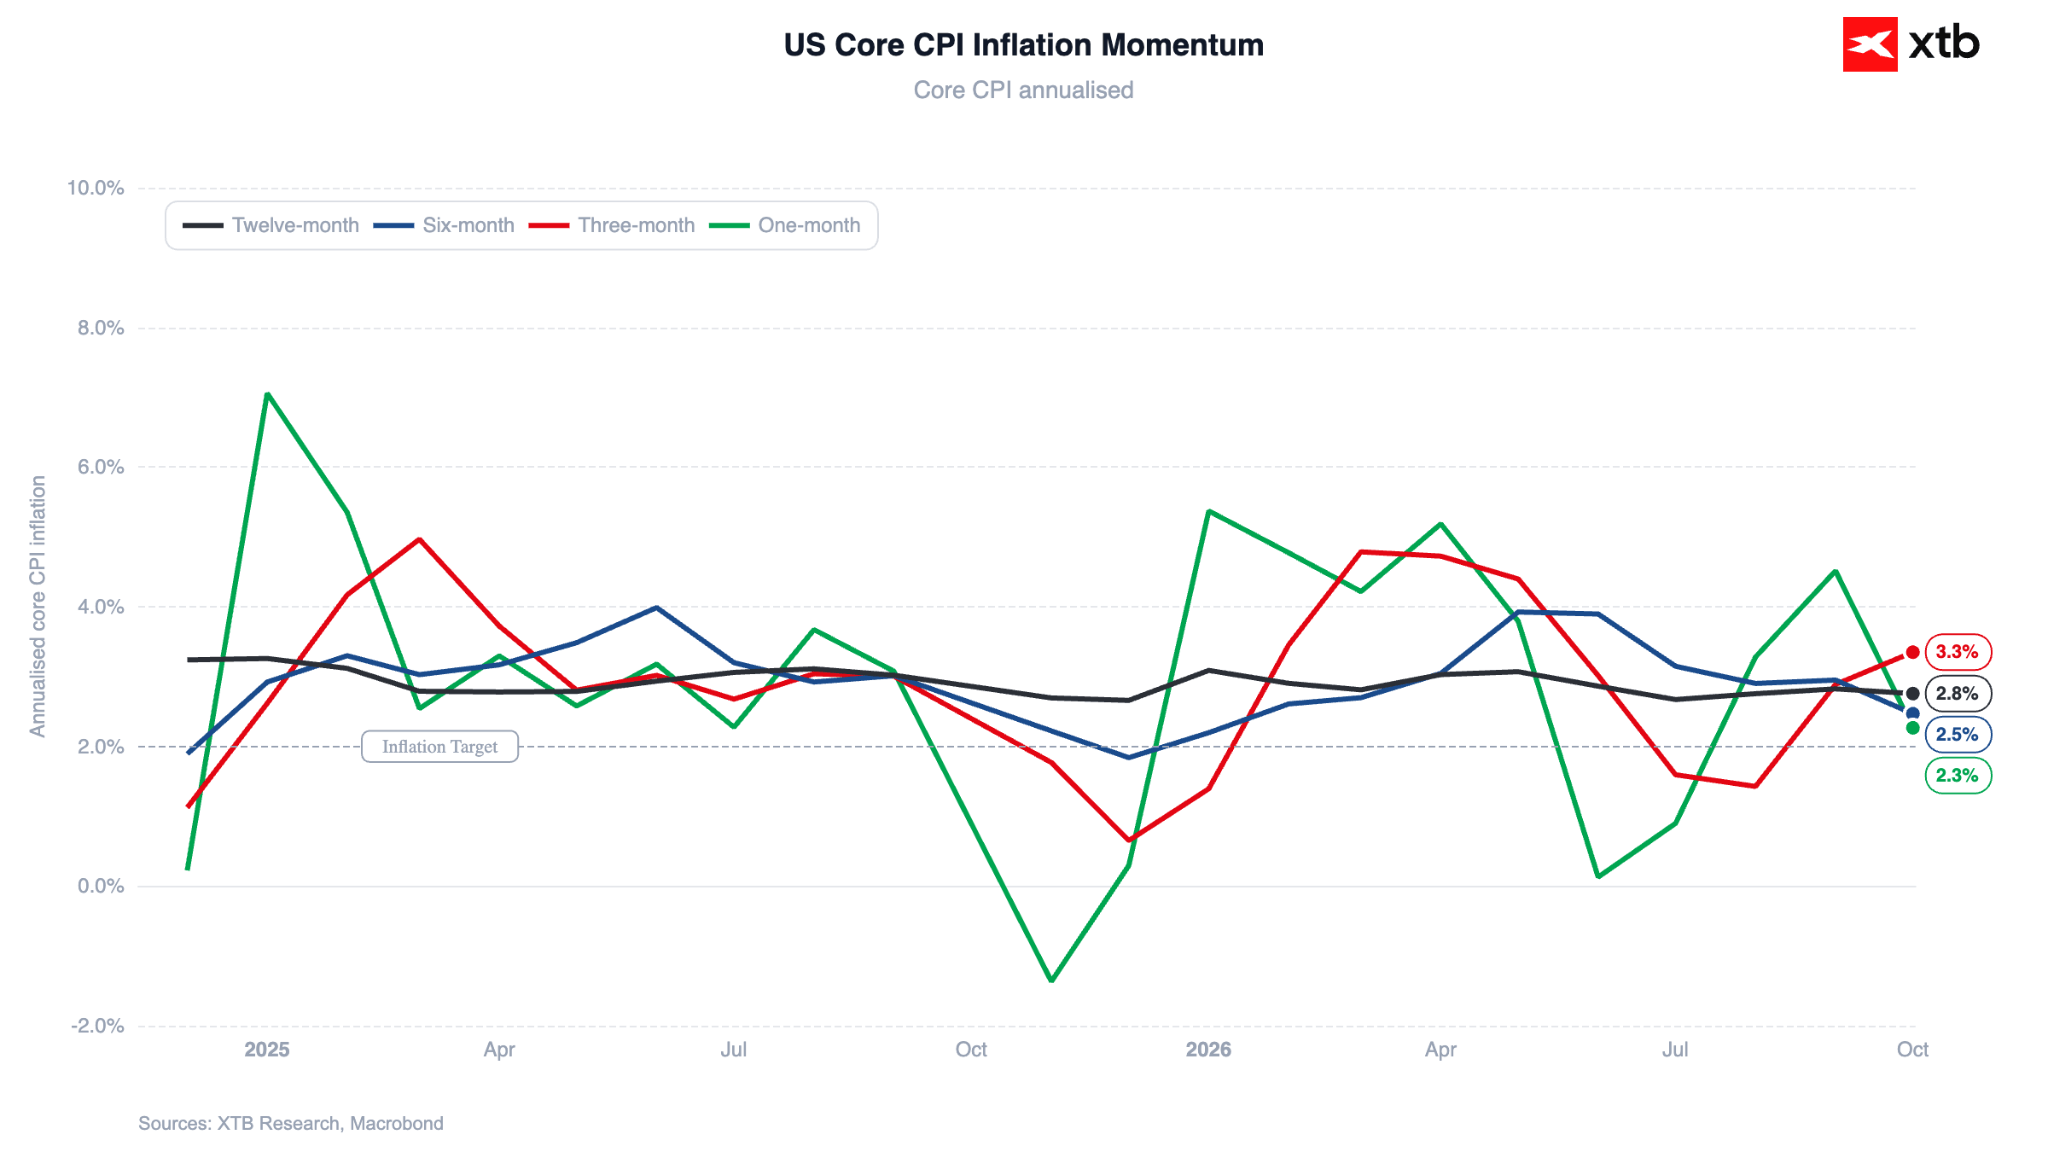
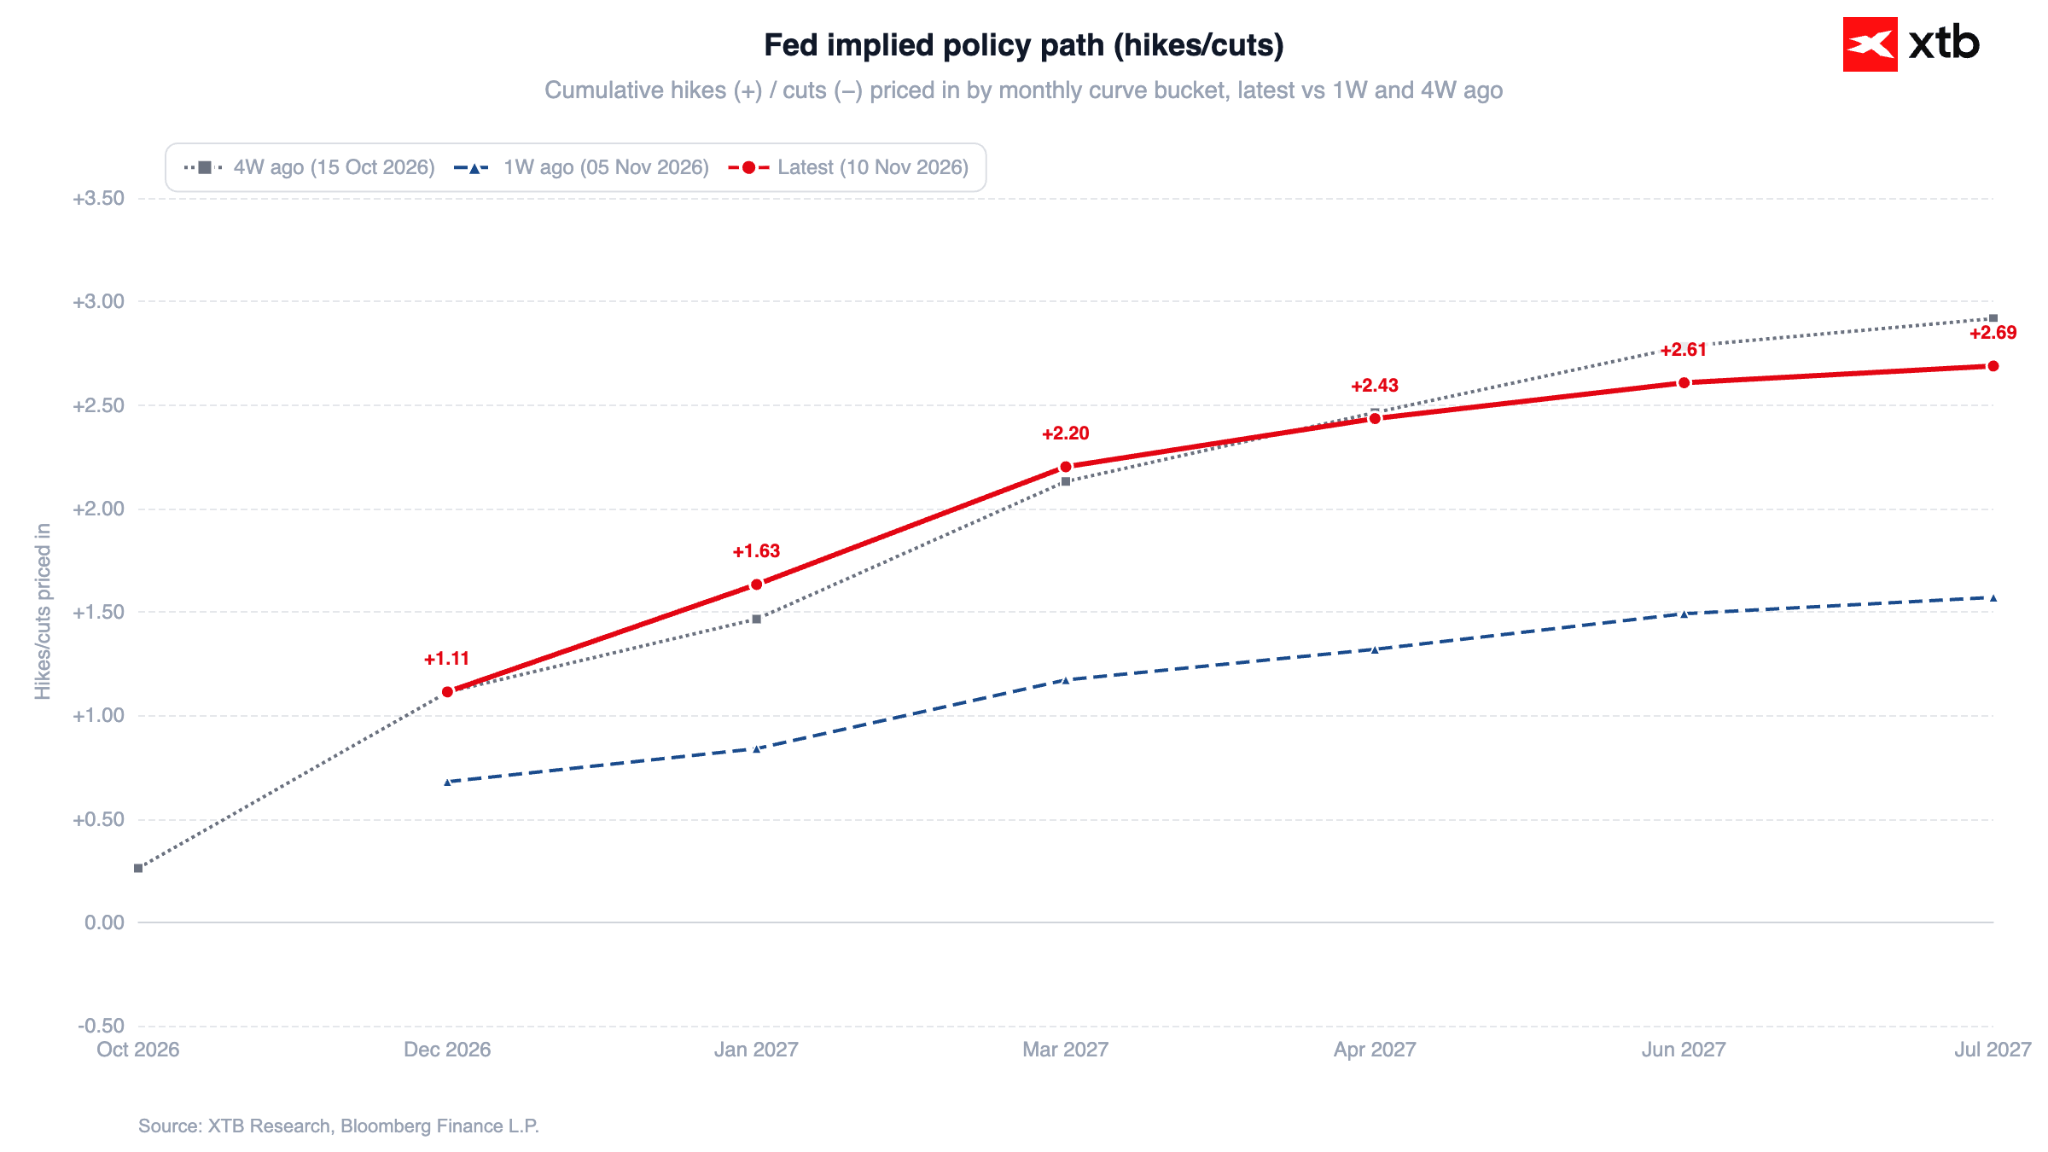
Expectations of interest rate hikes by the Federal Reserve are rising. Markets are once again fully pricing in a December rate increase, without ruling out a potential 50 bps move (though we view the latter as highly unlikely). As a reminder, October inflation figures came in significantly higher than expected, with headline CPI increasing by 0.4% m/m against a projected 0.3%, and core CPI rising 0.3% compared to the anticipated 0.2%.
Figure 5: Momentum of core CPI inflation in the US (2024 - 2026)
 Source: XTB Research, 12.11.2026
Christopher Waller expressed support for a 25 bps hike in December, but added that with core inflation at or above 0.3%, a 50 bps increase should be considered. Chicago Fed President Austan Goolsbee described the October reading as "borderline disturbing".
Figure 6: Market-implied rate path in the US (2026 - 2027)
 Source: XTB Research, 12.11.2026
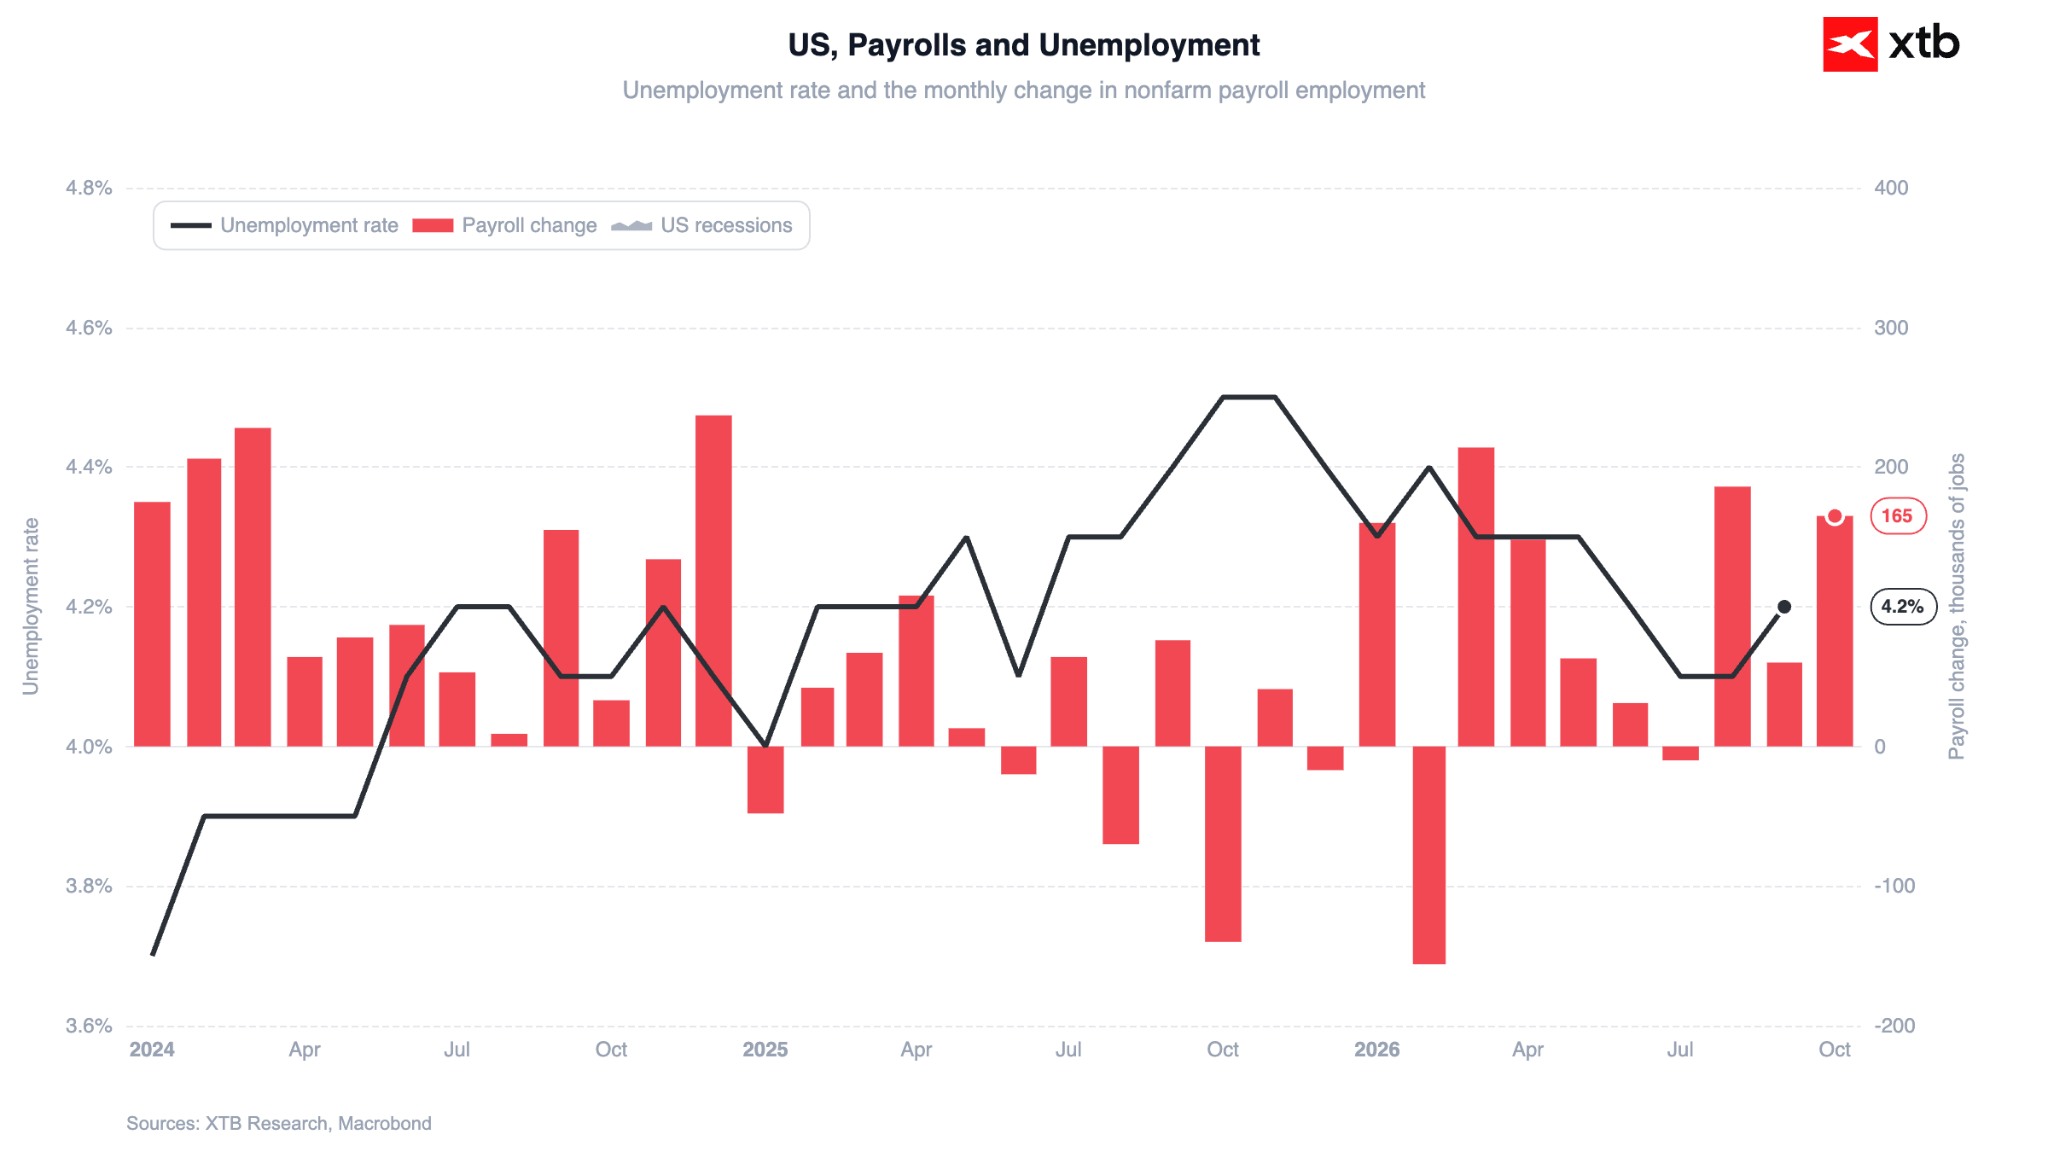
On the data front, third-quarter UK GDP growth figures have already been published. The data broadly aligned with expectations, showing an impressive 0.7% expansion quarter-on-quarter. Looking ahead, weekly US jobless claims are scheduled for release at 14:30; however, their impact is likely to be muted following last week's NFP release.
Figure 7: NFP and unemployment rate in the US (2024 - 2026)
 Source: XTB Research, 12.11.2026
🛢️ Energy commodities
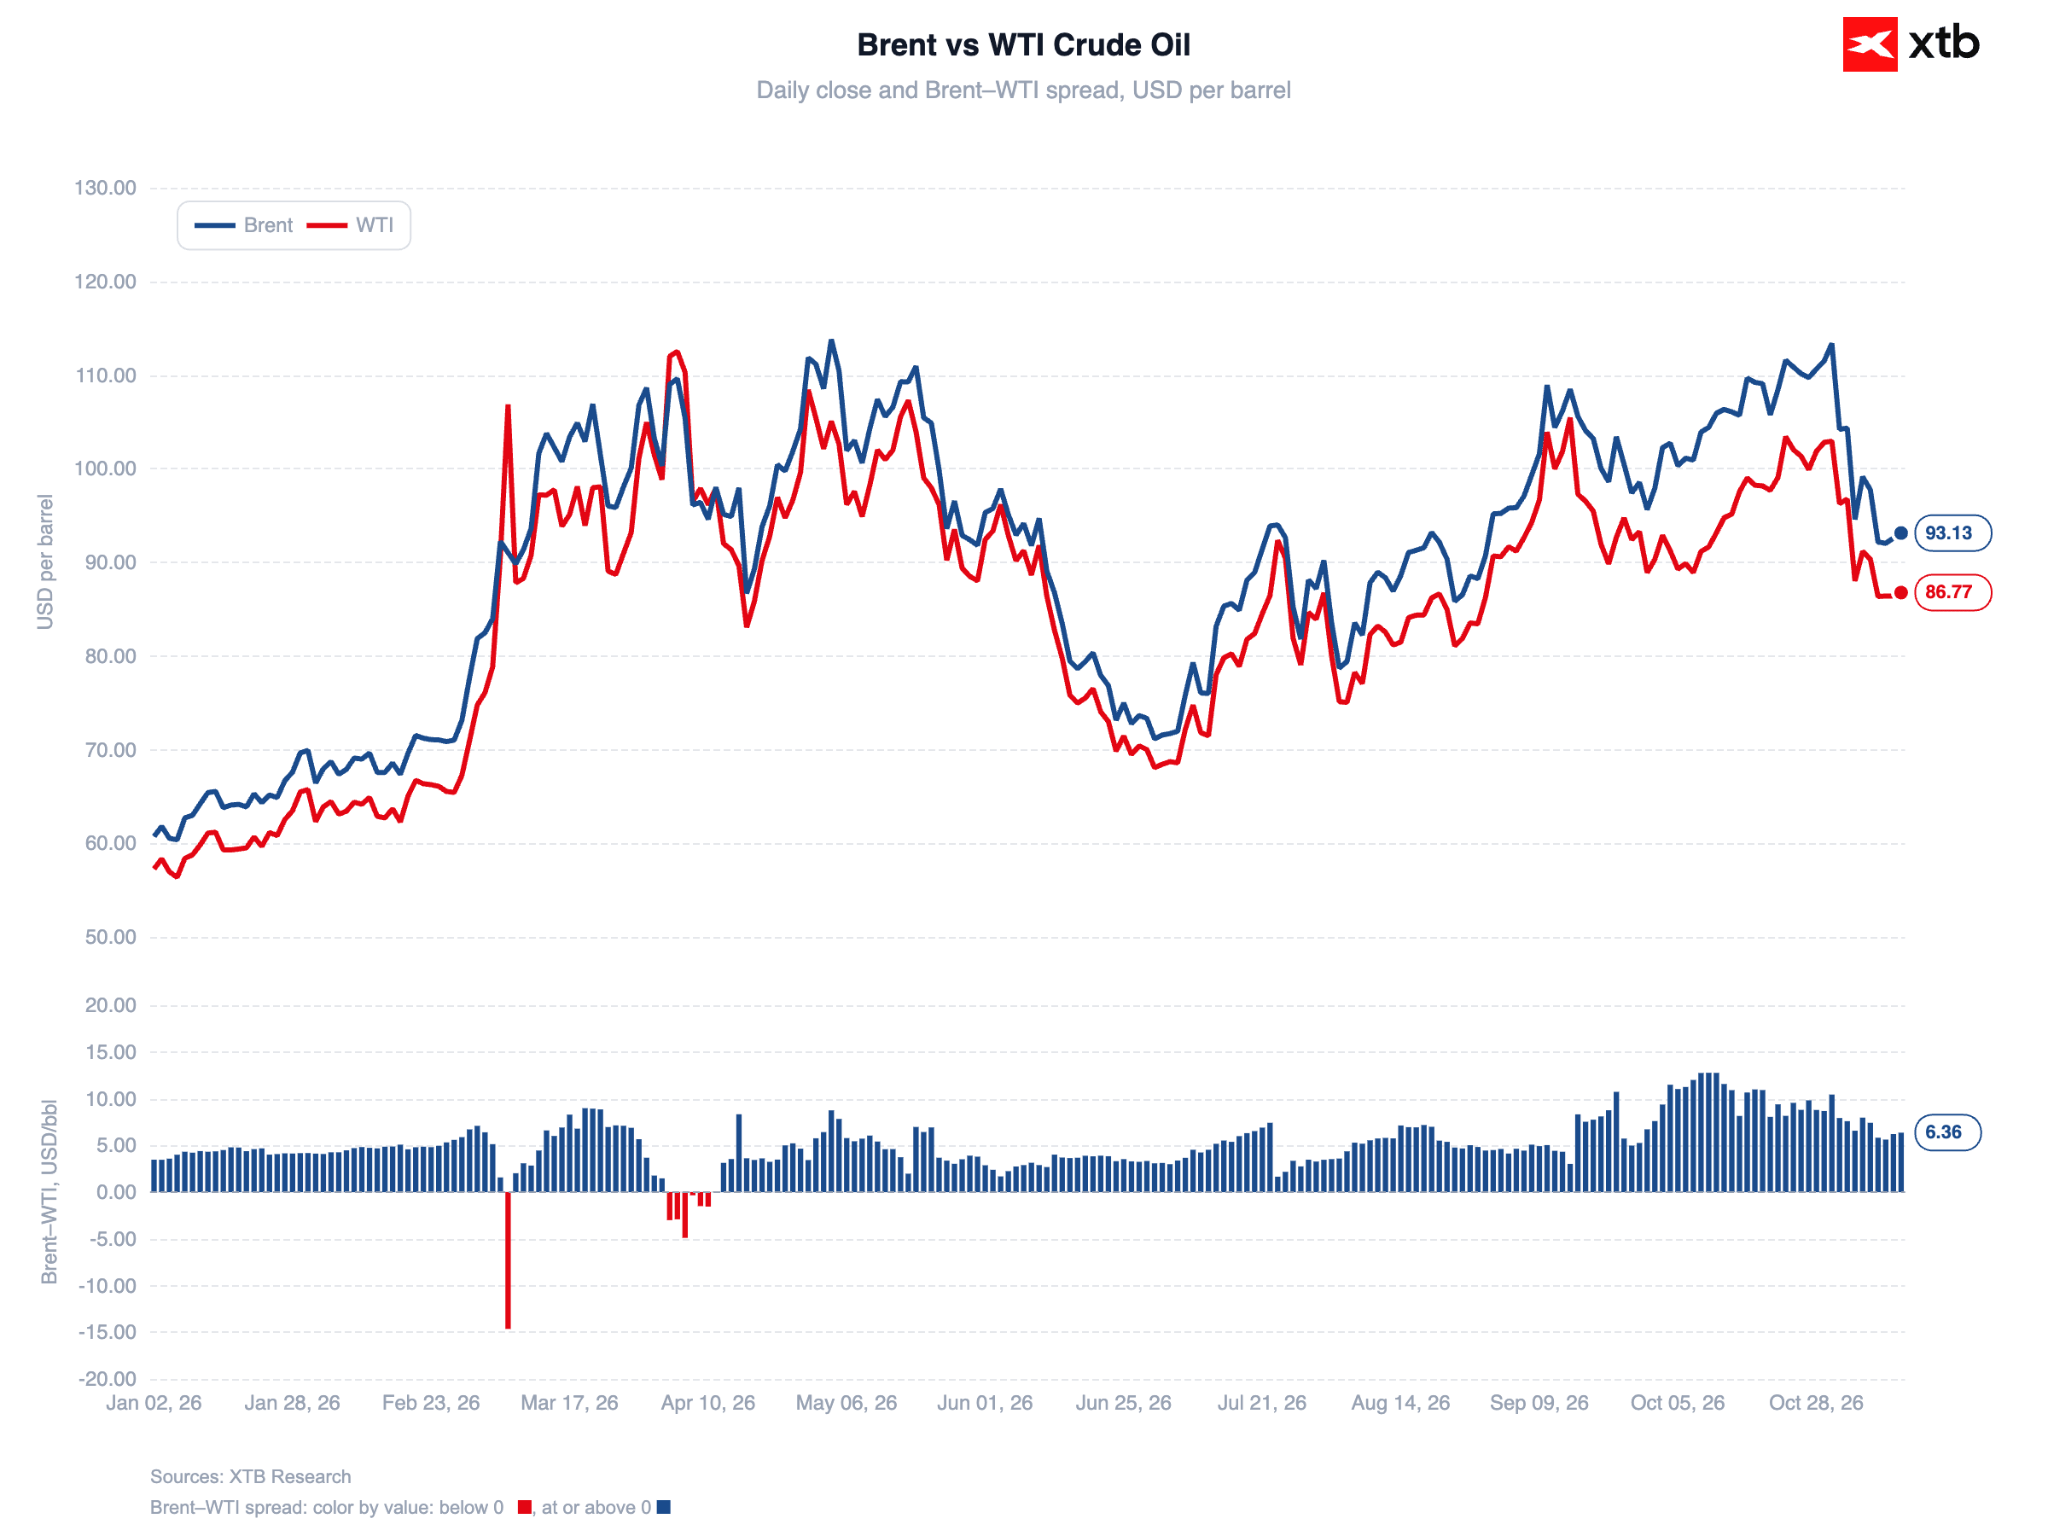
Brent crude, having dipped near a two-month low (USD 91.6 per barrel), is rebounding slightly to USD 93. WTI is also moving higher to USD 86.8.
Figure 8: Brent and WTI crude oil (2026)
 Source: XTB Research, 12.11.2026
🪙 Precious metals
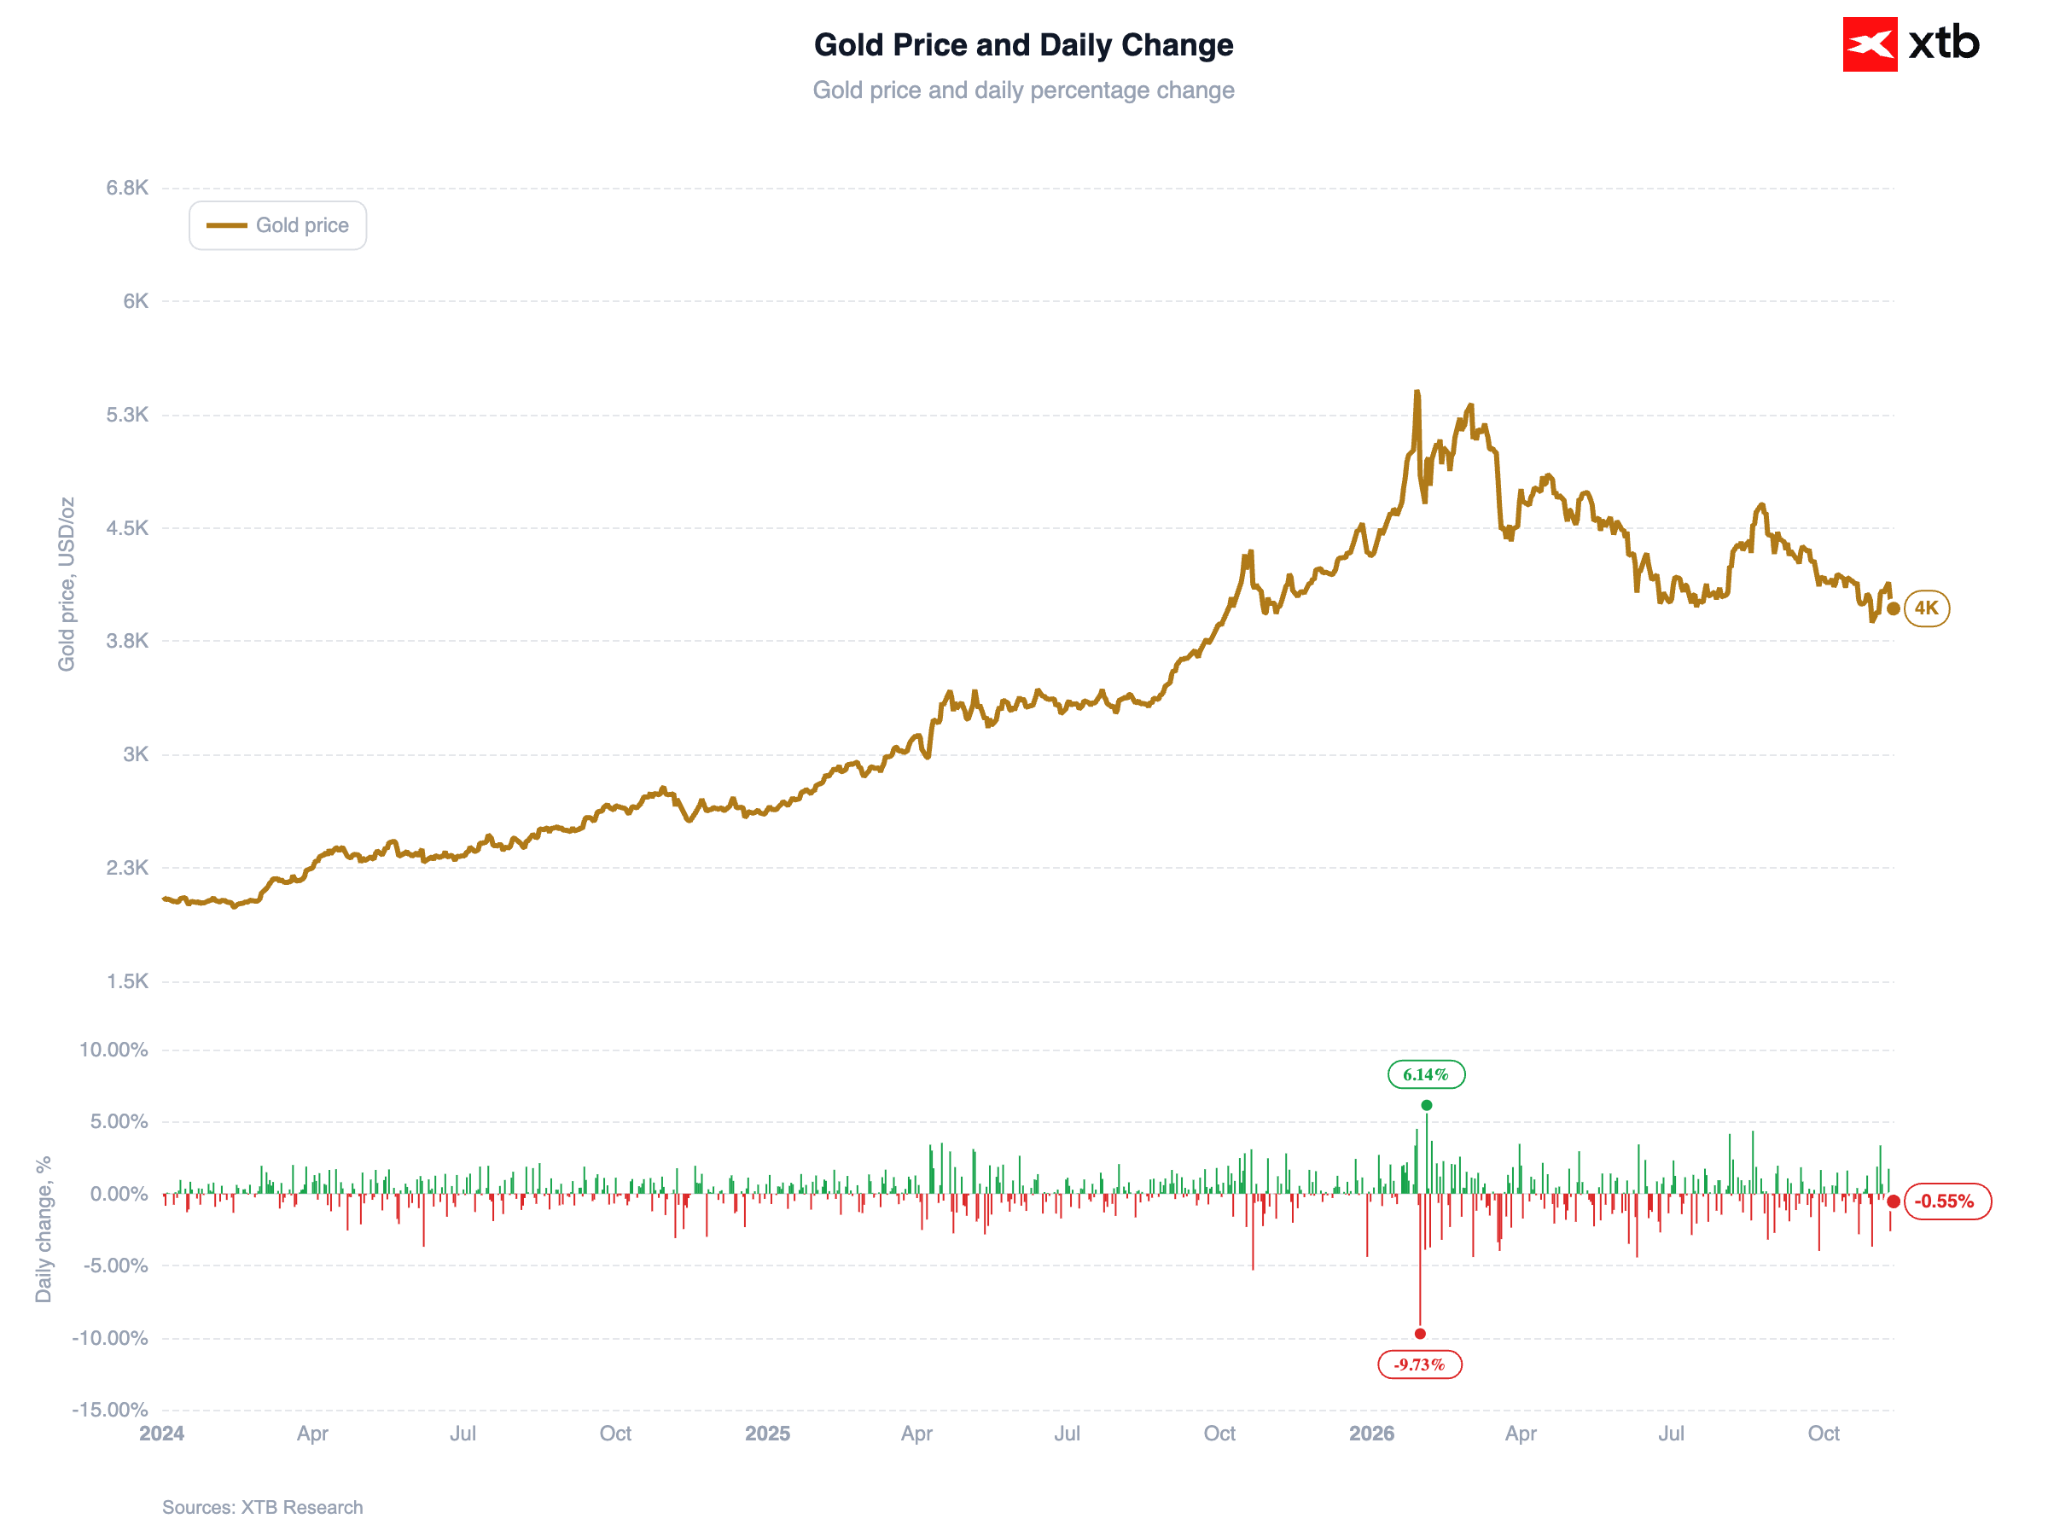
Gold is declining for a third consecutive session, trading around USD 3,960 per ounce - below the key psychological barrier of USD 4,000. The precious metal is under pressure from a stronger US dollar and heightened expectations of Fed rate increases. An upside surprise in Friday's US PPI release could deepen the pull-back.
Figure 9: Gold (2024 - 2026)
 Source: XTB Research, 12.11.2026
💱 Currencies
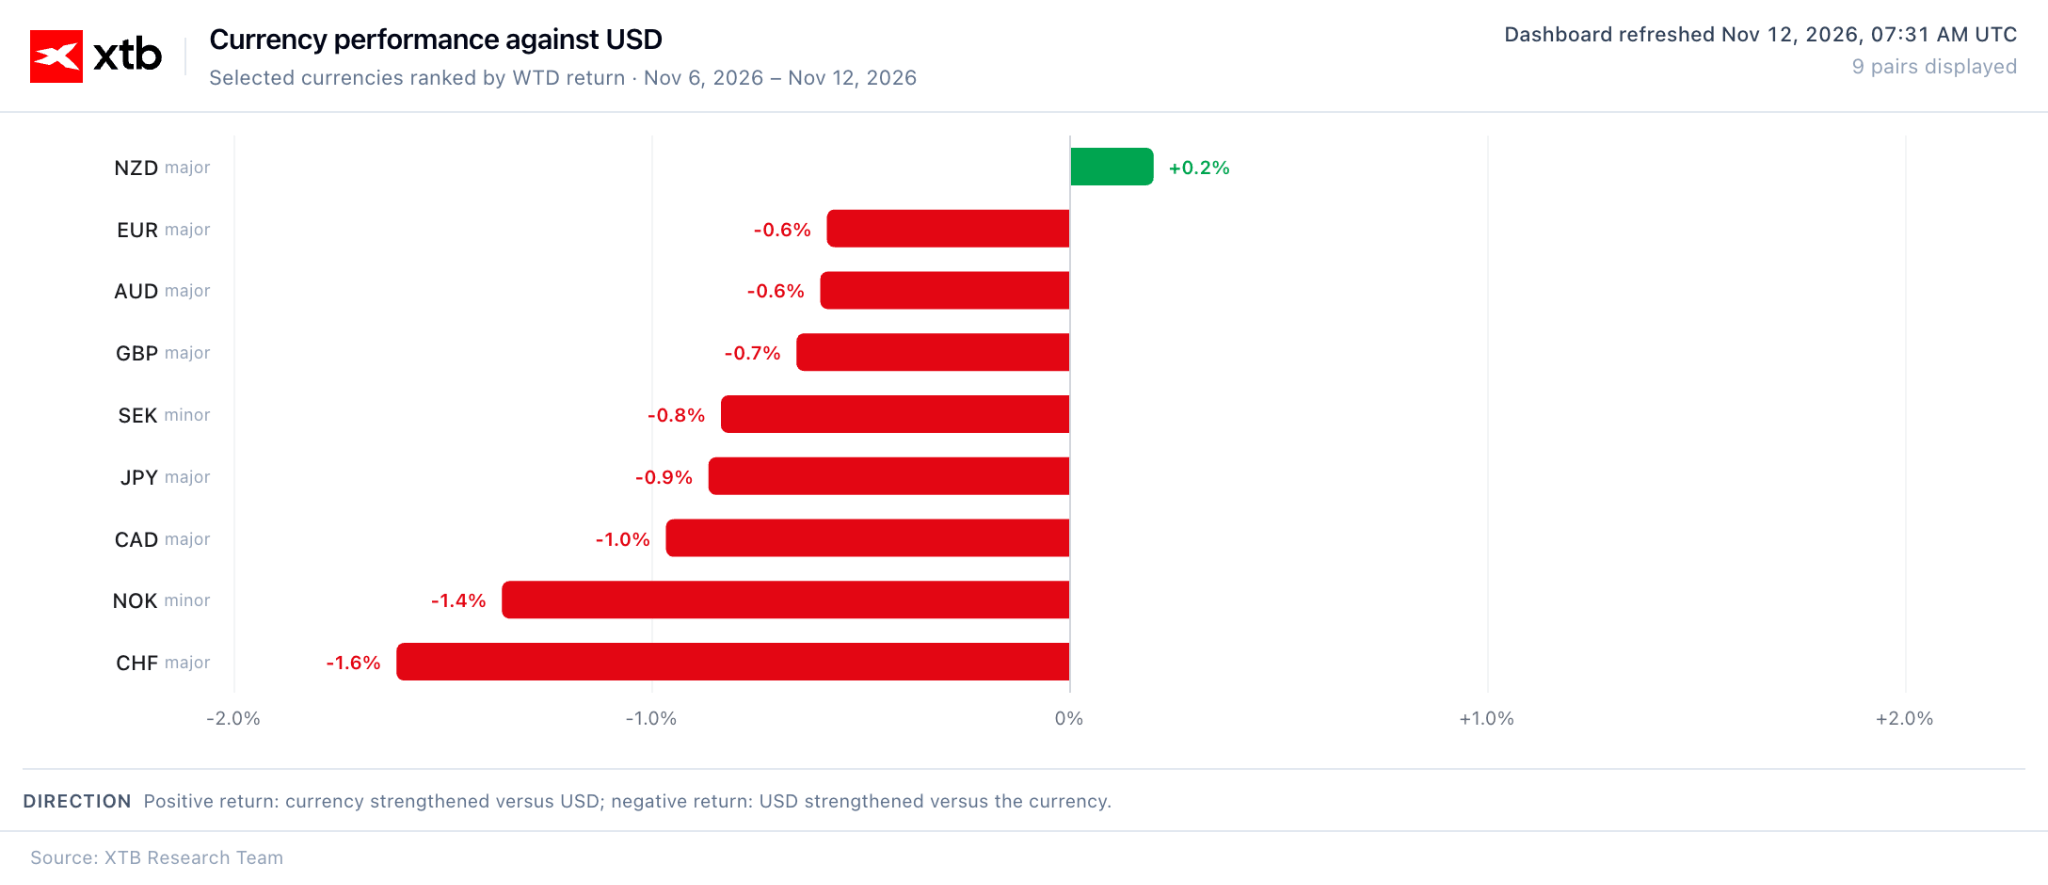
EURUSD fell to its lowest level since May 2025 (1.107). The dollar is benefiting from growing expectations of Fed rate hikes. The euro is weighed down by concerns over French public finances and an increasing consensus that the ECB will be disinclined to tighten monetary policy further after December.
Figure 10: G10 currencies dashboard [vs. USD] (06.11.2026 - 12.11.2026)
 Source: XTB Research, 12.11.2026
USDJPY is also attracting attention as it approaches the 160 level, a threshold that has triggered intervention by the BoJ in recent months.
—
Michał Jóźwiak, Financial Markets Analyst at XTB



📊Daily Summary: Tech sector drives Wall Street rebound, DAX leads in Europe


Nvidia shares suffer their biggest drop since 2025 🚩 What’s next for the AI giant?


Daily summary: CPI reading hits markets, hawkish Fed and Wall Street selloff
US OPEN: Higher CPI Inflation Cools Sentiment, Anthropic Targets $1.4 Trillion Valuation
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.