


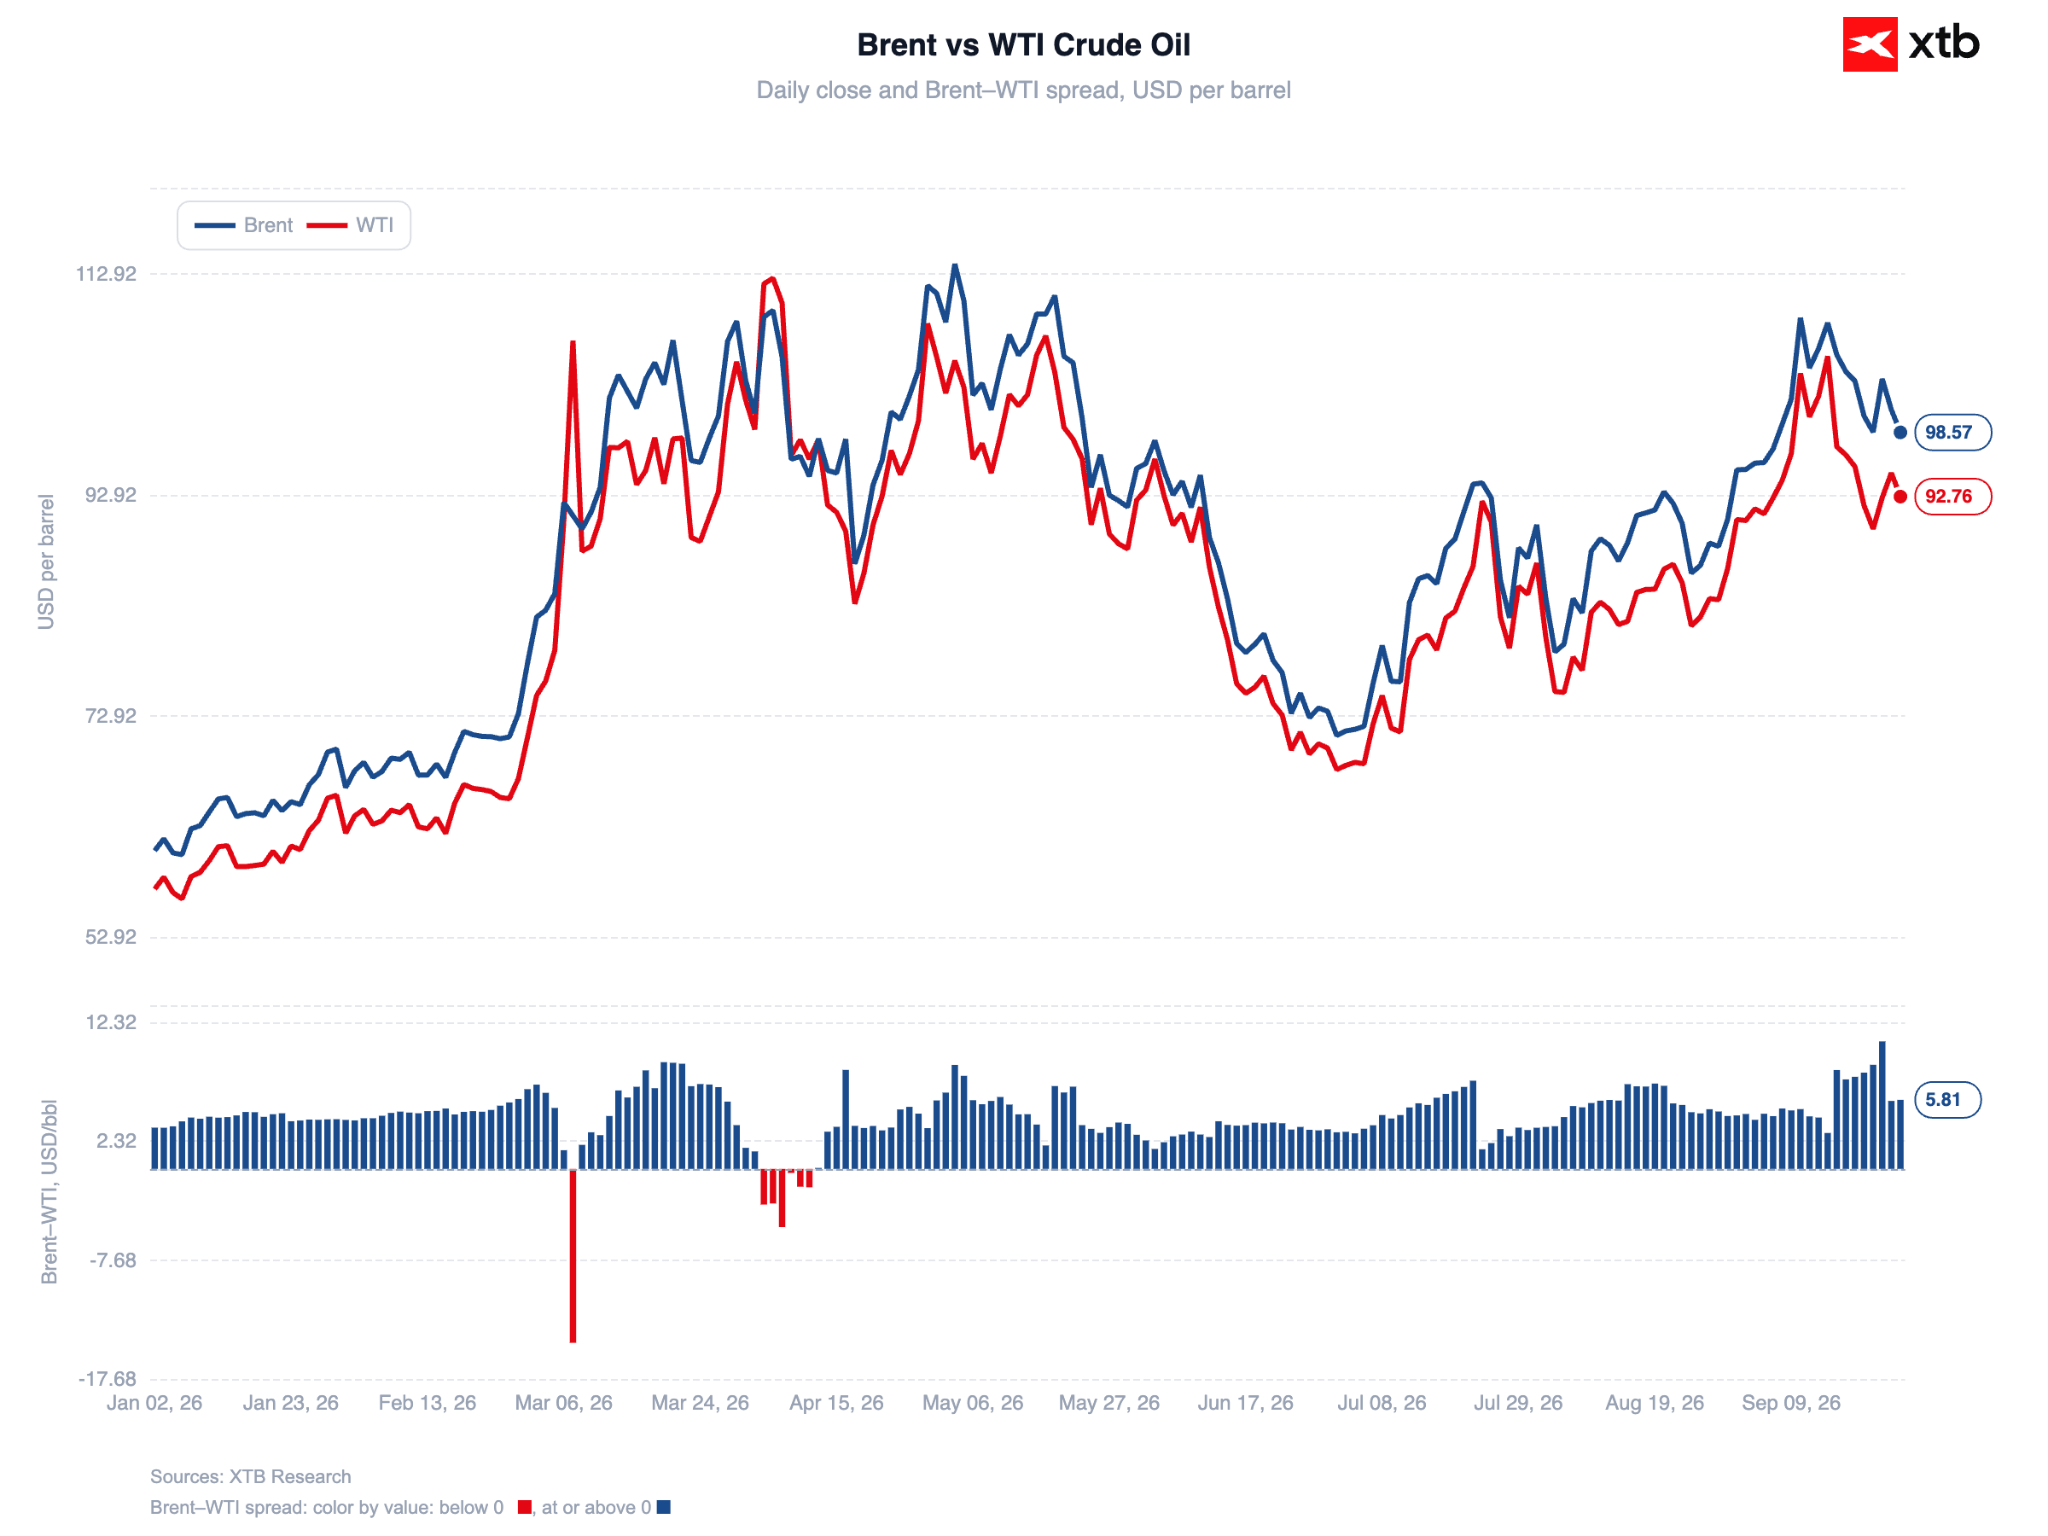
Following two sessions of strong gains, we are observing a correction in the oil market. Prices have declined from yesterday's local peak, with Brent crude currently trading slightly above $98 per barrel. Oil prices dropped relative to yesterday's local high of $102 per barrel, aided by reports of modest progress in negotiations between the US and Iran.
Figure 1: Brent and WTI Crude Oil (2026)
 Source: XTB Research, 25.09.2026
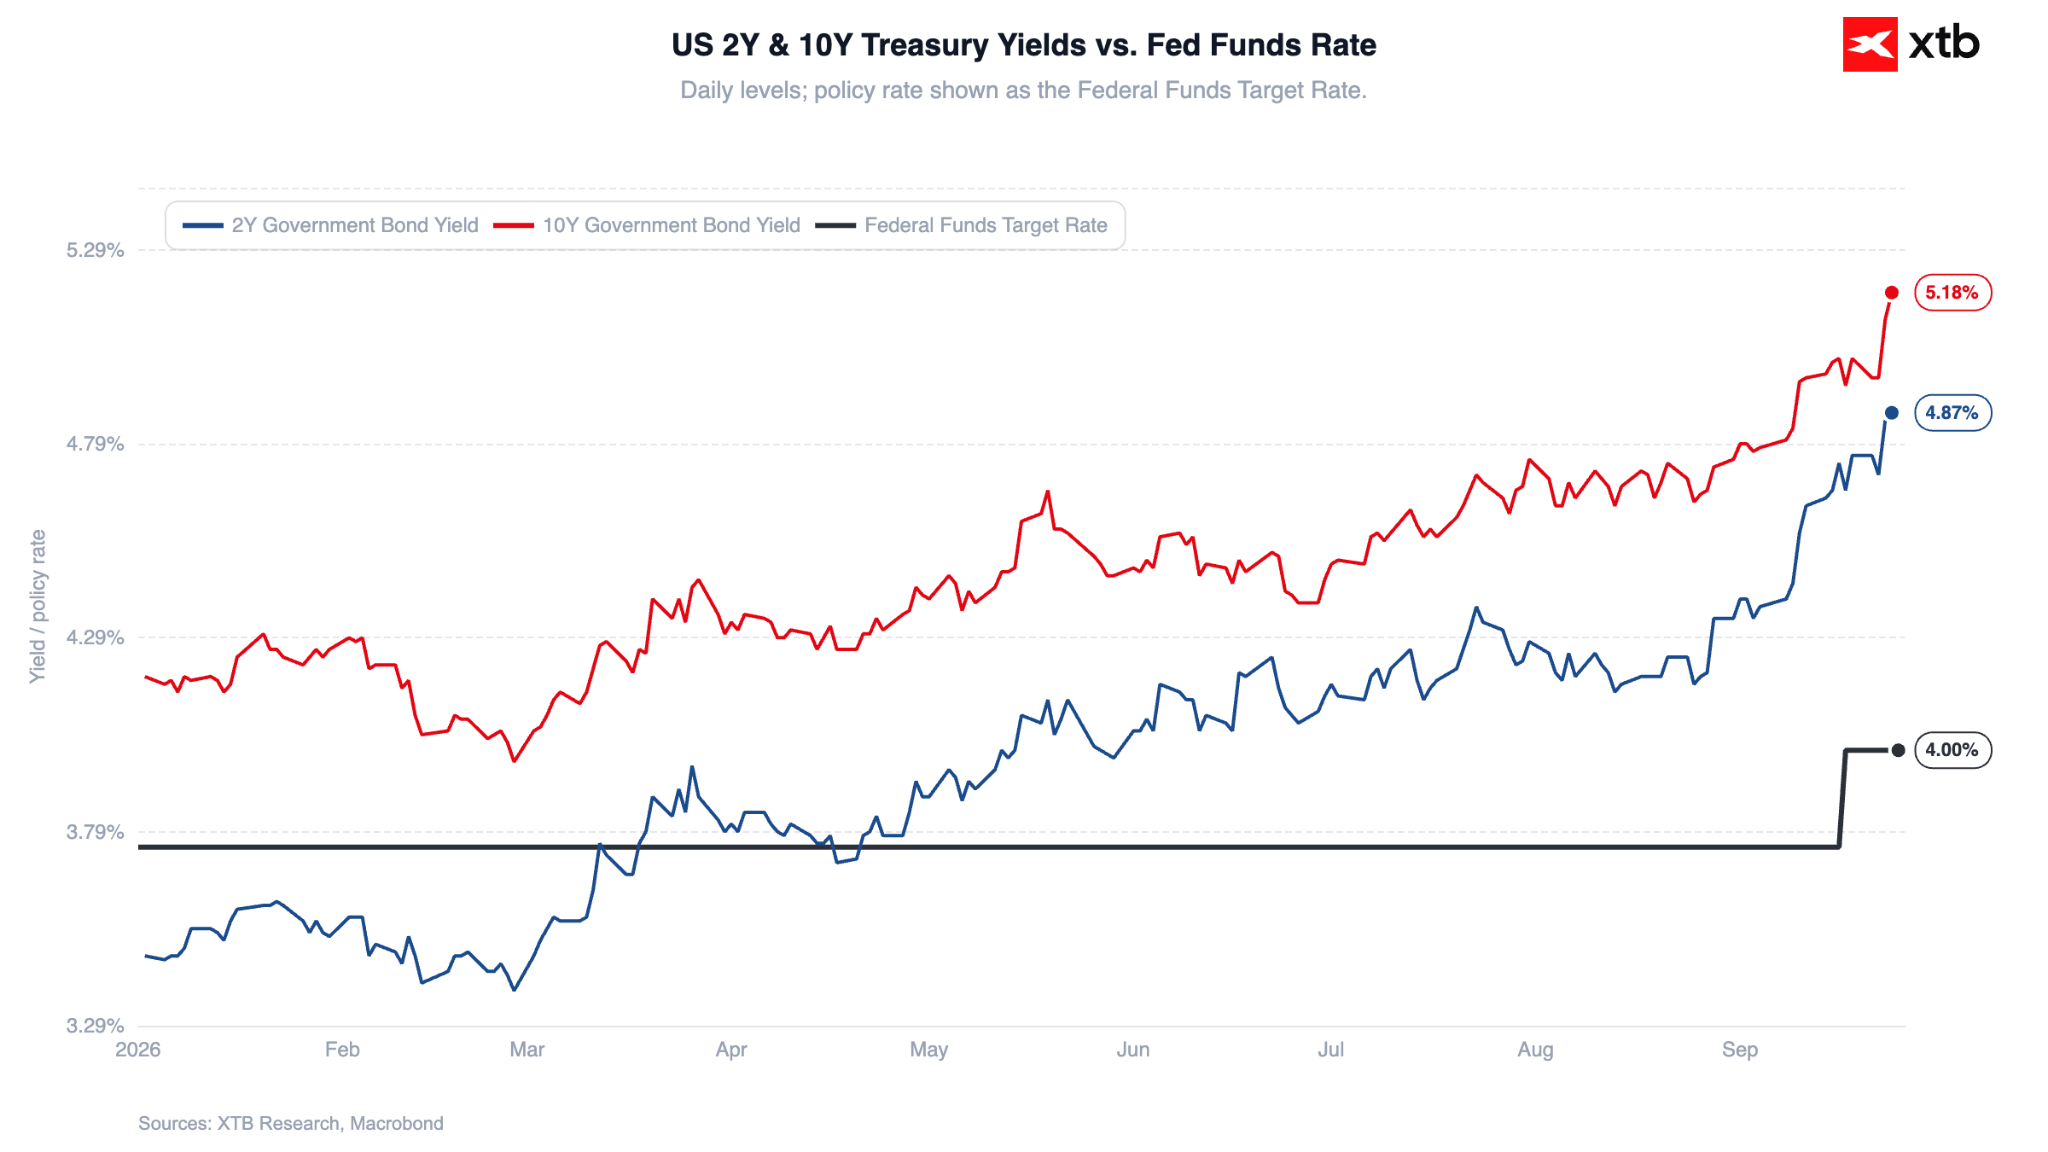
After reaching new 19-year highs (5.22%), US Treasury yields are also retreating, although the movement is currently modest at around 5 bps. Investors' focus this morning has also been drawn to the strengthening of the yen, which occurred following comments from Japan's Minister of Finance. She suggested that President Trump shares Tokyo's concerns regarding currency weakness.
Figure 2: US Treasury Yields and Federal Reserve Interest Rate (2026)
 Source: XTB Research, 25.09.2026
🛢️ Energy Commodities
US and Iranian negotiators reportedly discussed a deal on the sidelines of the UN General Assembly under which Tehran would open the Strait of Hormuz in exchange for Washington lifting the blockade on Iranian ports. Iranian Foreign Minister Abbas Araghchi informed reporters in New York that Tehran had submitted a new seven-day proposal to Washington regarding the reopening of the strait.
Tensions in the southern Arabian Peninsula remain high. On Thursday, Saudi Arabia intercepted missiles targeted at the port of Yanbu and the city of Taif, fired by Iran-backed Houthi forces. France declared it would send troops to protect Saudi energy infrastructure, joining the UK, which had previously offered support to Riyadh.
Brent crude has fallen below $99 per barrel, having gained over 7% across the preceding two sessions. WTI experienced a steeper decline, dropping towards $93.
The physical market continues to signal tightness, with the spread between prompt Brent contracts reaching its widest point since April (nearly $7). On Thursday at the primary US storage hub in Cushing, traders paid record premiums for immediate physical delivery, whilst several European refineries were notified that they would receive no crude in October under long-term contracts, a consequence of the shutdown of the Saudi East-West Pipeline.
Regarding LNG, Qatar increased tanker traffic through the Strait of Hormuz to its highest level in over two months, with at least four loaded vessels leaving the Persian Gulf over the past week.
📈 Monetary Policy and Debt Markets
The 10-year US Treasury yield eased slightly to 5.18%, following a jump of over 20 basis points across the previous two sessions. The 2-year yield fell to 4.9%. Swap markets are now fully pricing in three consecutive 25 bps rate hikes by the Fed over the coming year, driving a sell-off at the long end of the curve, where the 30-year yield reached nearly 5.5% on Thursday, its highest level in over two decades.
🪙 Precious Metals
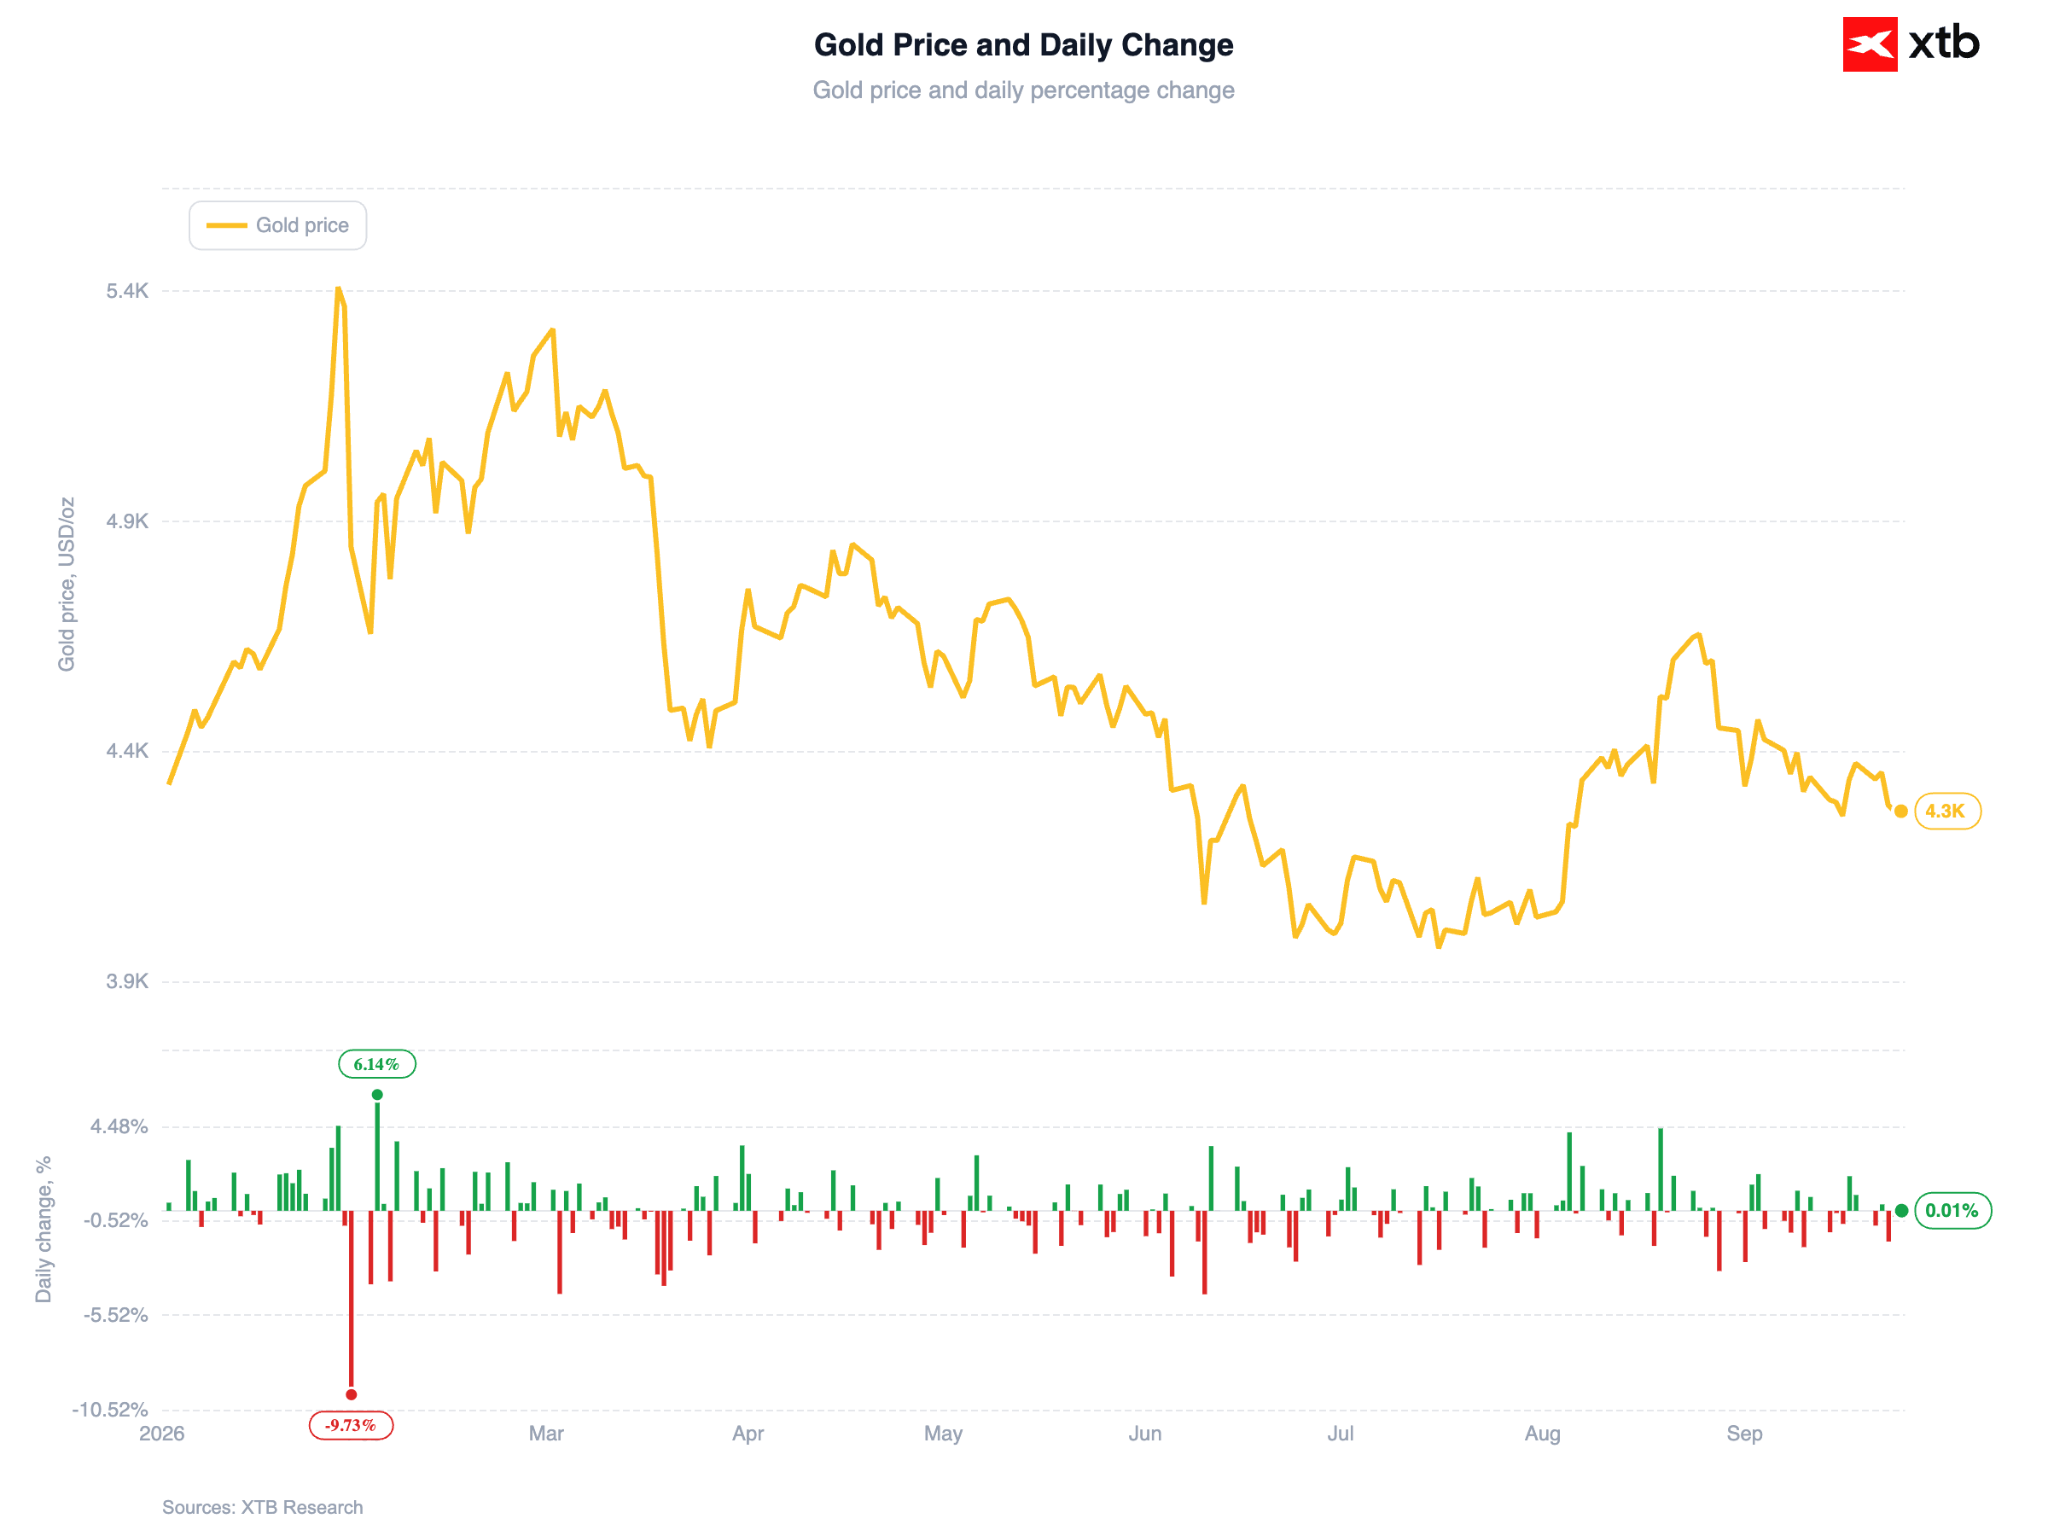
Gold is heading towards a weekly loss, with prices trading near $4,300 per ounce on Friday, down approximately 2% on the week. The metal remains under pressure primarily from elevated bond yields.
Figure 3: Gold (2026)
 Source: XTB Research, 25.09.2026
💱 Currencies
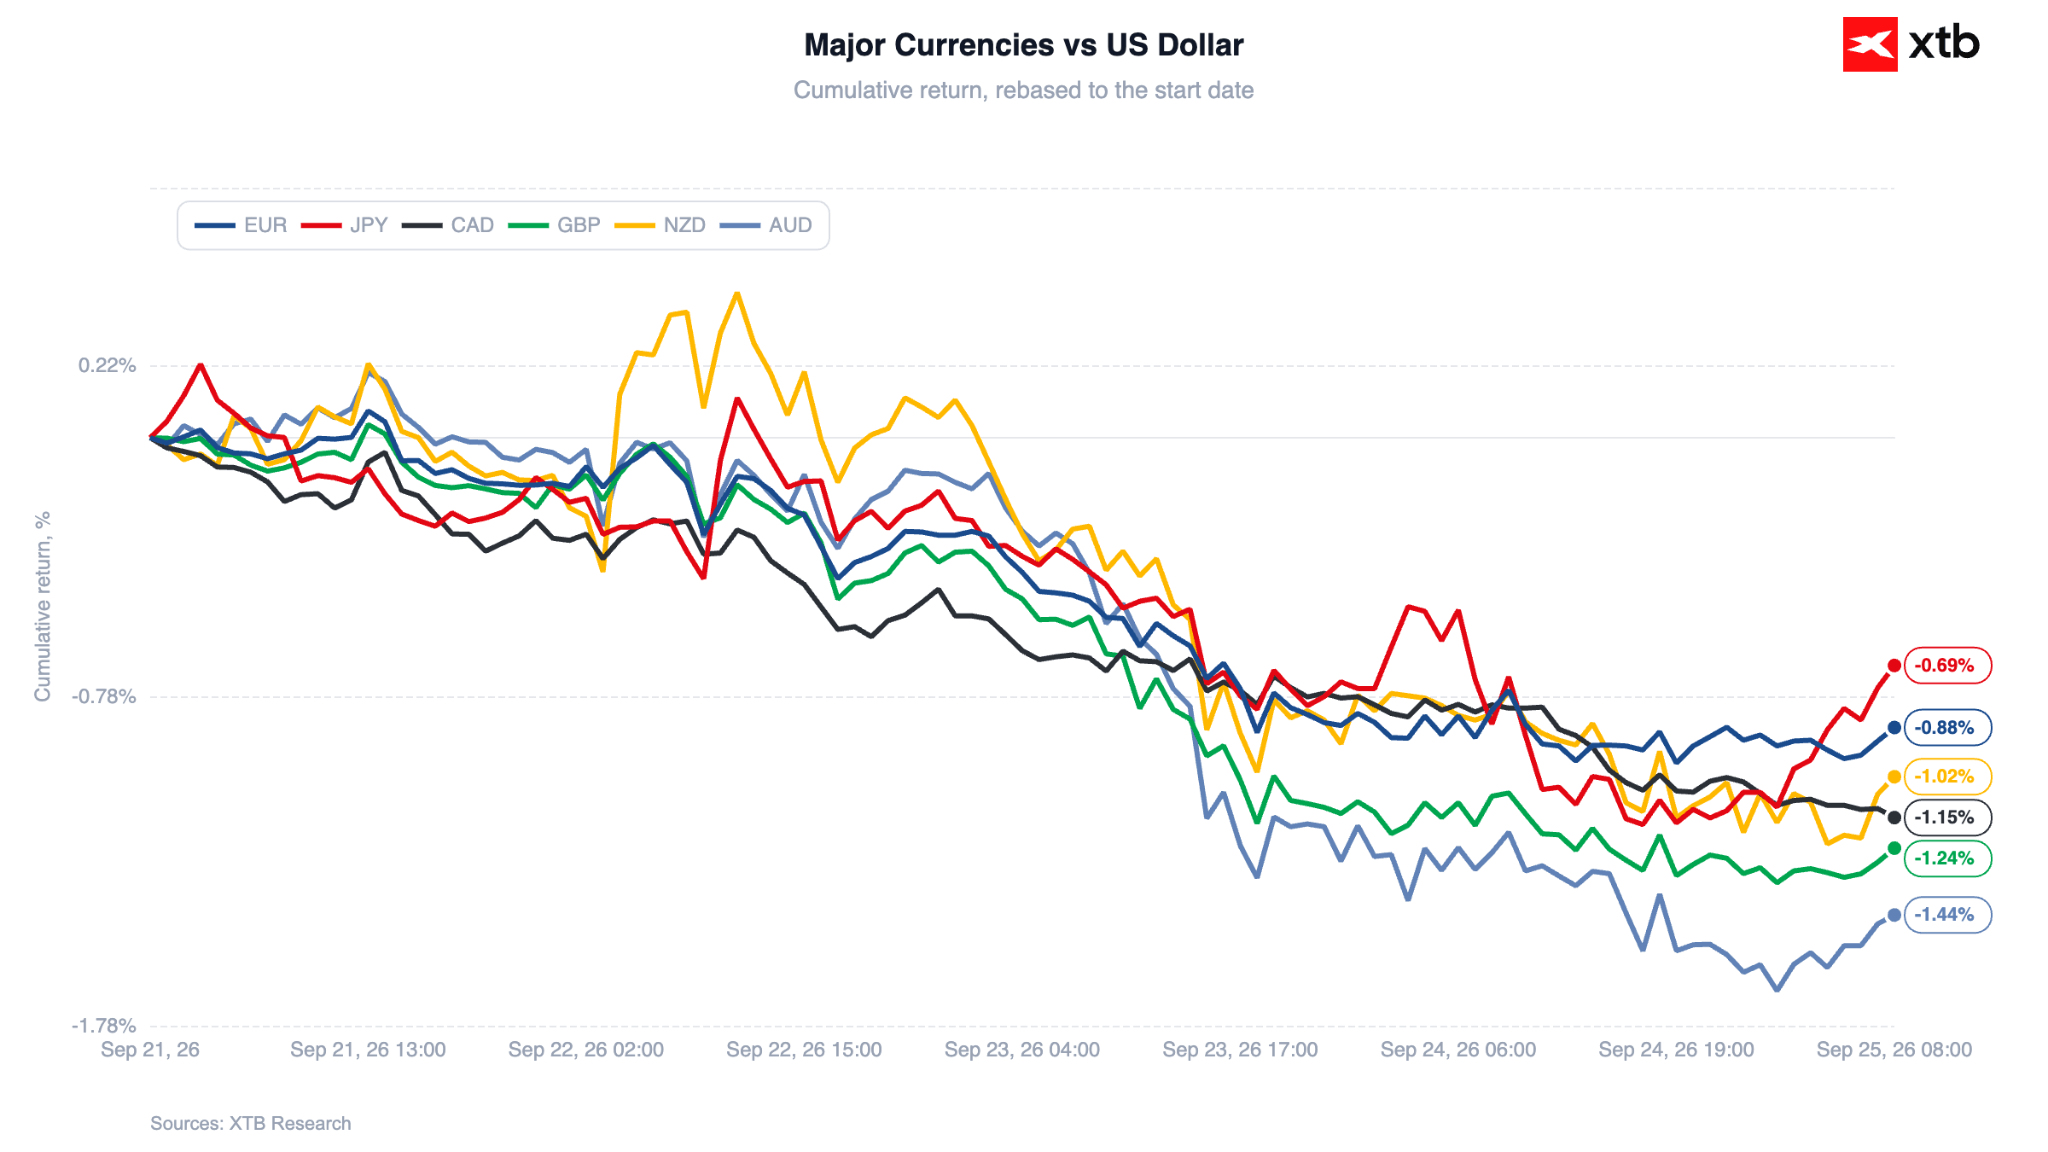
USD/JPY is approaching the 158 level after Japanese Minister of Finance Satsuki Katayama revealed that President Trump shares concerns regarding the weakness of the Japanese currency. However, the US dollar remains firm, buoyed by five consecutive sessions of gains.
Figure 4: Major Currencies Performance Against the US Dollar (21.09.2026 - 25.09.2026)
 Source: XTB Research, 25.09.2026
📈 Equities
Sentiment in Asia was mixed. Japan's Nikkei 225 gained 1.3%, whereas the Hang Seng fell 1.4% after the Trump-Xi meeting concluded without concrete agreements. Markets in South Korea, Taiwan, and mainland China were closed today for the Mid-Autumn Festival.
In corporate news, Anthropic signed a seven-year, $11.6 billion computing power agreement with Akamai Technologies, whilst Paramount Skydance plans to close a massive $52 billion debt offering next week to fund its acquisition of Warner Bros. Discovery.
—
Michał Jóźwiak, Financial Markets Analyst at XTB



Market Wrap: Further rise in oil prices weighs on European stocks (24.09.2026)


Bond yields highest since 2007


US Diesel Export Ban: Is It a problem for Europe?



Daily Summary: US dollar reaches new highs, Wall Street, gold and bitcoin fall (23.09.2026)
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.