


Wall Street recovered most of its earlier losses yesterday, with the S&P 500 finishing the session nearly flat even though most constituents advanced. Sentiment improved after comments from Fed’s John Williams, who suggested that one more rate hike may still be needed this year, but that further increases in 2027 are unlikely to be necessary.
-
Treasury yields declined, while pressure on the technology sector eased in the second half of the session. The semiconductor index ended yesterday down just around 0.2%, recovering a large part of its earlier losses, while Microsoft shares rose to a record high, illustrating how weakness in one part of Wall Street can be offset by strength elsewhere.
-
Sentiment in the technology sector remains weaker following ASML’s mixed results, while the US dollar is edging slightly lower today. Nasdaq 100 futures and European equities pared part of their gains after ASML warned that supply may not be able to fully meet demand over the next two years, although the company simultaneously raised the lower end of its 2026 sales guidance on the back of strong AI-related demand.
-
ASML reported Q3 net sales of EUR 11.66 billion versus EUR 11.72 billion expected, while net profit significantly exceeded consensus, reaching EUR 4.96 billion compared with the EUR 4.1 billion forecast. The company also narrowed its full-year revenue guidance to EUR 44–45 billion, raising the lower end from the previous EUR 43 billion.
-
For Q4, ASML expects net sales of between EUR 14.2 billion and EUR 15.2 billion, with the upper end of the range above the LSEG consensus of EUR 14.2 billion. Additional support for the company’s longer-term outlook comes from Samsung and TSMC committing to the use of High NA EUV systems, which are expected to play a key role in the next generation of advanced semiconductors.
-
Today, attention will focus on the US CPI report at 12:30 PM GMT. The market expects inflation to accelerate to 3.6% y/y from 3.4% previously and to 0.6% m/m from 0.4%. Higher gasoline prices may lift the September headline reading, although underlying price pressures excluding food and energy are expected to show signs of moderation. At the same time, Christopher Waller noted that elevated long-term Treasury yields are already tightening financial conditions in interest-rate-sensitive sectors such as housing and autos, potentially reducing the need for further rate hikes.
-
BlackRock and Bank of America are due to report earnings before the US market opens. Investors will also be watching developments from Anthropic Investor Day at around 16:00, which could influence sentiment across the AI sector. Fed’s Barkin is scheduled to speak at 19:30, while at 20:00 the Fed will publish its Beige Book, providing additional insight into conditions in the US private sector.
-
Asian equities are attempting to rebound, with the MSCI Asia Pacific Index up around 0.5% after two consecutive sessions of losses, although China remains a relatively weak point in the region. The CSI 300 is down around 0.3% and is approaching technical bear-market territory after falling more than 15% from its June peak.
-
China’s September CPI inflation came in slightly below expectations at 0.9% y/y versus 1.0% forecast and 0.8% previously, while on a monthly basis it rose 0.2% compared with 0.4% previously. Producer price inflation, meanwhile, increased by 5.0% y/y versus 4.4% expected and 3.8% previously.
-
Brent crude is up around 0.6% and has moved above USD 106 per barrel amid intensifying attacks in the Middle East and growing uncertainty over the recovery of energy shipments from the Persian Gulf. Yesterday, the Houthis warned of potential attacks on Saudi oil infrastructure.
-
The Fed remains committed to its 2% inflation target, with Susan Collins stressing that the central bank is not reconsidering it. She also noted that the Fed is taking a holistic view of the economy when assessing monetary policy, paying close attention to the breadth of inflation pressures and the elevated level of economic uncertainty.
-
Collins acknowledged that high interest rates are creating challenges for the economy, while Fed models also take government debt levels into account. This suggests that future rate decisions will continue to depend on the balance between inflation, economic conditions and the costs of maintaining restrictive monetary policy.
-
Geopolitical and energy risks also remain in the background: CENTCOM said US forces helped Gulf partners move more than 19 million barrels of crude oil through the Strait, while President Zelenskiy said a Russian ballistic missile attack on Kyiv primarily targeted energy infrastructure, including CHPP-4.
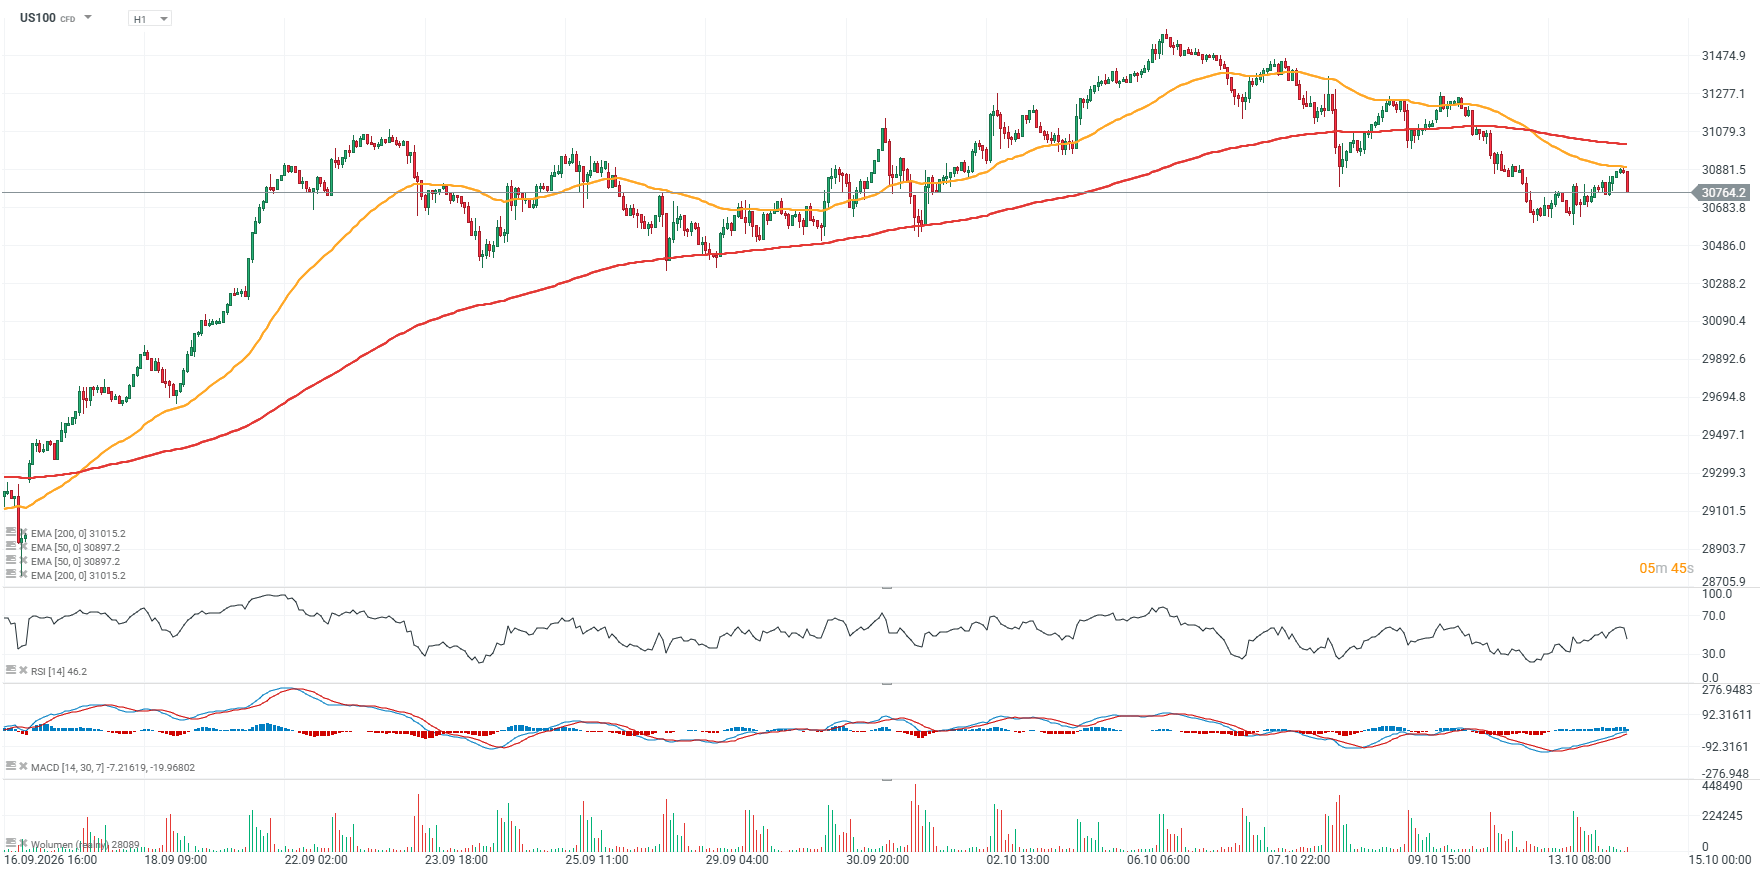
US100 chart (H1 interval)
The Nasdaq 100 futures contract pulled back once again shortly after reaching the EMA50 (orange line, around 30,900 points), which remains the key resistance level for now. ASML’s solid, though not flawless, earnings report triggered a sudden downside reaction in the index, while the main support area now appears to be around 30,600 points, reinforced by recent price reactions.
Source: XTB



Economic Calendar - Start of Wall Street Earnings Season, Hawkish RBA, and Middle East Tensions (13.10.2026)



Morning Wrap: Tech Crash in Asia and Hawkish Central Banks in the Shadow of an Oil Shock (13.10.2026)



📊Market Wrap: Europe Rebouns Despite Higher Oil and Dollar (12.10.2026)


Chart of the Day: Will the RBI's bold regulatory package rescue the rupee? (12.10.2026)
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.