


Nickel is extending its decline today, falling to its lowest level since late December 2025 following new forecasts from the International Nickel Study Group (INSG). The organization expects the global nickel market to end 2026 with a modest supply surplus, which is projected to widen further in 2027. This marks a significant shift from April, when the INSG was still forecasting a deficit for 2026.
-
Global demand for primary nickel is expected to reach around 3.85 million tonnes in 2026, up 7.6% from a year earlier, while production is forecast at approximately 3.87 million tonnes.
-
This would leave the market with a surplus of around 19,000 tonnes in 2026, compared with the 32,000-tonne deficit projected in April, which would have represented the first annual supply shortfall since 2021.
-
In its previous forecast, the INSG expected 2026 demand of 3.75 million tonnes and production of 3.72 million tonnes, indicating that both consumption and supply are growing faster than previously anticipated.
Although the INSG expects demand from the stainless steel sector to increase further in the second half of 2026 and throughout 2027, nickel use in electric vehicle batteries has so far grown more slowly than expected due to increasing competition from LFP technology (lithium iron phosphate batteries). Indonesia, the world’s largest nickel producer, approved lower nickel ore production quotas for 2026 than a year earlier. Applications for 2027 production quotas can be submitted until November 15.
For 2027, the INSG expects both demand and supply to continue rising, but the market surplus is forecast to widen to around 70,000 tonnes. Global nickel consumption is expected to reach approximately 4 million tonnes, while production is projected at around 4.07 million tonnes. From a nickel price perspective, the forecasts have a bearish implication, as rising demand is still expected to be more than covered by even faster growth in production. Indonesia will therefore remain a key factor for the market, particularly in the context of future mining quotas.
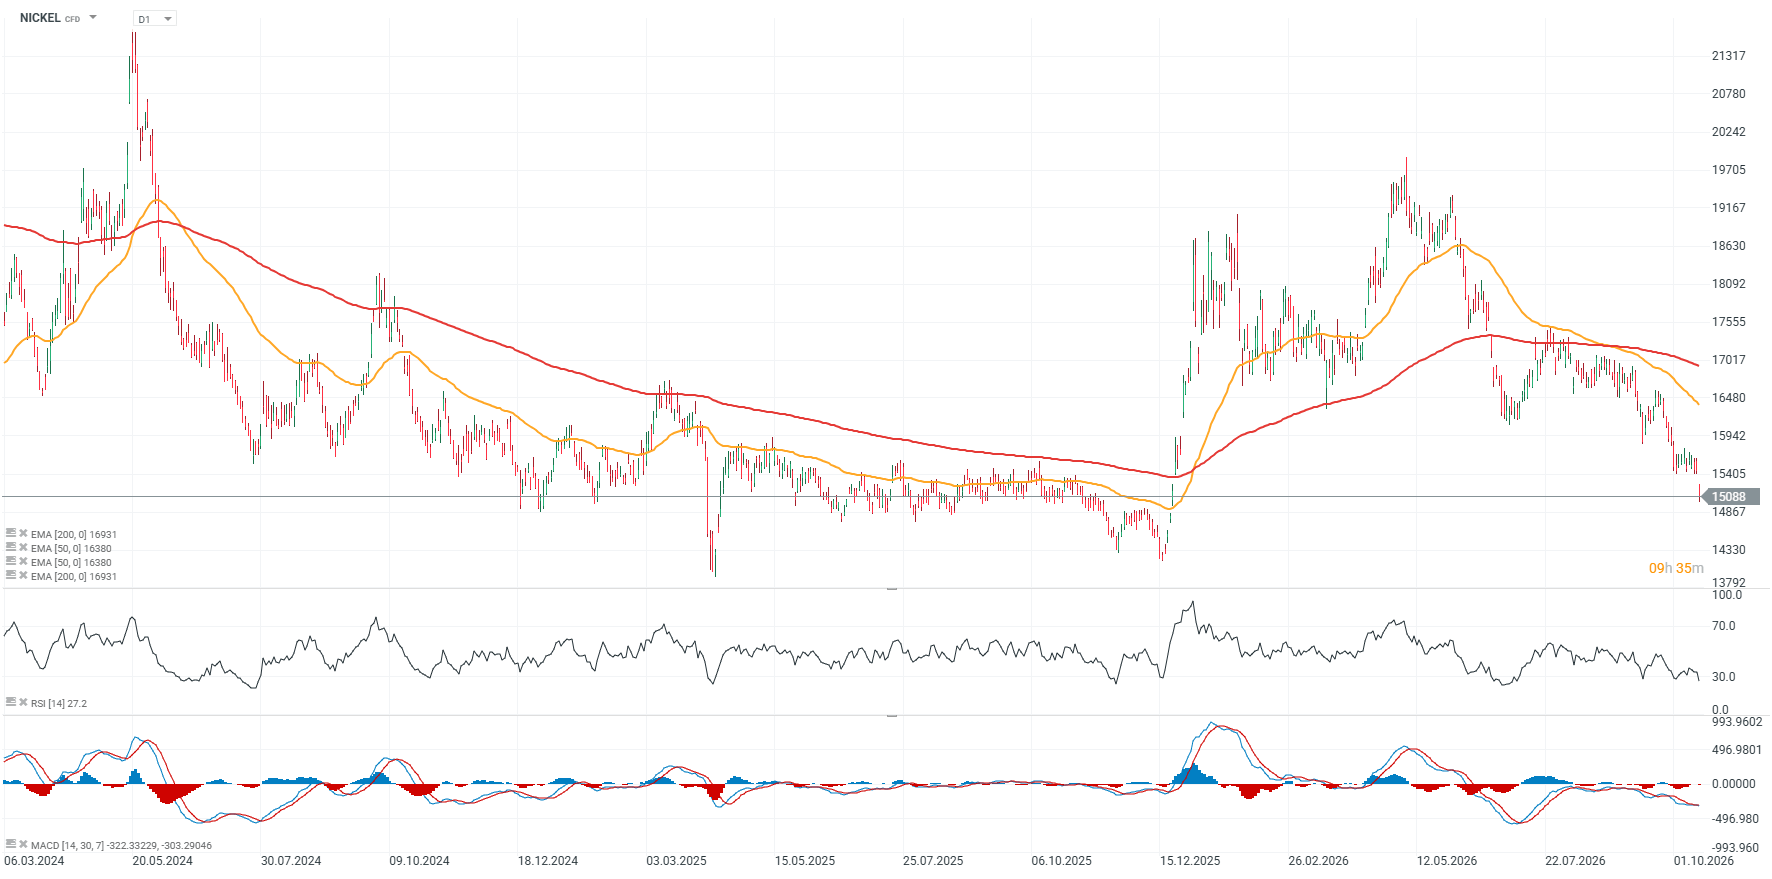
Nickel price chart (NICKEL), D1 interval
Looking at the nickel chart, the RSI has fallen below 30, indicating the most pronounced oversold conditions since early December 2025, while the price is trading around 10% below the 200-session exponential moving average (EMA200), clearly confirming the bearish trend. The first objective for bulls would be a recovery toward 15,600, with potentially key resistance around 16,500, while an important technical support zone can be found between 13,800 and 14,000. However, it is far from certain that the price will fall that low, as technically it has moved close to an important support area corresponding to the broad consolidation range seen in 2025. As a result, the market may at least temporarily begin to stabilize around current levels while waiting for an external catalyst.
 Source: XTB


Hot inflation data from the US🔥📈 PPI and retail sales are rising!



Market Wrap: Tech Sell-Off Hits Europe, Gold Shines Again

Gold sell-off over? 🔼 Central banks buy the most in nearly two years


Sell-off in the semiconductor market 📉🖥️
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.