


- Novo Nordisk posted revenue of 79.2 billion DKK, beating market consensus of 73.5 billion DKK.
- Adjusted operating profit rose 34% to 31.72 billion DKK, driven by strong oral Wegovy sales.
- Management upgraded the full-year guidance range for adjusted revenue and operating profit to between -2% and +2%.

- Novo Nordisk posted revenue of 79.2 billion DKK, beating market consensus of 73.5 billion DKK.
- Adjusted operating profit rose 34% to 31.72 billion DKK, driven by strong oral Wegovy sales.
- Management upgraded the full-year guidance range for adjusted revenue and operating profit to between -2% and +2%.
The Danish pharmaceutical group published results that positively surprised the market. Initial gains reached as much as 5%, but over time the market gave back a large part of the move and limited the rise to around 2%. This may be a positive signal for the company’s operating condition, which is still waiting for a meaningful demand impulse after many months of sell-off.
Earnings
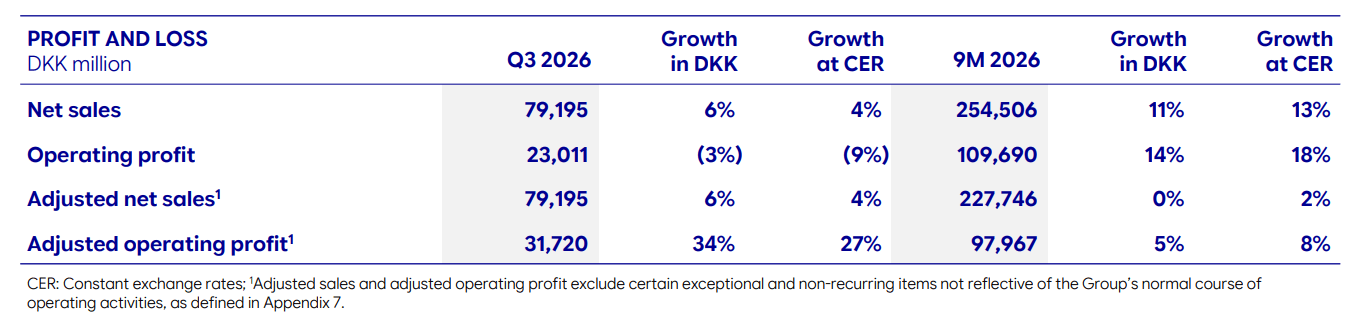
- The company’s revenue increased to DKK 79.2bn, up 6% year on year, which is significantly above the consensus of about DKK 73.5bn (DKK is the Danish krone).
- The “star” of the release, however, was adjusted operating profit. It rose 34% to DKK 31.72bn versus expectations of around DKK 28.7bn.
- Attention should be paid to net profit, which came in at DKK 16.7bn. This is a 16% year-on-year decline.
The takeaway from these data is mixed. First of all, a clear operational improvement is visible, and it is above market expectations. It is driven mainly by oral Wegovy. Sales totaled DKK 5.39bn, representing a 53% increase quarter on quarter. The entire obesity treatment segment generated DKK 26.15bn in revenue, growing 24% year on year.
However, the quality of earnings remains an issue.
- First, net profit fell, which means the improvement above is merely a slowing of the profit erosion trend.
- Second, at constant exchange rates, revenue rose 4% and adjusted operating profit rose 27%. The latter benefited from a low base, as the result a year earlier was burdened by about DKK 9bn in “transformation costs”.
- In addition, this year’s reported EBIT was burdened by DKK 8.7bn in impairments: DKK 4.6bn related to ziltivekimab and DKK 4.1bn related to adjustments to the production network. These impairments are non-cash, but they signal a loss in value of previous investments.
This means that the improvement in operating profit cannot be equated one for one with an improvement in the core business.
Guidance and outlook
More optimistic than the results themselves is management’s guidance.
- Both adjusted revenue and operating profit received an upgraded full-year outlook, from a range of -6% to 0% to a range of -2% to +2%.
- For the investment outlook, the key question remains whether the expansion of oral drugs will offset pricing pressure and competition. From January 2027, Novo plans to cut US list prices for Wegovy and Ozempic by about 50% and 35%.
- A positive catalyst that investors may be waiting for is the launch of CagriSema in the US in early 2027, subject to regulatory approval.



BREAKING: Democrats take both chambers of Congress🗽

Super Micro's Revenue Explodes, Nearly Quadrupling on AI Demand


Arista Networks shares jump 6% after earnings 📈 Revenue growth hits its highest level since IPO

AMD shares jump 7% after stellar earnings 🔼 Will semiconductor stocks return to growth?
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.