


U.S. crude oil inventories fell by 8.557 million barrels, while the market had expected an increase of 0.150 million barrels; inventories had declined by 3.186 million barrels previously. The draw in crude and distillate inventories was not offset by the increase in gasoline stocks, which came in far above expectations.
- Gasoline inventories rose by 3.518 million barrels, well above the expected decline of 0.911 million barrels; inventories had increased by 0.382 million barrels previously.
- Distillate inventories fell by 2.527 million barrels, more than the expected decline of 1.720 million barrels; inventories had decreased by 0.042 million barrels previously.
- Crude inventories at the Cushing hub increased by 1.862 million barrels, compared with a rise of 0.444 million barrels in the previous week.
U.S. oil market tightens as inventories fall below seasonal norms
The latest EIA report reinforces a relatively supportive short-term picture for the U.S. oil market. Commercial crude inventories are now 3% below the five-year average for this time of year, while total commercial petroleum stocks fell by a substantial 13.4 million barrels, indicating that the broader inventory draw extended well beyond crude alone. Refinery activity remained strong, with crude inputs averaging 16.6 million barrels per day, up 135,000 bpd from the previous week, and utilisation reaching a high 93.5% of operable capacity. At the same time, crude imports fell sharply by 791,000 bpd to 6 million bpd, reducing the amount of foreign supply entering the domestic system and helping explain the larger-than-expected inventory draw. Gasoline production increased to an average of 9.2 million bpd, suggesting refiners are still responding to downstream demand despite already elevated utilisation rates. Taken together, the combination of lower inventories, reduced imports and strong refinery runs is fundamentally supportive for WTI, although the rise in gasoline stocks means the demand side of the report is not uniformly bullish.
OIL.WTI chart (D1 interval)
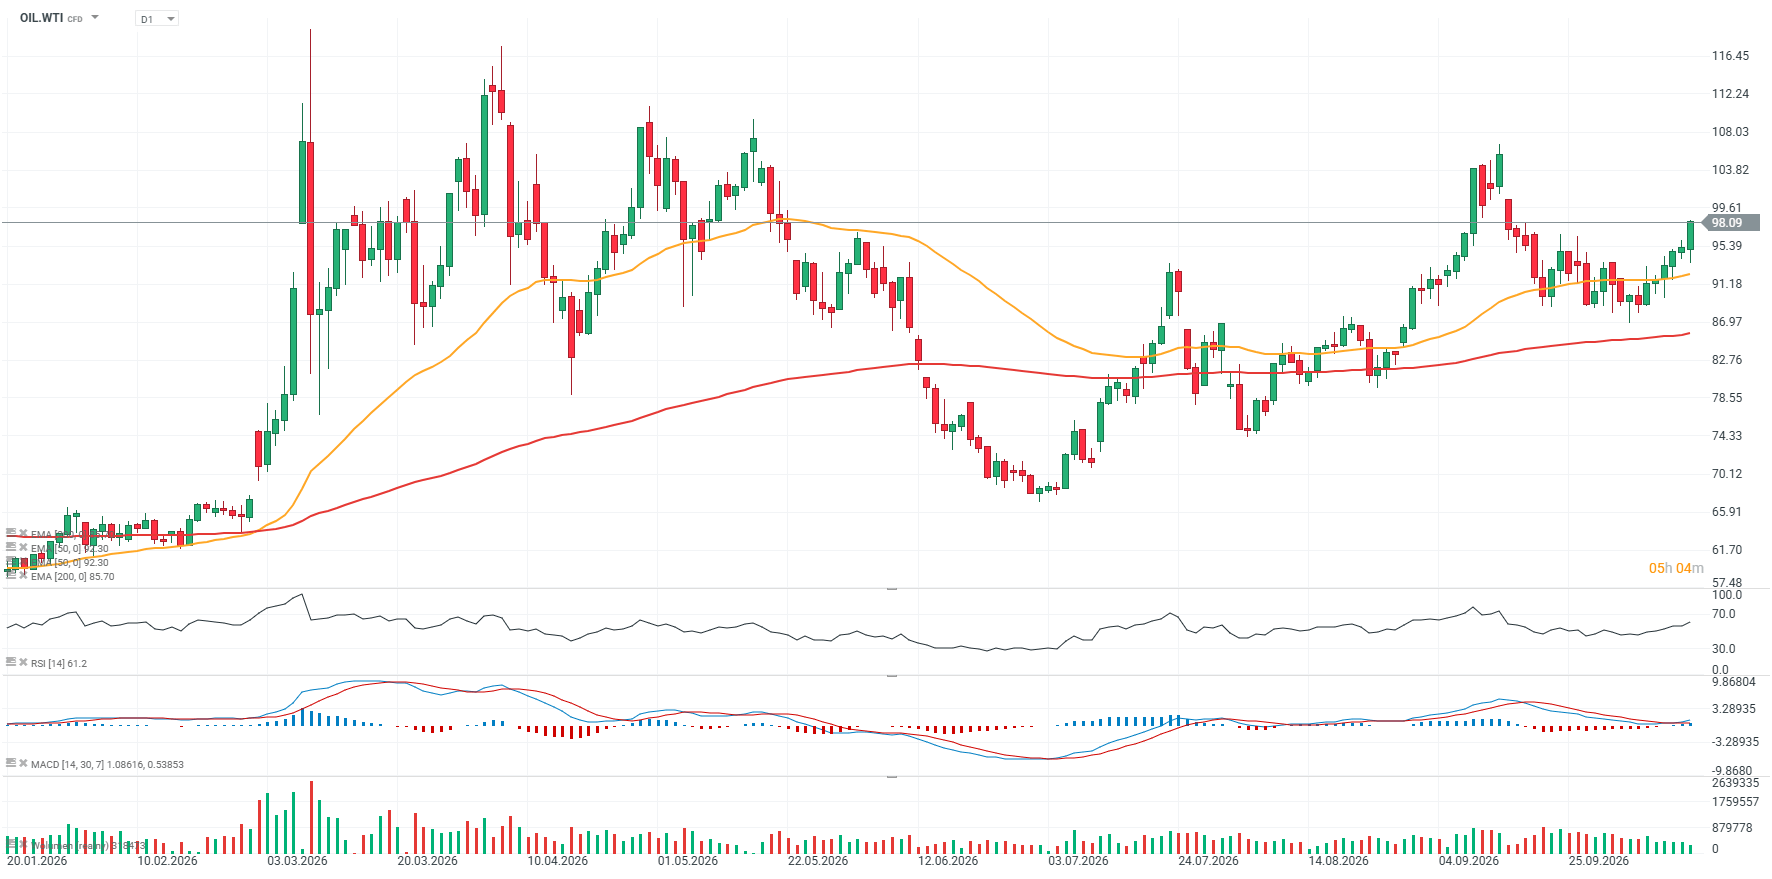 Source: XTB

U.S. indices attempt to rebound after recent losses


Hot inflation data from the US🔥📈 PPI and retail sales are rising!

Nickel market panic 🚩 INSG revises forecast, surplus in 2027?



Market Wrap: Tech Sell-Off Hits Europe, Gold Shines Again
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.