


Palo Alto is one of the few companies with such a clean, high quality exposure to cybersecurity themes. Yesterday’s earnings release shows that both the cybersecurity industry and the company’s position within it are in better shape than ever.
Earnings
Large, high profile hacking attacks involving (confirmed or alleged) AI are becoming more frequent, which naturally raises expectations for results. The market backdrop and expectations were a challenge for the company ahead of earnings, but it cleared that hurdle with relative ease.
- The company’s revenue rose to USD 3.44bn, representing 39% year over year growth, beating expectations around USD 3.3bn.
- Remaining performance obligations (RPO, the order backlog) increased to USD 21bn, up 35% year over year.
- Annual recurring revenue (ARR) from “next generation” products reached as much as USD 9.73bn, up 66%. This is a particularly important line item because it directly signals that margin and revenue improvement is not only the result of rapid, aggressive monetization of new products, but also that this revenue is stable and long lasting rather than episodic.
- Adjusted EPS came in at USD 1.05 per share versus expectations of USD 0.97, up 13% year over year. This corresponds to an adjusted operating margin of 30.7%, an increase of 0.5 percentage points year over year.
- Free cash flow rose to USD 1.84bn, up 9% year over year.
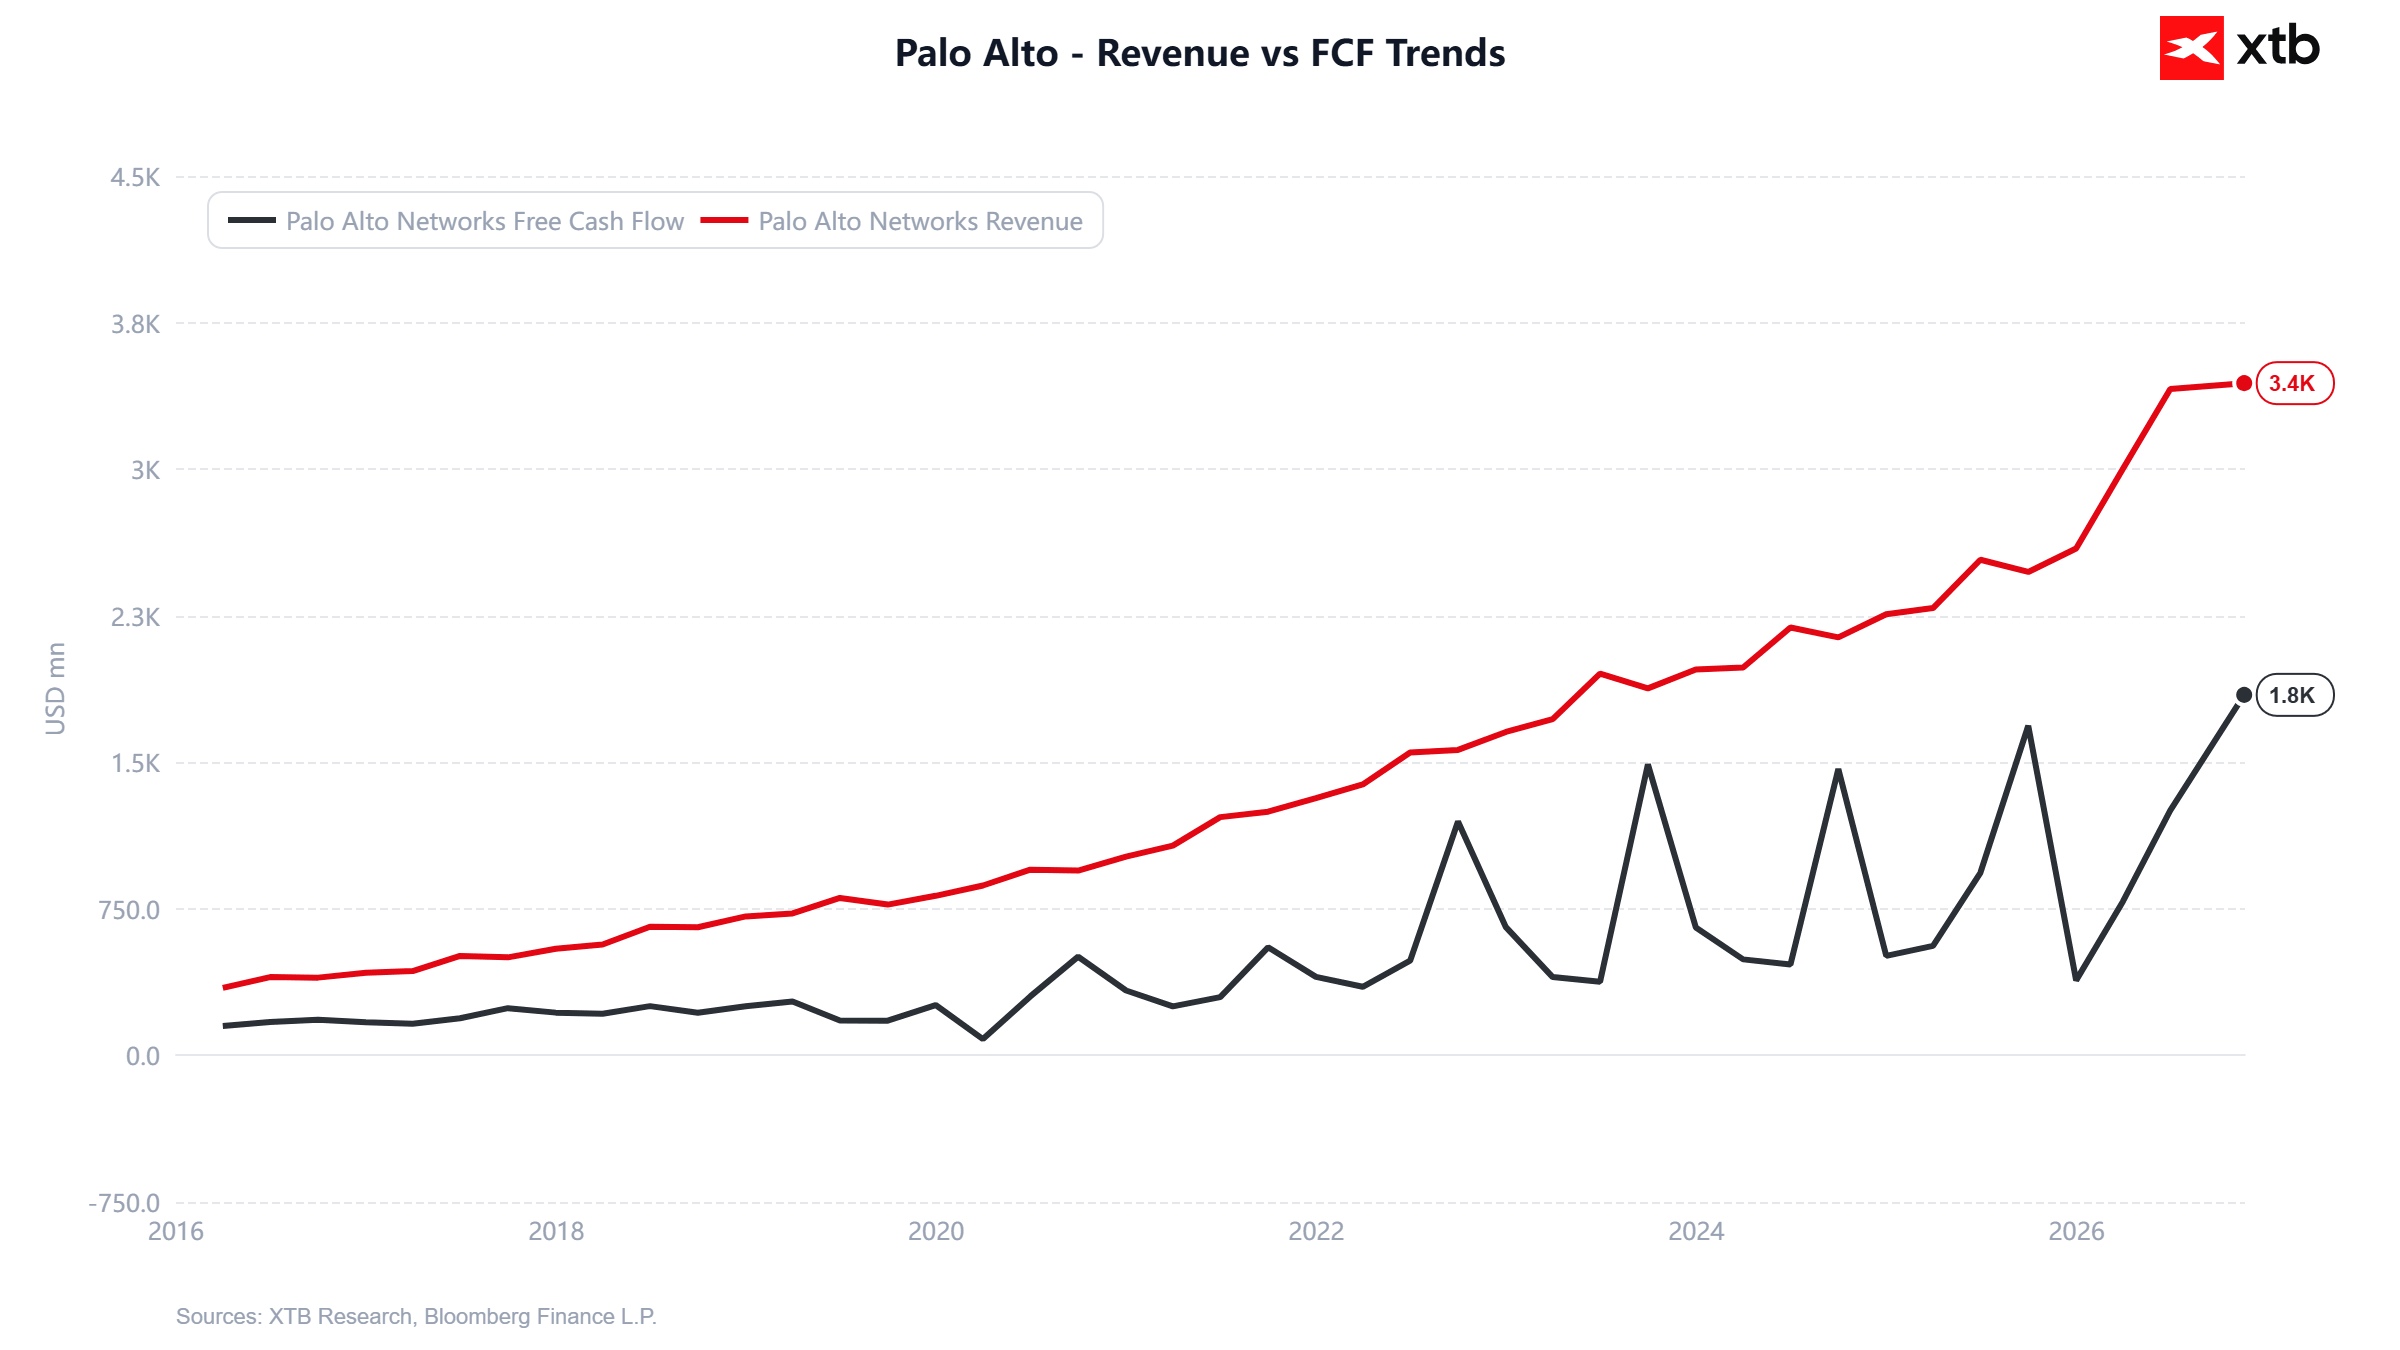
The strongest element is the breadth of demand alongside the sheer scale of growth. The company is posting double digit revenue growth across all business segments while sustaining significant expansion in long term orders.
The key challenge is monetization and profitability, which in pace still trails absolute growth. This can be viewed from two perspectives:
- The company is struggling with the pace of profitability growth and the monetization of its solutions.
- The company is prioritizing capturing the maximum market share and customer count during a critical expansion period, and then monetizing more easily and effectively later, but with a delay.
This interpretation is crucial for sentiment toward the company, but for now everything indicates the market leans more toward the second view. The guidance partially supports that.
Guidance
- Full year revenue guidance increased from USD 14.10 to 14.20bn to USD 14.52 to 14.57bn. The midpoint was raised by about 2.8%. This is a conservative increase, but it comes off an already high base.
- The company expects non GAAP EPS of USD 4.26 to 4.30, an operating margin of 29.5%, and an adjusted FCF margin of 38%.
- This guidance excludes Applied Compute, Palo Alto’s newly planned acquisition. The CFO said the deal could reduce the operating margin by up to 1 percentage point in FY2027 and 2 percentage points in FY2028.
- In response to a question from Joshua Tilton of Wolfe Research, Nikesh Arora pointed to the possibility of monetizing additional agent traffic in SASE over a 6 to 9 month horizon. This is a management signal rather than already contracted revenue. The test will be whether sales growth exceeds the incremental costs of handling the traffic.
Conclusion
The company delivered another excellent quarter in a row and raised guidance. Valuation gains show that sentiment toward the stock is very strong, even against the backdrop of poor conditions across much of the tech sector in recent months (in valuation terms).
No sentiment lasts forever, though. Questions about further monetization, the rationality of the company’s M&A pricing, and pressure from investment spending could turn investor favor faster than most expect. Management will need to keep managing investor expectations on these fronts over the coming quarters, and so far it has been doing that very well.



Morning Wrap: Time for the largest stock market debut in history (19.11.2026)



🔴US500 decrease ahead of FOMC minutes

US OPEN: Nvidia Isn’t Enough as Wall Street Slips Back Into the Red



Market Wrap: Stocks under pressure, Iceye reaches for Avio
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.