



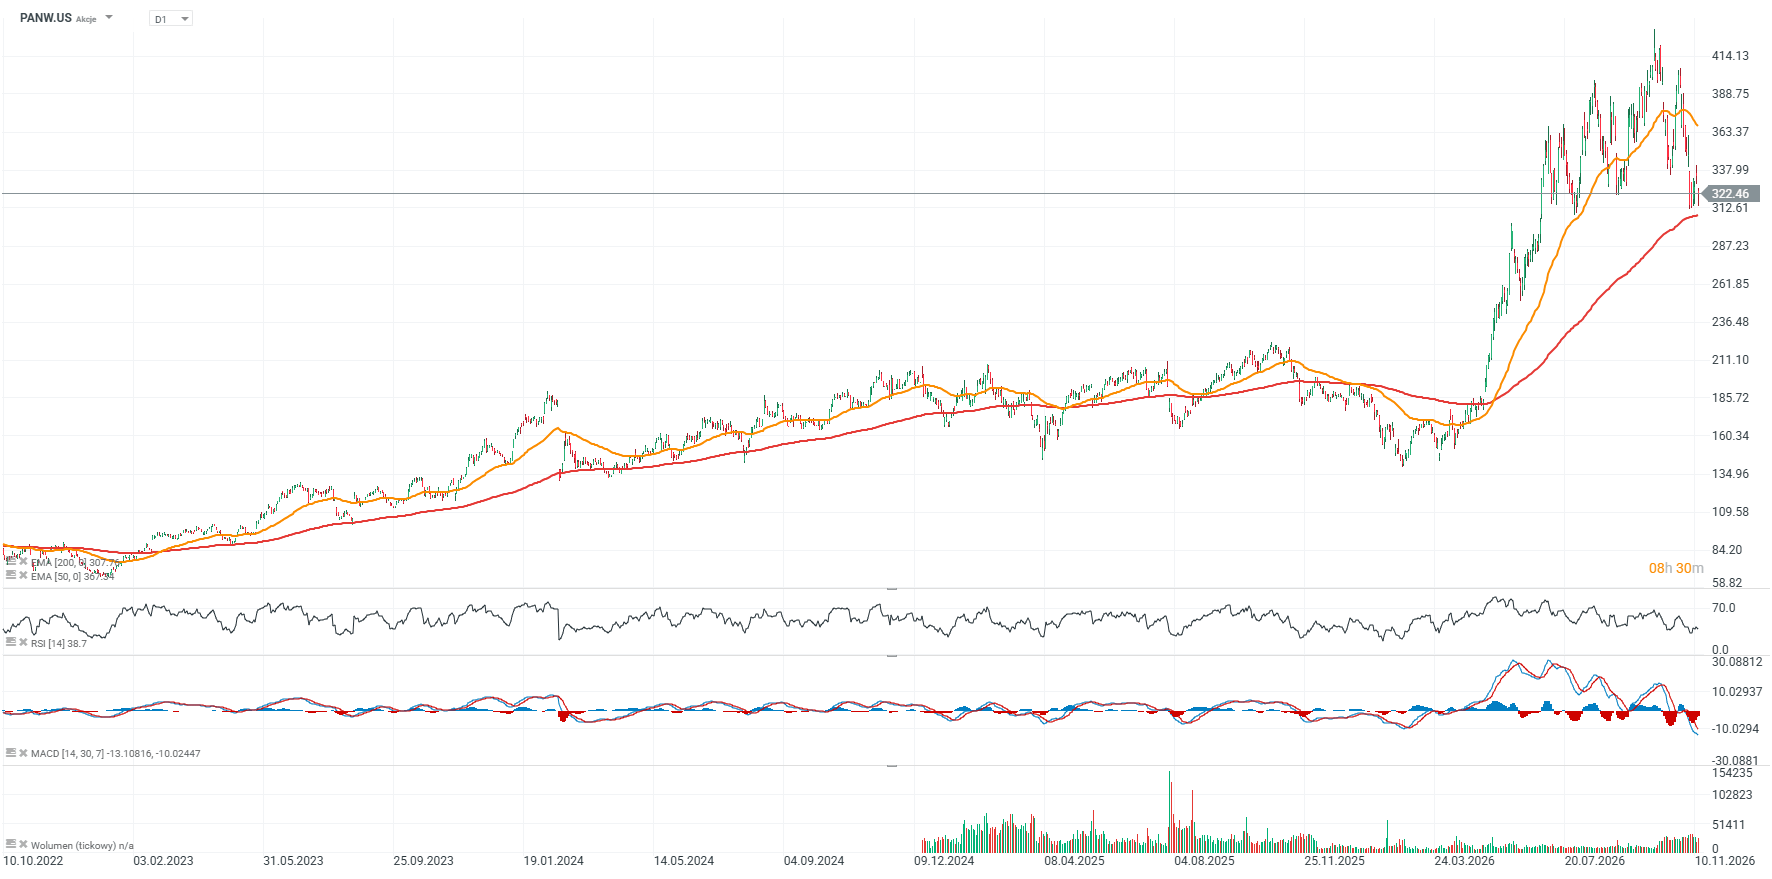
Palo Alto Networks shares are gaining nearly 3.5% in pre-market trading after KeyBanc analysts upgraded the stock from "Sector Weight" to "Overweight", setting a price target of $380 compared with yesterday's closing price of $322. The bank believes the stock's roughly 20% decline over the past month could represent an attractive investment opportunity, particularly given expectations of accelerating cybersecurity spending in 2027. The company is scheduled to report its quarterly earnings on November 18, 2026.
-
Cybersecurity budgets could grow by more than 20% in 2027, compared with single-digit growth at the beginning of 2026 and an expected acceleration to around 15% by the end of this year. These estimates are based on KeyBanc's discussions with Chief Information Security Officers (CISOs).
-
The development of AI is increasing the scale and complexity of cyber threats, prompting companies to invest more heavily in protecting their infrastructure, data, and artificial intelligence systems.
-
Palo Alto Networks and CrowdStrike could be among the main beneficiaries of industry consolidation, as enterprises increasingly reduce the number of security vendors they use and shift toward comprehensive cybersecurity platforms.
-
KeyBanc is positive about Palo Alto's fiscal first-quarter earnings outlook, also pointing to strong demand among channel partners. In the third quarter, all surveyed resellers met or exceeded their sales targets.
-
Palo Alto's competitive advantage could be strengthened by the development of agentic AI in cybersecurity, where extensive proprietary datasets and integrated solutions may create barriers to entry for new competitors, including large language model providers.
According to KeyBanc, Palo Alto Networks is well positioned to benefit from rising cybersecurity spending, although the realization of this scenario will depend on actual customer budget growth and the company's ability to maintain its competitive advantage.
Why could Palo Alto Networks be one of the biggest beneficiaries of AI growth?
The development of artificial intelligence is reshaping cybersecurity spending, and Palo Alto Networks could benefit not only from overall market expansion but also from gaining market share from competitors. More enterprises are moving away from numerous standalone security tools toward integrated platforms covering network security, cloud protection, identity management, and security operations centers (SOCs). This strategy, which Palo Alto calls platformization, could increase contract values, recurring subscription revenue, and customer switching costs.
The company already has financial results supporting the effectiveness of this model. In fiscal Q4 2026, revenue increased 34% year-over-year to $3.41 billion, while Next-Generation Security annual recurring revenue (NGS ARR) surged 63% to $9.1 billion. Moreover, more than 65% of NGS ARR came from customers using integrated platforms. As autonomous AI agents become more widespread, automated threat detection and incident response are becoming increasingly important, potentially strengthening the competitive position of providers with extensive proprietary cybersecurity datasets.
Does Palo Alto Networks' 20% share price decline present an investment opportunity?
According to KeyBanc, the recent sell-off does not reflect the improving outlook for the cybersecurity industry, while its $380 price target implies approximately 18% upside from the November 12 closing price. This assessment is primarily driven by expectations of accelerating cybersecurity spending in 2027, although higher customer budgets do not necessarily translate into proportional earnings growth for Palo Alto. Maintaining strong recurring revenue growth, improving profitability, and successfully integrating acquired businesses will be particularly important.
The next major test will come with the company's fiscal Q1 2027 earnings release, scheduled for November 18. Palo Alto forecasts revenue of $3.30–3.31 billion and NGS ARR of $9.54–9.56 billion. However, the key question for investors will be not only whether the company exceeds expectations, but also the quality of its growth, particularly the contribution from organic expansion and its conversion into cash flow. Acquisitions can accelerate Palo Alto's growth, but they also increase business complexity and make it more difficult to assess the underlying performance of its core operations.
 Source: XTB


US PPI lower than expected 🗽 Markets react to macro data



Morning Wrap - Will the markets recover from the scandal involving Nvidia's ousted CEO❓
Daily Summary: Oil Rebounds, EURUSD Falls Sharply 🗽 Wall Street Stabilizes After Nvidia Sell-Off

Oil Gains Nearly 2% Despite a Sharp Rise in US Inventories 📈
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.