


The monetary policy outlook in Australia is once again shifting toward further tightening. Reserve Bank of Australia (RBA) Deputy Governor Andrew Hauser warned that the inflation outlook is significantly worse than the central bank had previously forecast and that price pressures could prove more persistent than expected. Particular concern surrounds underlying inflation, as measured by the trimmed mean, which is likely to exceed the RBA’s earlier projections in the third quarter. Hauser also highlighted the risk of inflation expectations becoming unanchored, noting that some businesses are beginning to treat inflation of 3–3.5% as the new normal. His remarks significantly increased expectations of another interest rate hike as early as November 3. The probability of a 25 bp increase to 4.85% rose from around 20–22% to nearly 50%, although market-implied probabilities vary depending on the time of measurement. This would mark the fifth rate hike in 2026, following September’s increase in the cash rate to 4.60%.
Australia’s inflation problem reflects both external and structural factors. According to the latest data, CPI inflation accelerated to 4.0% YoY in August from 3.5% in July, while trimmed mean inflation remained at 3.6%, well above the RBA’s target range. Price pressures are being reinforced by elevated energy costs linked to the conflict in the Middle East, capacity constraints, and weak productivity growth. In addition, the global investment boom surrounding artificial intelligence is increasing demand for certain technology-related goods. According to the RBA, businesses are increasingly passing higher costs on to consumers, making it more difficult to bring inflation sustainably back to target.
The Australian economy is showing increasingly clear signs of slowing, complicating the central bank’s policy decisions. The unemployment rate rose to 4.7% in September, its highest level in five years, while employment fell by 39,300. Hauser acknowledged that previous rate hikes are beginning to weigh on economic activity, but argued that this does not eliminate the threat of persistent inflation. The RBA therefore faces a difficult trade-off between restoring price stability and avoiding an excessive slowdown in economic activity. The key upcoming event remains the release of Q3 inflation data on October 28, just days before the November policy meeting. A stronger-than-expected trimmed mean reading could tip the balance toward another rate hike. Goldman Sachs, UBS, and ANZ all expect the RBA to raise rates in November.
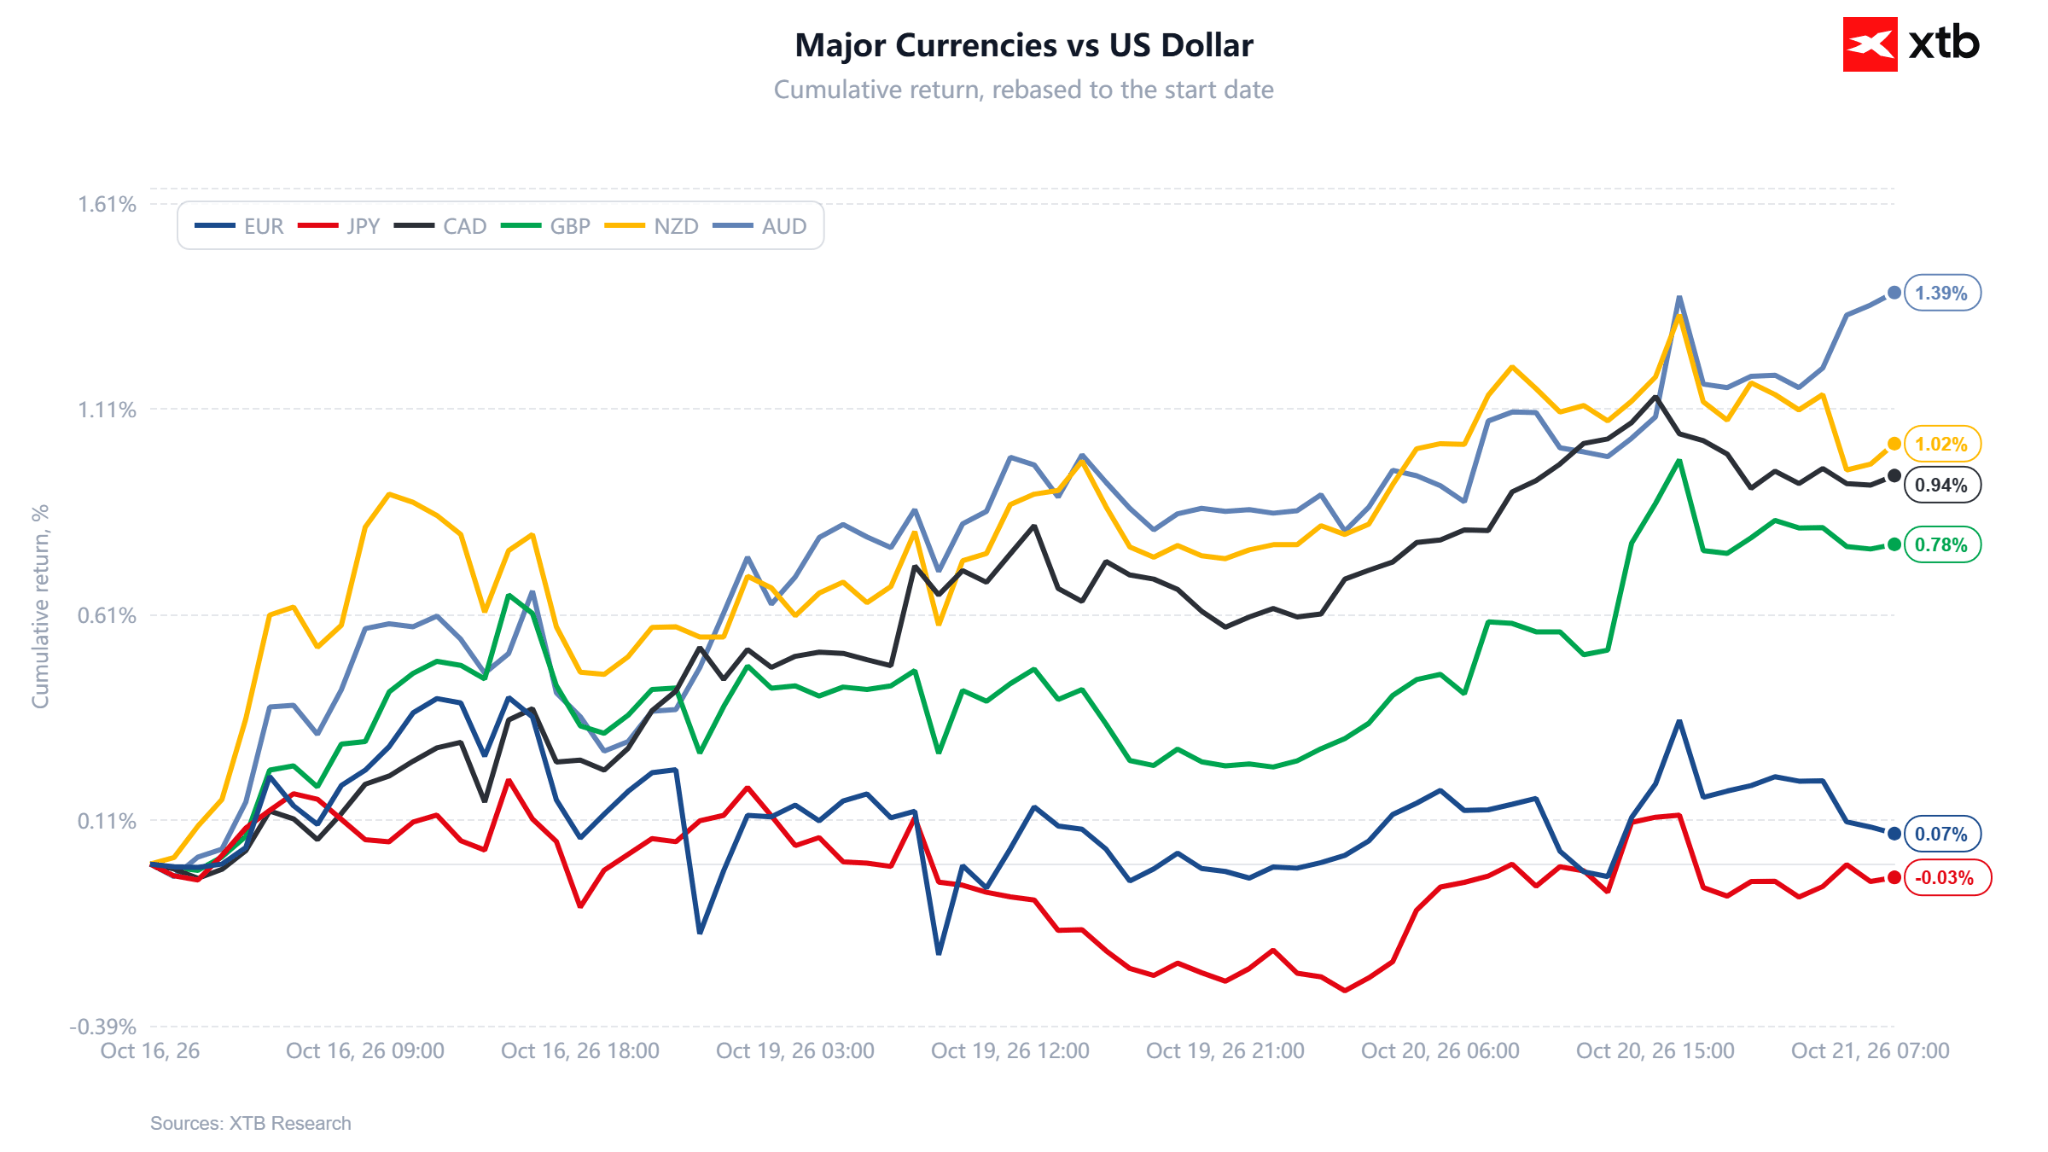
Hawkish signals from the RBA have supported the Australian dollar, allowing it to recover some of the losses suffered following last Thursday’s weaker labor market data. The AUD is the strongest-performing currency among the G10 today, having appreciated by 1.39% against the U.S. dollar since last Friday.
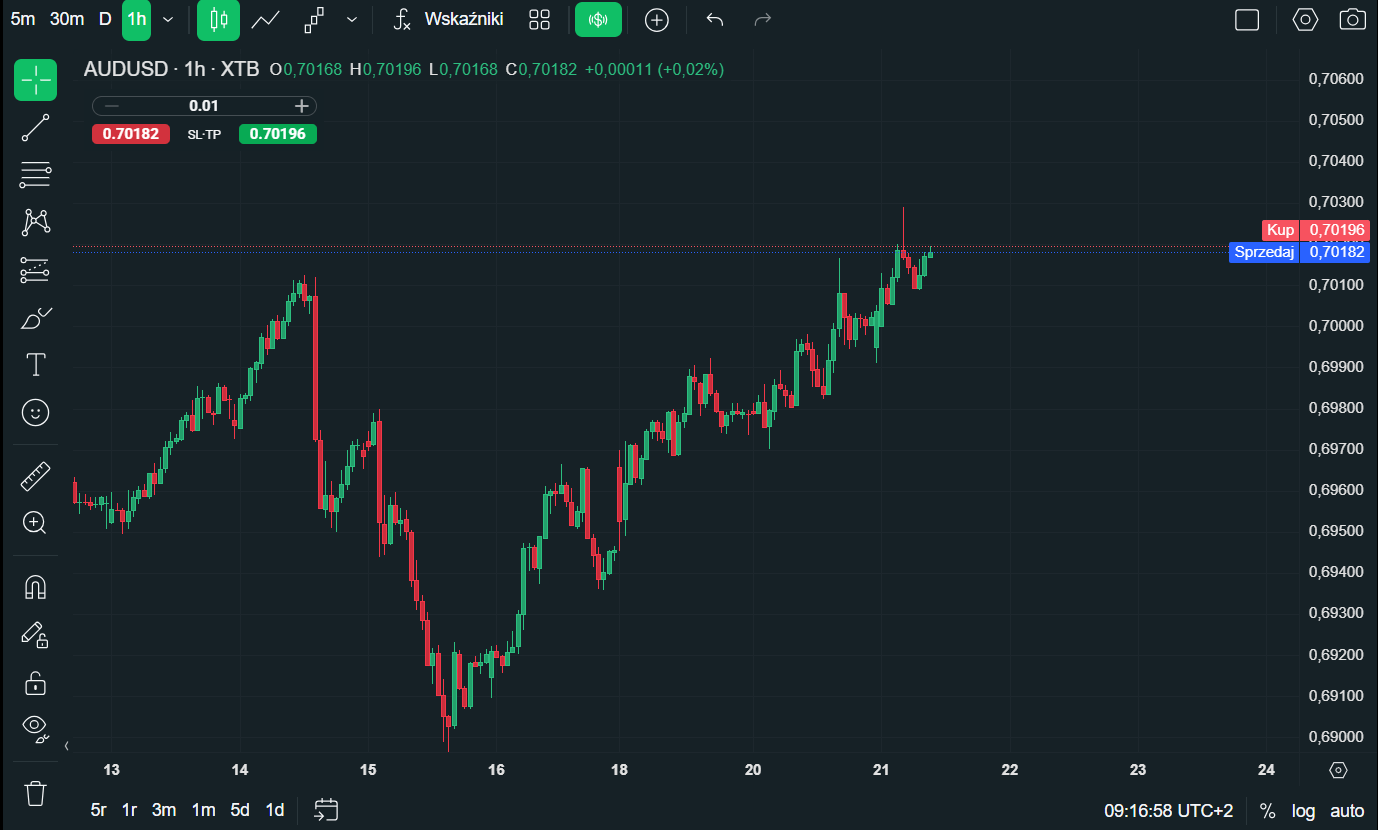
Today’s appreciation of the Australian currency has been further supported by renewed expectations of a November rate hike. The next move in AUDUSD will largely depend on the upcoming CPI data scheduled for late October.



Daily Summary: Buyers Refuse to Give In
US Natural gas extends declines 🔥📉



US OPEN: The wave of AI concerns is building again, oil returns near highs



Macro Calendar - UK Labor Market, ZEW Sentiment, and Wall Street Giants' Reports
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.