


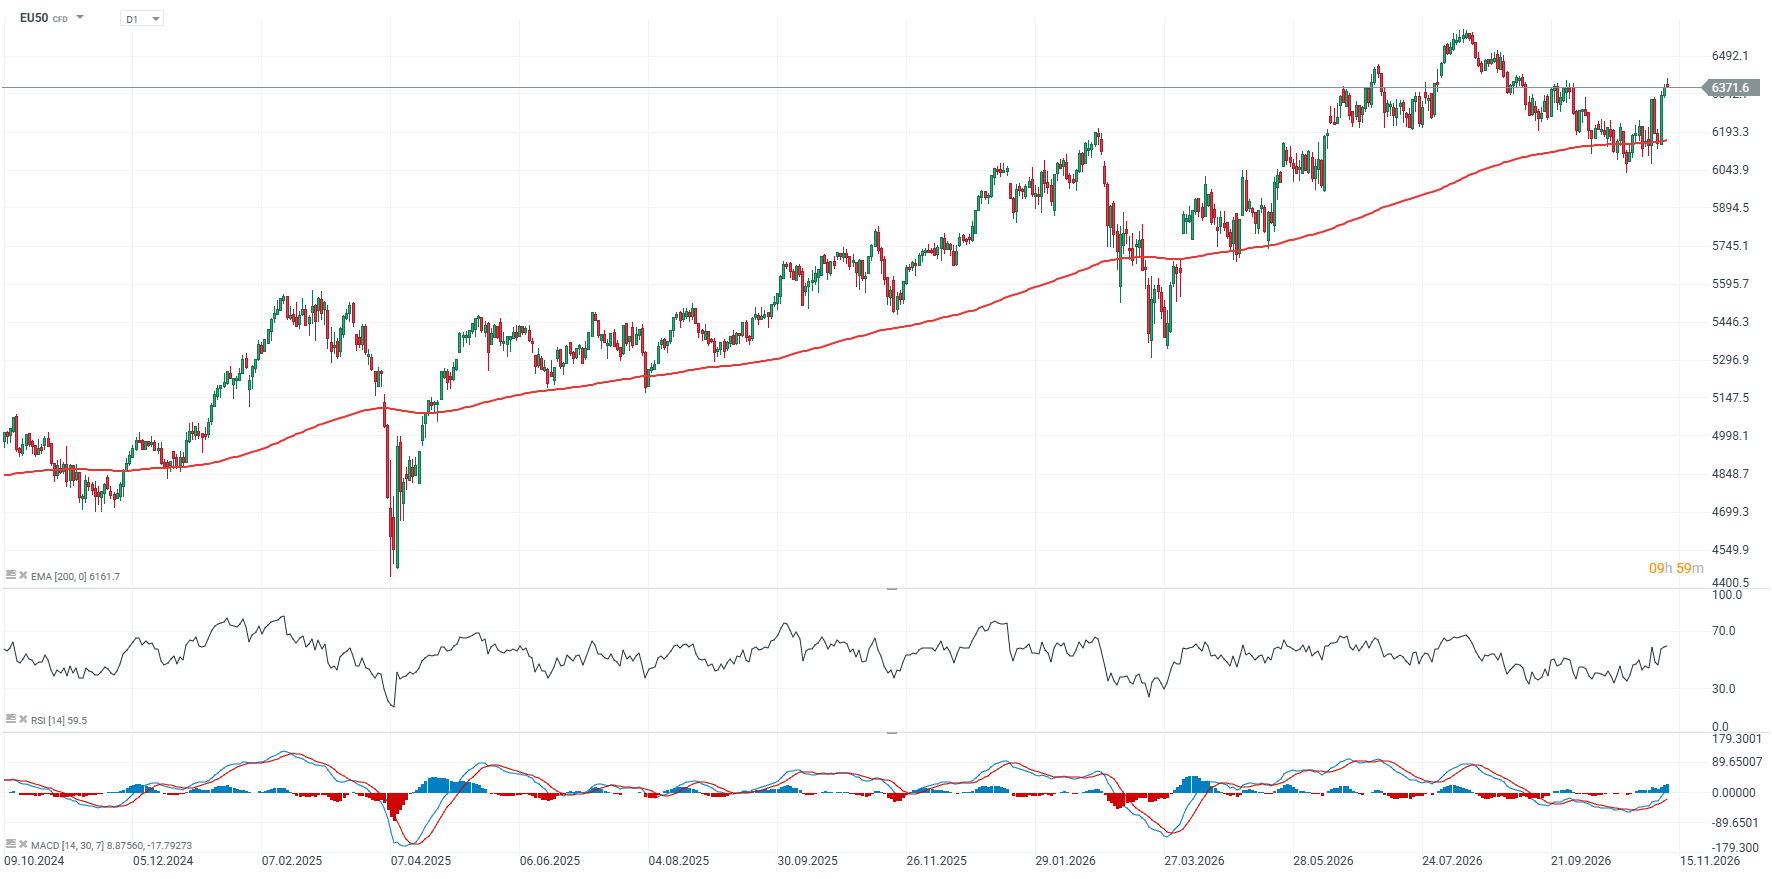
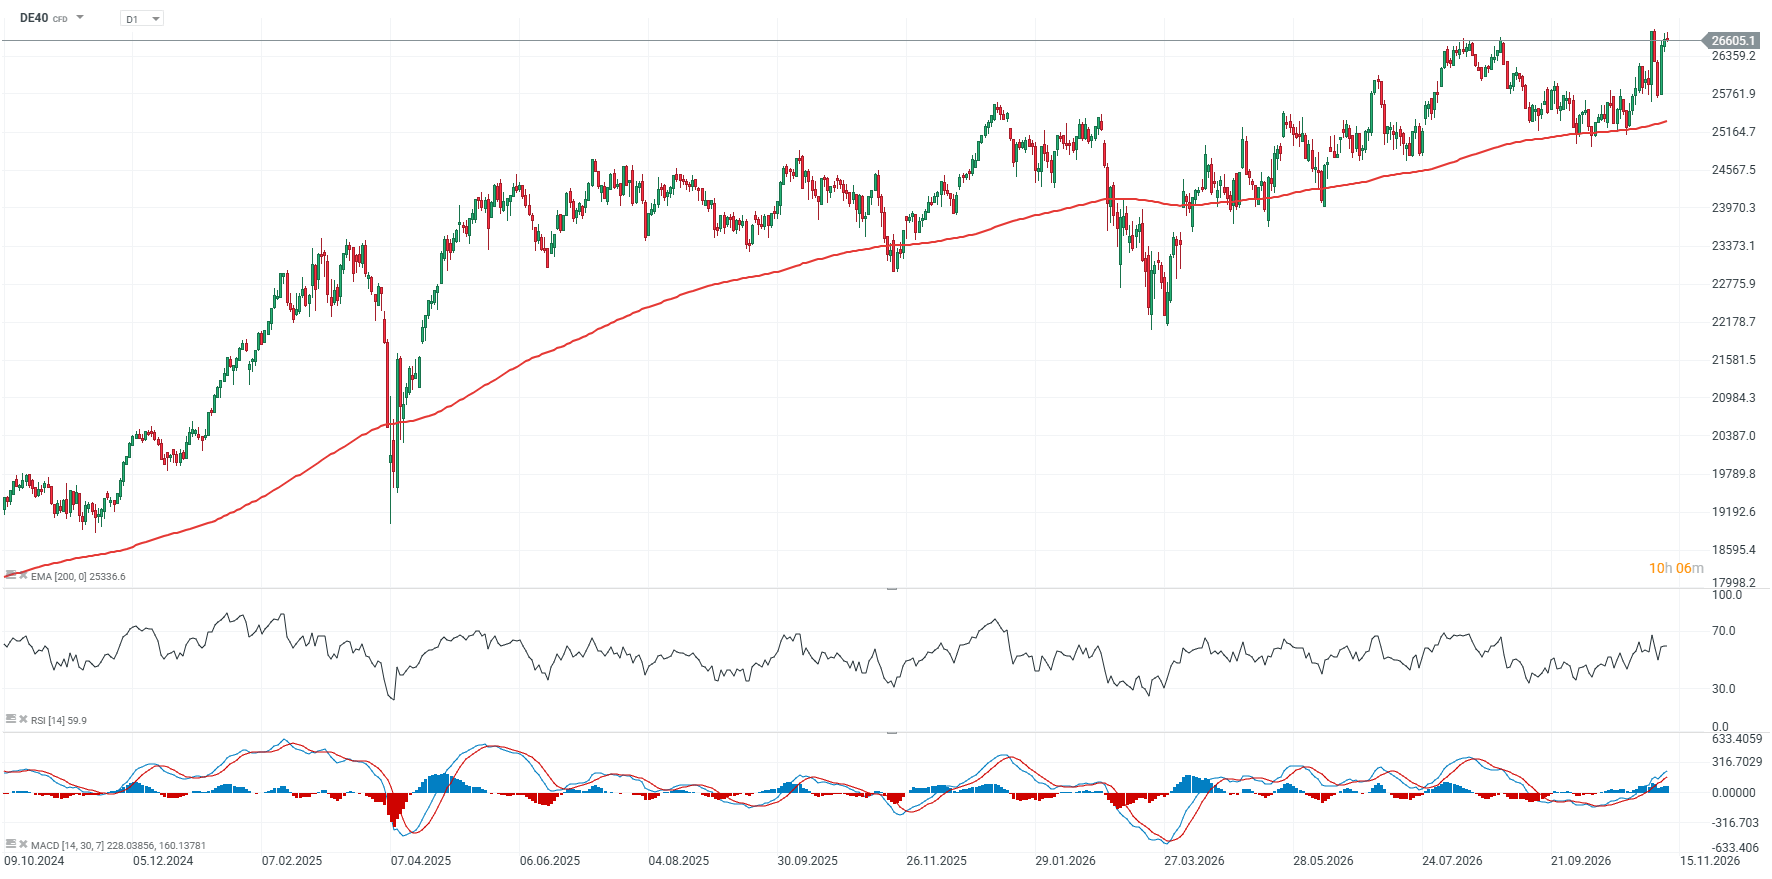
European indices continue to advance, with the STOXX 600 approaching record highs on the back of strong performance in technology shares and corporate earnings. The DAX is gaining around 0.9%, the CAC 40 is up 0.7%, while the FTSE 100 rises 0.8%, additionally supported by a rebound in oil prices. Positive sentiment persists despite growing expectations of a more hawkish Fed following higher-than-expected US inflation.
-
Technology leads the gains: CoreWeave’s results supported sentiment toward AI infrastructure, with BE Semiconductor and ASM International rising more than 4%, while ASML and STMicroelectronics gain over 3%.
-
Earnings season supports the market: Q3 reports are improving investors’ assessment of European corporate fundamentals despite higher bond yields and pressure from the cost of capital.
-
The Fed remains the key risk: higher US inflation has increased expectations of a December rate hike, which could weigh on growth-stock valuations.
-
Oil rebounds from two-month lows: continued tensions in the Middle East and reports from the Strait of Hormuz are supporting the energy sector. Iran has indicated that it will not allow previously enriched uranium to be removed from the country and has threatened to attack US bases in the region in the event of a US strike.
-
Bitcoin is staging a modest rebound and remains around USD 74,000, while gold is rising and stabilizing above USD 4,000 per ounce, as EURUSD falls by more than 0.5%.
EU50, DE40 charts, D1 interval
 Source: XTB
 Source: XTB
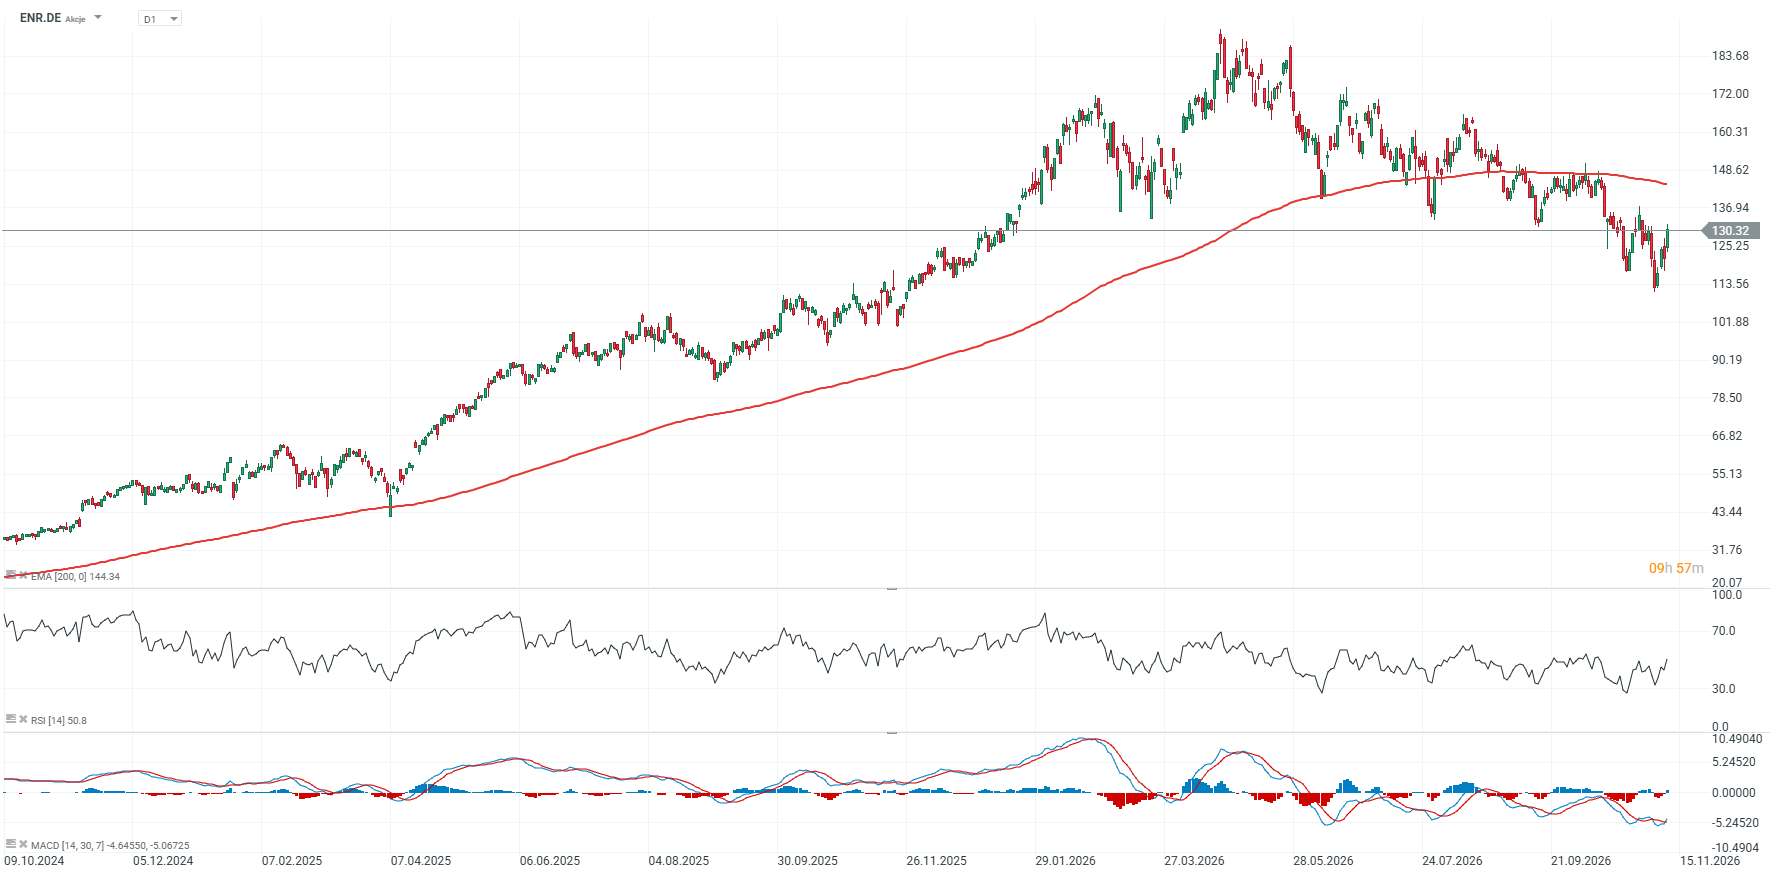
Siemens Energy after earnings: record year, strong backlog and ambitious 2030 targets
Siemens Energy ended fiscal 2026 with record results, while investors reacted particularly positively to the improvement in profitability, Siemens Gamesa’s return to breakeven and the new financial targets through 2030. The company is benefiting from very strong demand for gas turbines, grid infrastructure and data-center solutions, which has translated into a record order backlog. Siemens Energy shares are up around 7–8% today, as strong results, a higher dividend and an expanded share buyback program outweighed a slightly weaker-than-consensus net profit outlook for 2027.
Key Q4 FY2026 figures:
-
revenue: EUR 12.8 billion, +21.5% y/y on a comparable basis;
-
orders: EUR 14.8 billion, +5.2% y/y;
-
profit before special items: EUR 1.54 billion vs EUR 471 million a year earlier;
-
net profit: EUR 1.36 billion vs EUR 236 million;
-
EPS: EUR 1.49 vs EUR 0.19;
-
backlog: a record EUR 164 billion.
2026 confirms the scale of business improvement
For the full year, comparable revenue increased by 15.5% to EUR 44.2 billion, while orders rose 18.8% to EUR 68.1 billion. Profit before special items more than doubled to EUR 5.49 billion, while the margin improved from 6.0% to 12.4%. Net profit reached EUR 4.13 billion, while free cash flow before tax increased to EUR 8.8 billion from EUR 4.7 billion a year earlier.
A particularly important development is the turnaround at Siemens Gamesa, which after years of restructuring delivered a full-year result before special items slightly above breakeven, compared with a loss of around EUR 1.4 billion a year earlier. At the same time, Gas Services and Grid Technologies remain the main growth engines, benefiting from the investment boom in power grids, rising electricity demand and the expansion of AI-related data centers. Data-center-related orders already account for around EUR 15 billion, or more than 9% of the total backlog.
Siemens Energy raises the bar through 2030
For 2027, the company expects comparable revenue growth of 14–16% and a margin before special items of 14–16%. By 2030, Siemens Energy is targeting a margin of 20–22%, implying further significant improvement in operating efficiency. The company is also proposing to raise the dividend to EUR 2.30 per share from EUR 0.70 and launch an additional share buyback of up to EUR 9 billion through the end of 2030.
The main risk remains execution against very ambitious margin targets and the sustainability of the Siemens Gamesa turnaround, although the record backlog provides the company with exceptionally strong visibility on future revenue.
 Source: XTB
Financial results and market reactions of European companies
E.ON
E.ON reported adjusted EBITDA of EUR 7.1 billion for the first nine months, broadly unchanged year over year, while adjusted net income rose 4% to EUR 2.2 billion. In Q3 alone, EBITDA came in at EUR 1.7 billion, in line with consensus, while adjusted net income of EUR 278 million slightly exceeded expectations of EUR 268 million. The company maintained its FY2026 guidance for EBITDA of EUR 9.4–9.6 billion and adjusted net income of EUR 2.7–2.9 billion, while continuing to increase infrastructure investment. The market reaction was muted, with shares down around 1.7–2%, as investors had expected, among other things, a more aggressive increase in investment plans. E.ON is one of Europe’s largest power-grid operators and energy suppliers, focused primarily on distribution, retail supply and energy infrastructure.
RWE
RWE generated adjusted EBITDA of EUR 4.6 billion in 9M 2026, up 35% y/y, adjusted net income of EUR 1.8 billion and EPS of EUR 2.52, up 42% y/y. The company maintained its full-year EBITDA range of EUR 5.75–6.35 billion but indicated that the result should come in closer to the upper end, mainly thanks to trading, wind power and Flexible Generation. The initial market reaction was positive, with shares gaining around 1%, although part of the advance was later pared. RWE is a German energy group focused primarily on wind, solar and gas generation, while also operating a large energy-trading business.
ABN AMRO
ABN AMRO reported Q3 net profit of EUR 940 million, up 52% y/y and well above consensus of around EUR 782 million, although part of the beat came from the one-off impact of the NIBC acquisition and reserve releases. Commercial NII increased 7% q/q to around EUR 1.8 billion, while the bank raised its full-year outlook for this metric to more than EUR 6.9 billion. The market reacted moderately positively, with shares up around 1%, as investors welcomed the strong NII but partly discounted the one-off nature of part of the profit. ABN AMRO is one of the largest banks in the Netherlands, operating in retail banking, corporate banking, private banking and corporate finance.
Poste Italiane
Poste Italiane is due to approve its 9M 2026 report today, but the official Q3 and 9M results presentation is scheduled for November 12, meaning that at the time of writing the full set of new figures was not yet publicly available. Consensus ahead of the release pointed to around EUR 3.32 billion in revenue, EUR 866 million in adjusted EBIT and around EUR 635 million in Q3 net profit. The stock has been trading close to flat today, ranging from a slight gain to around -0.5%, so it is too early to speak of a reliable reaction to the results themselves. Poste Italiane is an Italian postal and financial-services group combining mail and parcel delivery with banking, payments, insurance and savings-management services.
Swiss Life
Swiss Life increased premiums by 8% in local currencies to CHF 17.4 billion in the first nine months of 2026, while fee income also rose 8% to CHF 2.04 billion. Net new assets in third-party asset management amounted to CHF 8.5 billion, while direct investment income fell to CHF 2.96 billion from CHF 3.13 billion and the SST ratio declined to around 205%. Shares were down around 2–2.5%, suggesting that strong premium and fee growth was not enough to offset weaker investment income and elevated expectations after the previous share-price rally. Swiss Life is a Swiss insurance group specializing in life insurance, pension products, wealth management and asset management.
Brenntag
Brenntag increased Q3 sales to EUR 4.3 billion, operating gross profit to EUR 1.064 billion and operating EBITDA to EUR 385 million, up around 14.5% y/y on a comparable basis. EBITDA was nevertheless around 1% below Visible Alpha consensus, while both main divisions slightly missed expectations, although the company now expects FY EBITDA to come in near the upper end of its EUR 1.35–1.45 billion range. The market reaction was limited, with shares trading slightly higher as the improved outlook offset a modest earnings disappointment. Brenntag is a global distributor of chemicals and specialty ingredients, connecting producers with customers across industrial, pharmaceutical, food and other end markets.
voestalpine
voestalpine kept H1 2026/27 revenue broadly stable at around EUR 7.7 billion, while EBITDA rose 17% to EUR 846 million, EBIT increased 36% to EUR 470 million and net profit advanced by around 46% to EUR 290 million. However, around EUR 100 million of the improvement came from one-off effects, while the company cut the upper end of its full-year EBITDA guidance from EUR 1.85 billion to EUR 1.70 billion due to higher energy and logistics costs and a weaker project environment. Shares fell around 3.2%, as the market focused mainly on the lower outlook rather than the historical improvement in earnings. voestalpine is an Austrian industrial group producing high-quality steel and components for the automotive, railway, aerospace, energy and machinery sectors.
Snam
Snam increased 9M revenue by 10.8% to around EUR 3.04 billion, EBITDA by 10.6% to roughly EUR 2.4 billion and net profit by 4% to EUR 1.11 billion. Investments rose from EUR 1.76 billion to EUR 2.31 billion, while the company maintained its full-year targets and increased its interim dividend by 4% to EUR 0.1257 per share. The market reaction was broadly neutral, with shares trading around 0.2–0.3% below the previous close, suggesting that the solid report was largely expected. Snam is one of Europe’s largest gas-infrastructure operators, managing transmission networks, gas-storage facilities and LNG terminals.
Technoprobe
Technoprobe is due today to formally review revenue, EBITDA and its financial position for 9M 2026, but at the time of writing the full earnings release had not yet been made public. Market sentiment toward the company remains very strong after a phenomenal H1, when revenue rose 42% to EUR 464 million and EBITDA increased 94% to EUR 206 million, driven mainly by AI-related demand and semiconductor testing. Shares are up more than 6% today, although the move should not yet be attributed solely to today’s results, as expectations around FTSE MIB inclusion and strong demand from TSMC are also providing support. Technoprobe produces advanced probe cards used to test integrated circuits during semiconductor manufacturing, particularly in high-performance computing and AI applications.
De’Longhi
De’Longhi increased Q3 revenue by 7.7% to EUR 944.9 million, adjusted EBITDA by 15% to EUR 171.6 million and net profit by 19% to EUR 84.5 million. For the first nine months, sales rose 6.5% to EUR 2.62 billion and EBITDA increased 17% to EUR 455 million, while the company raised its full-year adjusted EBITDA guidance to EUR 685–705 million, mainly thanks to very strong performance in the professional coffee-machine segment. Shares gained around 3%, as both improving margins and the higher outlook were received positively by investors. De’Longhi is an Italian manufacturer of household appliances, best known for coffee machines, kitchen appliances and professional coffee systems.
Vestas Wind Systems
Vestas increased Q3 revenue by 6% y/y to EUR 5.68 billion, while EBIT before special items came in at EUR 483 million with a margin of 8.5%, compared with 7.8% a year earlier; EPS rose 21% to a record EUR 1.14. The problem was that revenue and EBIT both came in below expectations, while turbine orders fell 27% y/y to 3.4 GW alongside a narrowing of the full-year outlook. Shares initially fell by as much as around 9% before limiting losses to roughly 4%, as the market focused on weaker backlog momentum and the costs related to the blade issue at the He Dreiht project. Vestas is one of the world’s largest wind-turbine manufacturers and a major provider of servicing solutions for onshore and offshore wind farms.
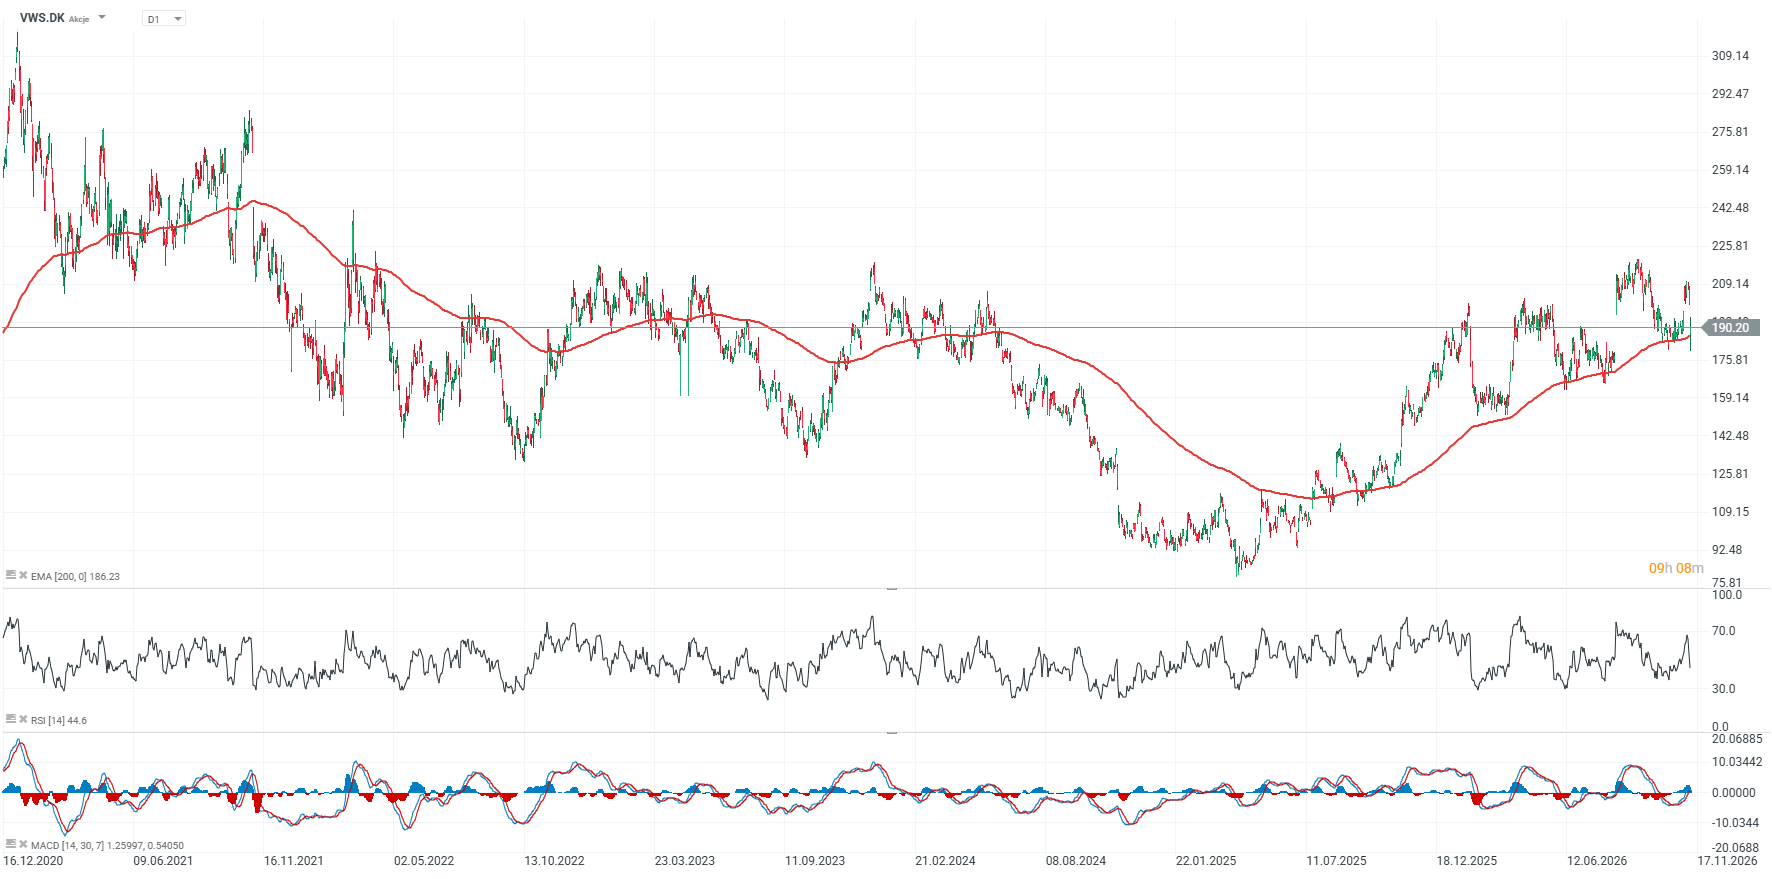 Source: xStation5


Nvidia shares suffer their biggest drop since 2025 🚩 What’s next for the AI giant?

Chart of the day 🚩 Cocoa sell-off continues. Record ICE inventories and index rebalancing in focus (11.11.2026)


📈 US500 continues its rebound


Economic calendar: European earnings season in focus amid light macro calendar (11.11.2026)
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.