


The US100 is regaining some ground today following its recent ‘slump’ and is up 1.02 per cent, continuing a rebound driven by semiconductor companies. The SOX index is rising for the third consecutive session (+3.2 per cent) after several difficult weeks. The catalyst remains the artificial intelligence sector: after Anthropic filed for a potentially record-breaking IPO on the Nasdaq, a consortium of banks and Blackstone secured US$63 billion in financing for the acquisition of Broadcom’s technology by Anthropic — Broadcom itself is up nearly 4%, followed by AMD (+5.4%), Micron and Western Digital (+7.5%). Tesla is climbing by nearly 4% to its highest level in over three months.
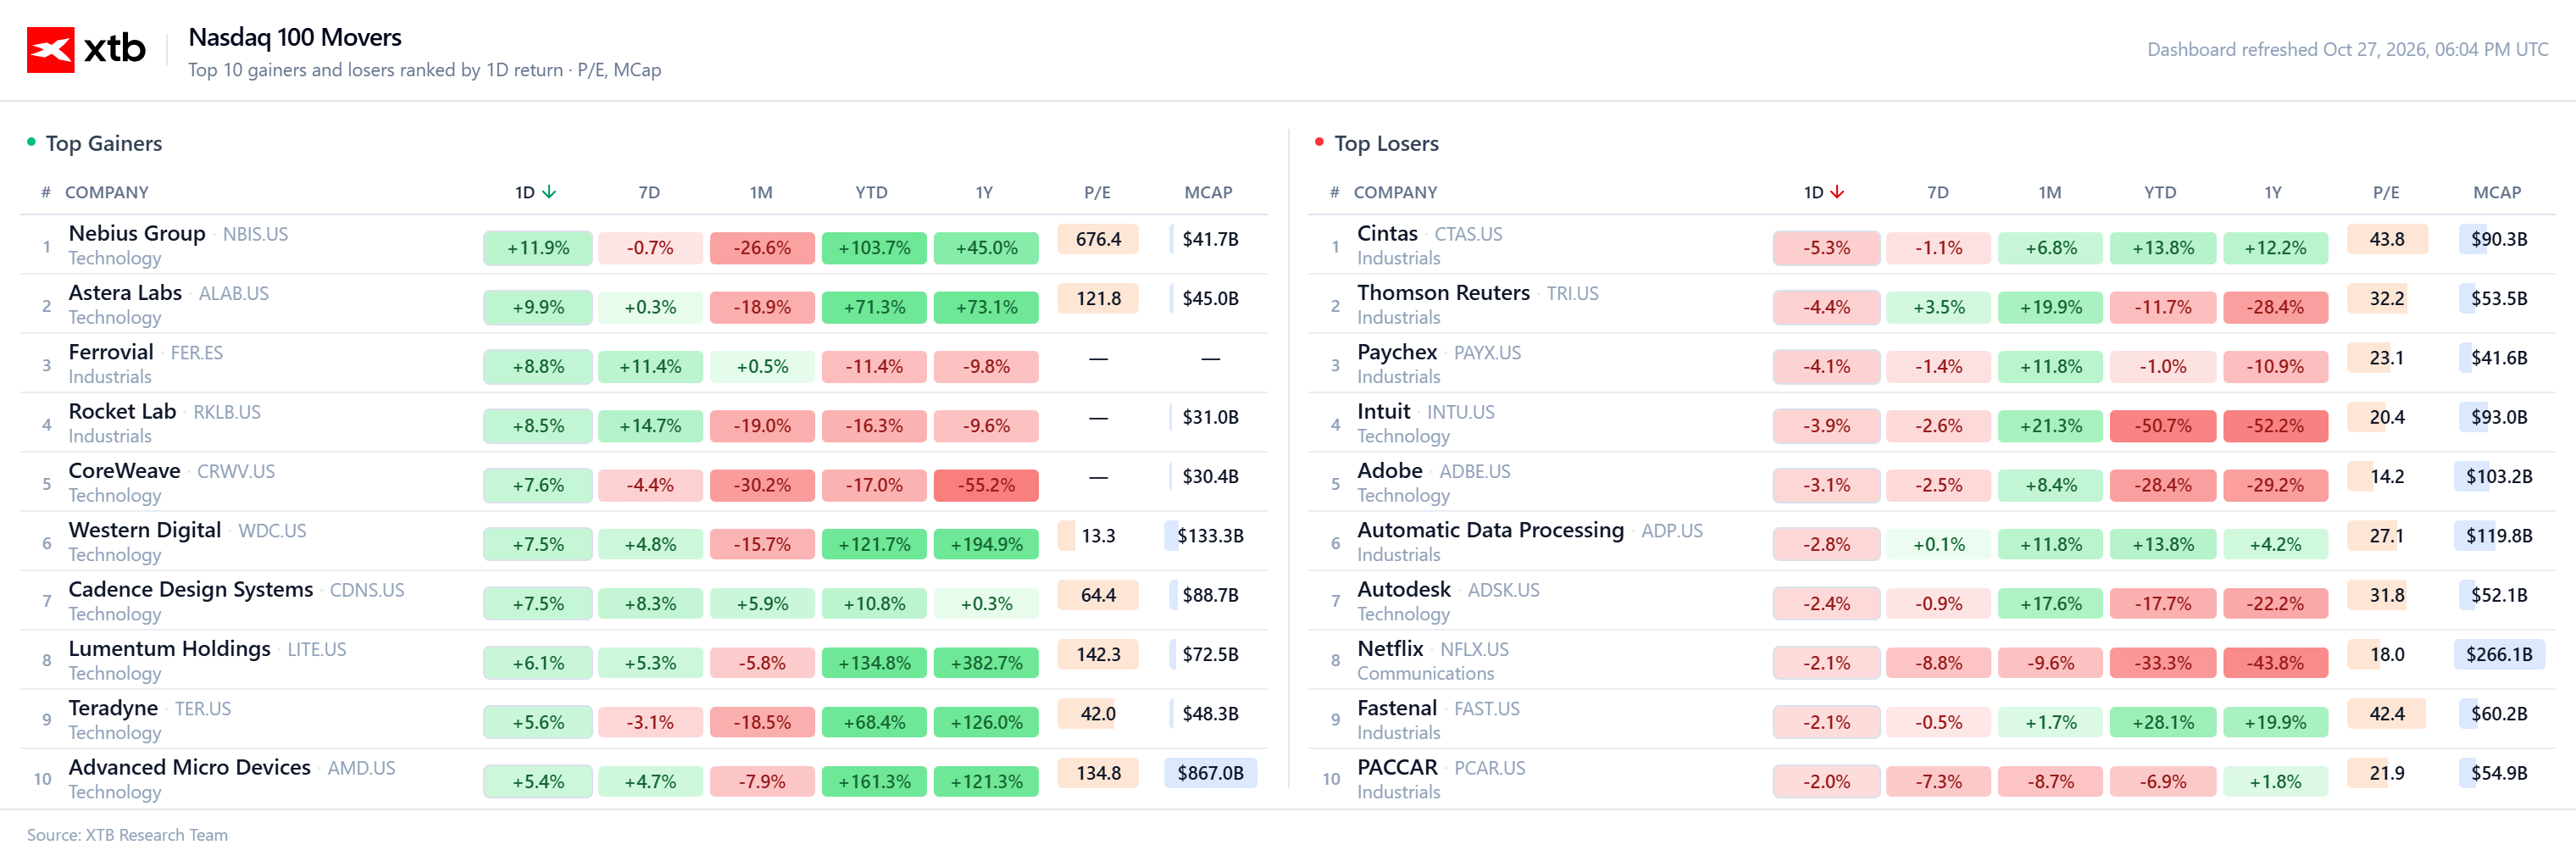
The companies showing the greatest volatility during today’s trading session. Source: XTB
Sentiment is also being buoyed by a second consecutive session of falling oil prices — Brent has slipped below US$114 following indications regarding the terms for ending the US–Iran conflict. In the background, the market is awaiting the Fed’s decision (Wednesday, with rates expected to remain unchanged) and the results of the hyperscalers/MAG7 companies — — Alphabet, Microsoft and Amazon — which are expected to confirm that multi-billion investments in AI are indeed translating into growth. Meta remains a sore point, falling by around 0.8 per cent after increasing its largest-ever share issue to $97.5 billion to fund AI expansion, fuelling questions about the sustainability of the debt-fuelled boom.
Technical analysis (US100, daily chart)
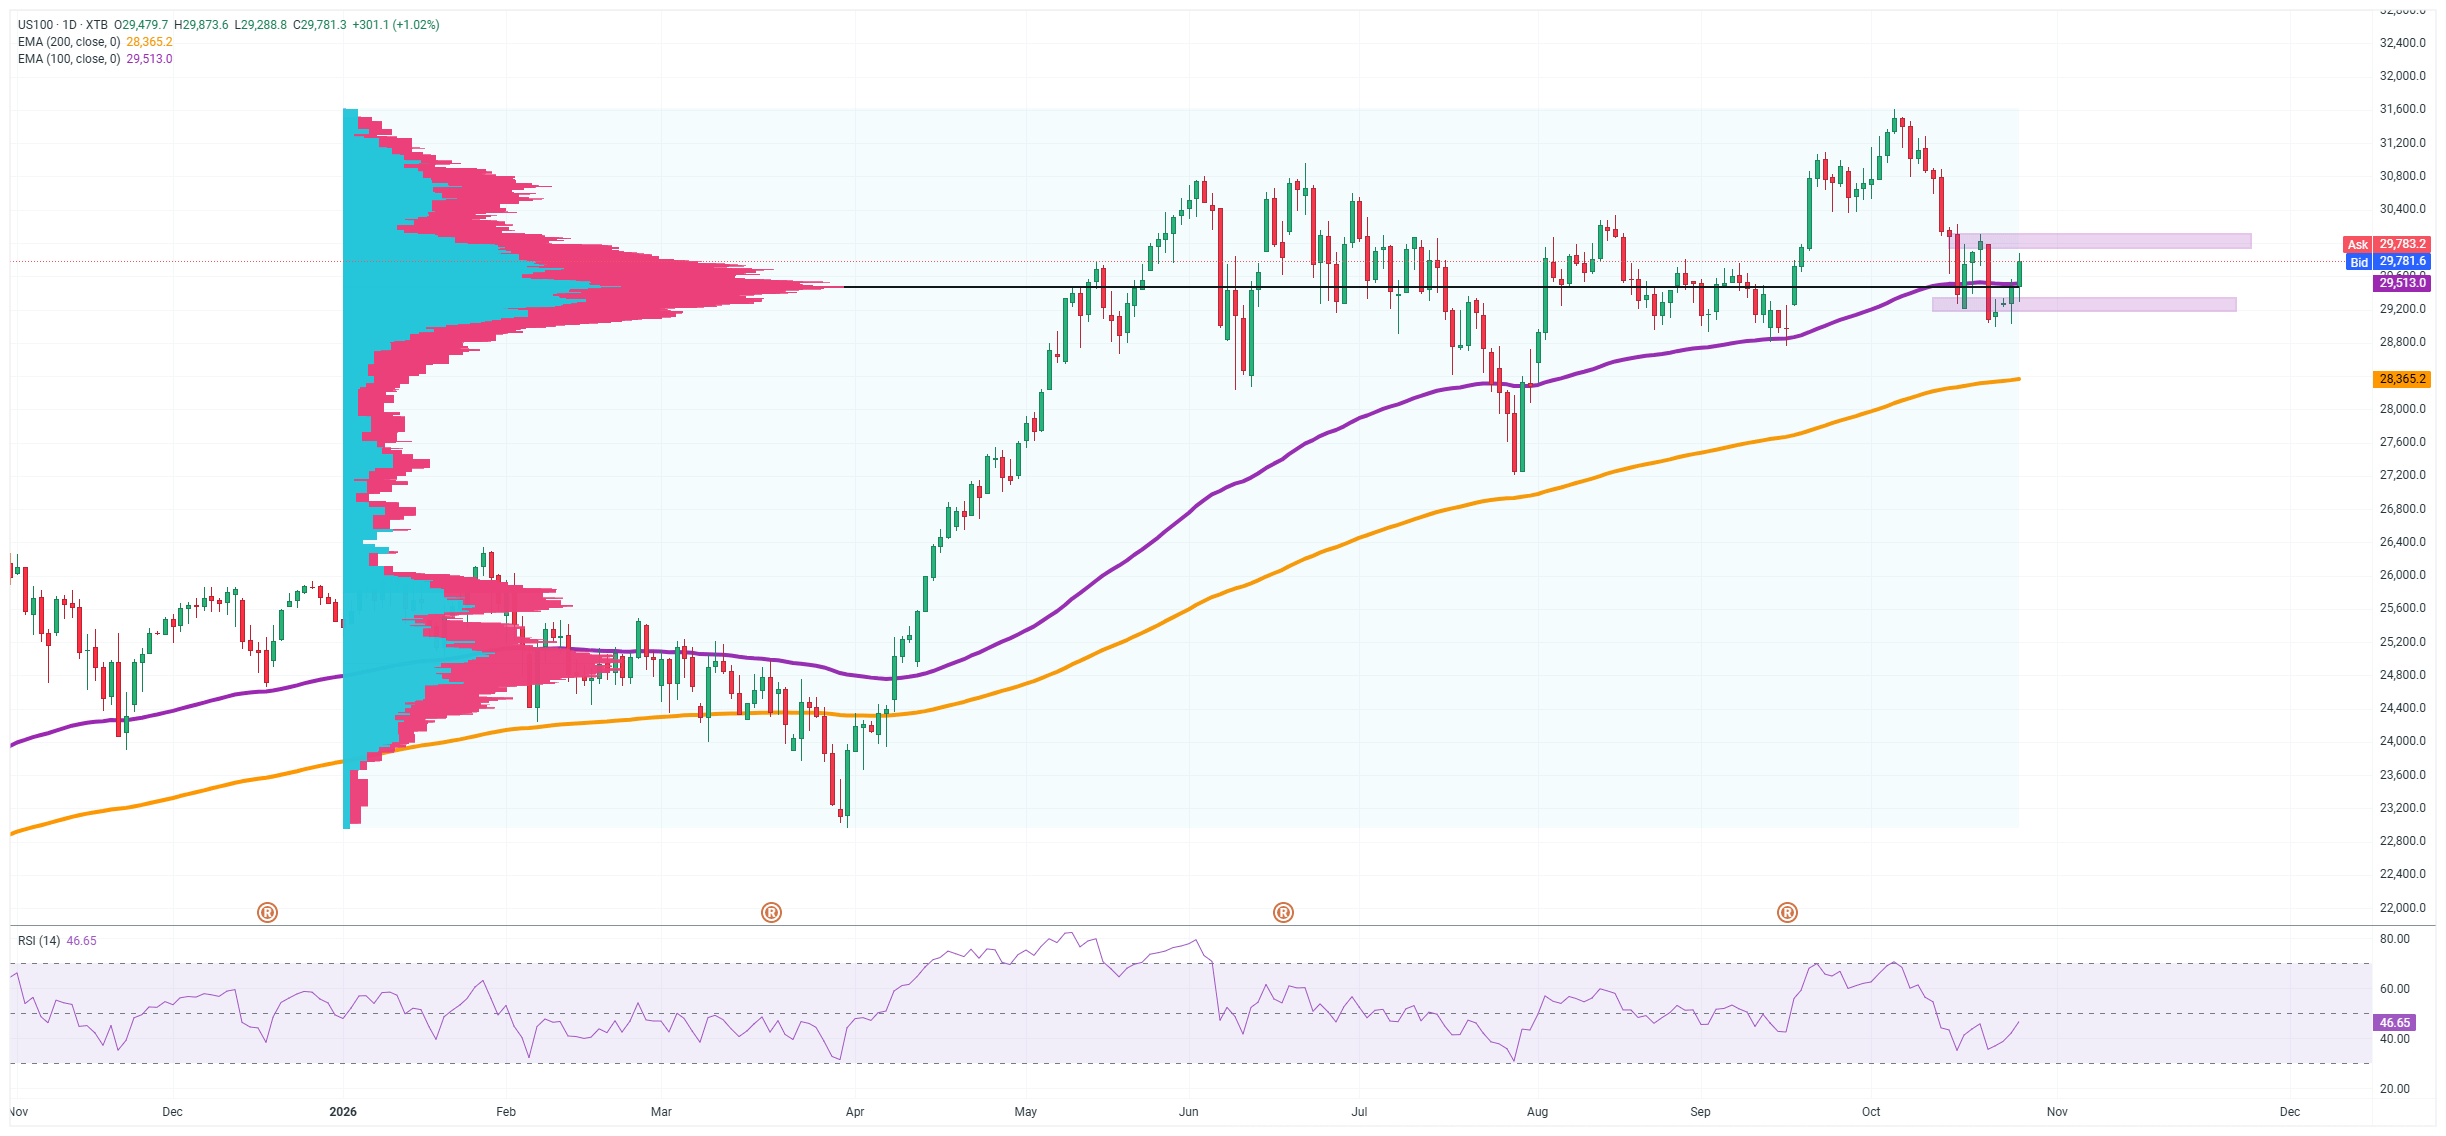
The bulls have recaptured the key 100-period EMA (29,513), which is once again acting as support — prices are closing above it, reversing the negative signal from the previous week when the price fell below this moving average. The rebound occurred precisely within the 29,000–29,500 point demand zone, which coincides with a dense volume profile, confirming its significance as the foundation of the recent consolidation.
The RSI (14) has rebounded to 46.65, moving out of the oversold zone towards the neutral midpoint — this leaves room for the upward movement to continue before overbought conditions set in. As long as the price remains above the 100-period EMA, the advantage has shifted back to the buyers.
The nearest resistance is the upper boundary of the supply zone in the 29,780–29,900 point range (today’s highs), and a break above this level would, in theory, open the way towards the October highs at 31,000–31,600 points. On the other hand, a hypothetical bearish scenario comes back into play should the index fall back below the EMA100 and drop below 29,000 points — in which case the EMA200 at 28,365 points could act as a support level.


Daily Summary: Wall Street Rises Ahead of Tomorrow's Fed Meeting💡



Market Wrap: Renewed confidence in AI drives stock market recovery (27.10.2026)


Gold Falls Below $4,000

Chart of the Day: USDJPY Caught in a Trap. Tokyo Intervention and a Hawkish BoJ Loom
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.