


For several weeks now, a proposal has been circulating in the US public debate, with varying intensity, to introduce a ban on diesel exports from the United States, ultimately for a period of around 90 days.
This step is meant, naturally, to reduce significant pressure on the US fuel market ahead of elections that are very important for the current administration.
Oil price on “Labor day” in the US [2000–2026]
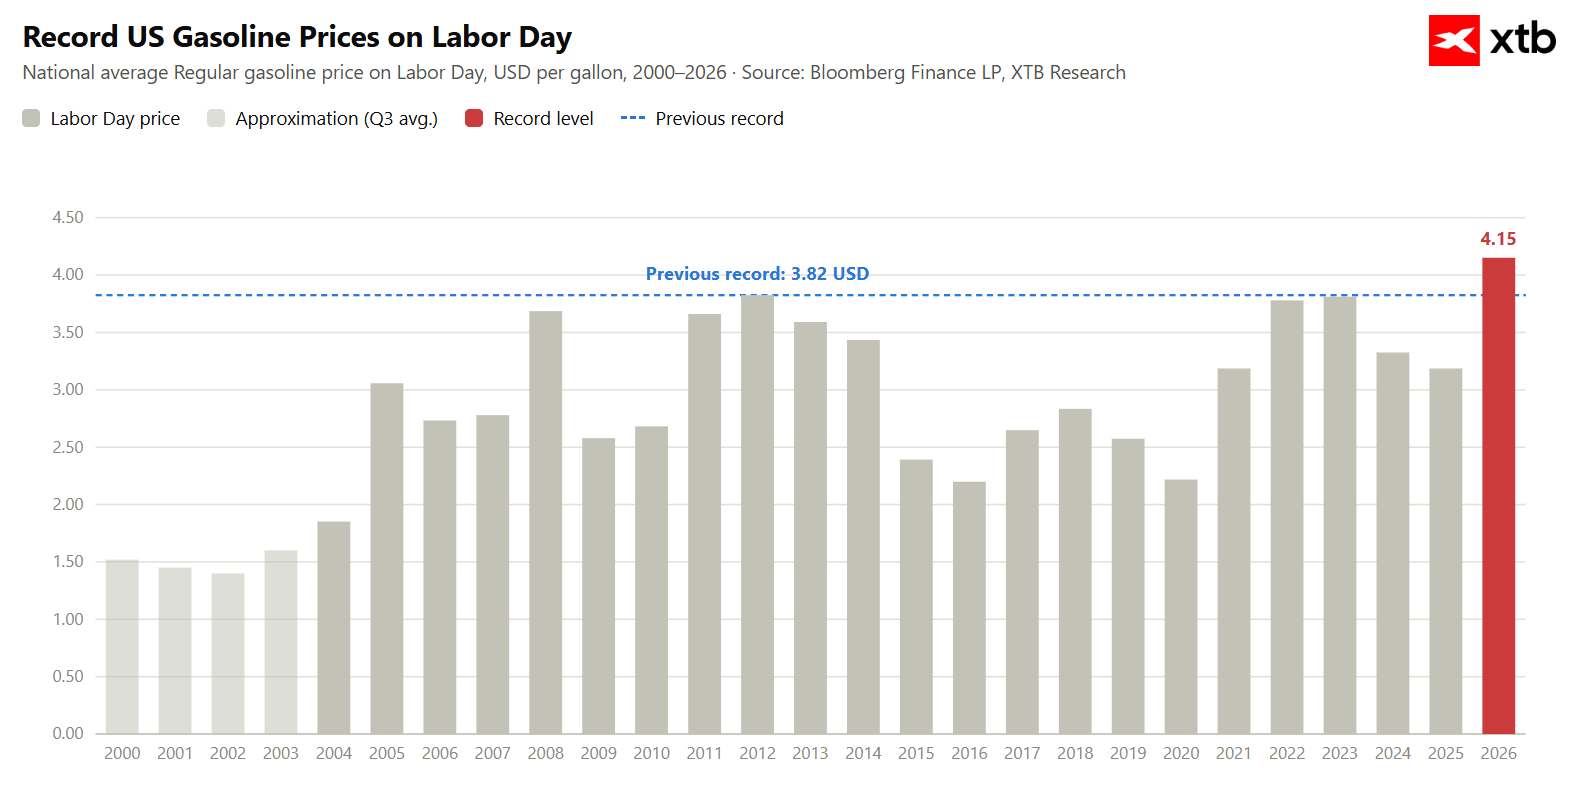
The situation is serious from the perspective of Republicans and the US due to the country’s extreme dependence on fuel consumption. Fuel prices are reaching all-time records, and isolated reports are appearing more and more often about physical shortages of certain petroleum products. With the midterm elections approaching, fuel prices are crucial, and despite the drastic and intrusive nature of this solution, many market participants do not rule it out.
Why diesel? The oil industry has a number of complex characteristics, and one of them is that the current deficit is not on the crude oil side, but on the refining capacity side. And among refined products, the biggest shortages are currently in the diesel market.
The war in the Persian Gulf has cut off several to more than a dozen percent of global refining capacity from the market (depending on the product). Supply pressure is also present in Russia. Last year, Russia accounted for about 5% of global supply of this type of fuel. A campaign of strikes on
Russia’s refining infrastructure, increasing in scale and effectiveness, has taken a large part of its export capacity out of use.
The shortage of this fuel is particularly problematic in the context of the harvest season. Despite the fact that Donald Trump spoke favorably about such a solution, it remains unlikely, and other representatives of the administration are even denying the possibility of implementing such a ban.
However, assuming the worst-case scenario, does it put Europe in as bad a position as many commentators suggest?
Oil transit through the Strait of Hormuz according to HormuzTracker.com
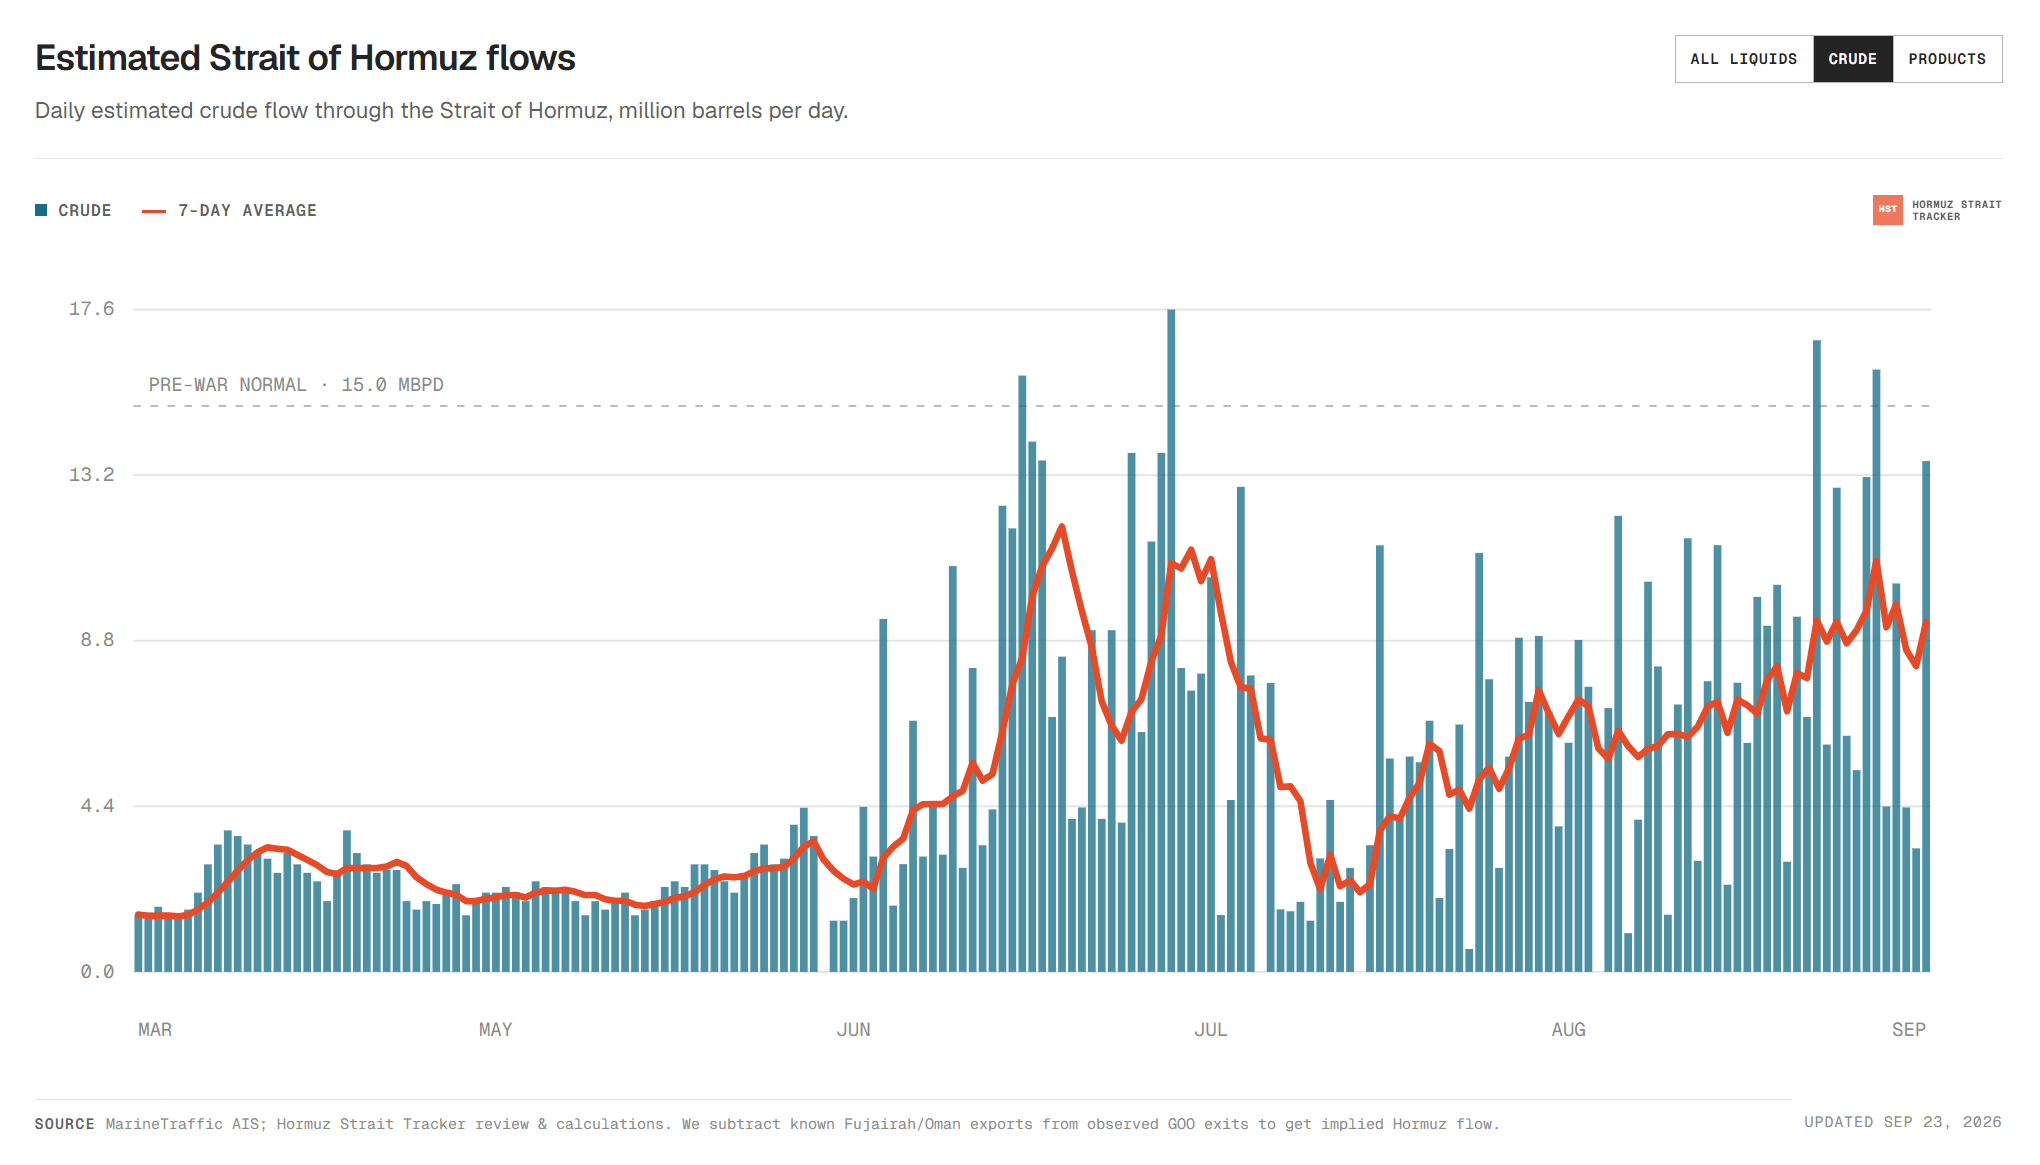
It should be emphasized that the shortage is currently on the refining side, not the extraction side. Strategic crude oil reserves released from inventories since the beginning of the conflict have cushioned a large part of the shortfall. For some time now, however, more and more data indicate that “blockade runners” are able to move out of the Strait of Hormuz an amount of crude sufficient to cover global demand. So the shortage is a matter of fuel, not crude oil.
The fuel market, however, both in Europe and globally, looks completely different.
Chart of GDP intensity versus oil consumption [2000–2025]
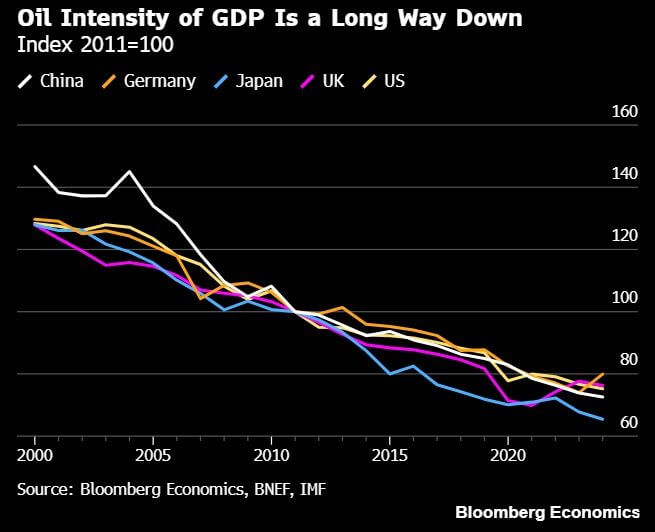
Source: Bloomberg Finance
Today, both the world and Europe have, by an order of magnitude, the lowest indicator of fuel-use intensity per unit of GDP generated. The global trend of moving away from fossil fuels, as a result of the war in the Gulf, will likely only accelerate.
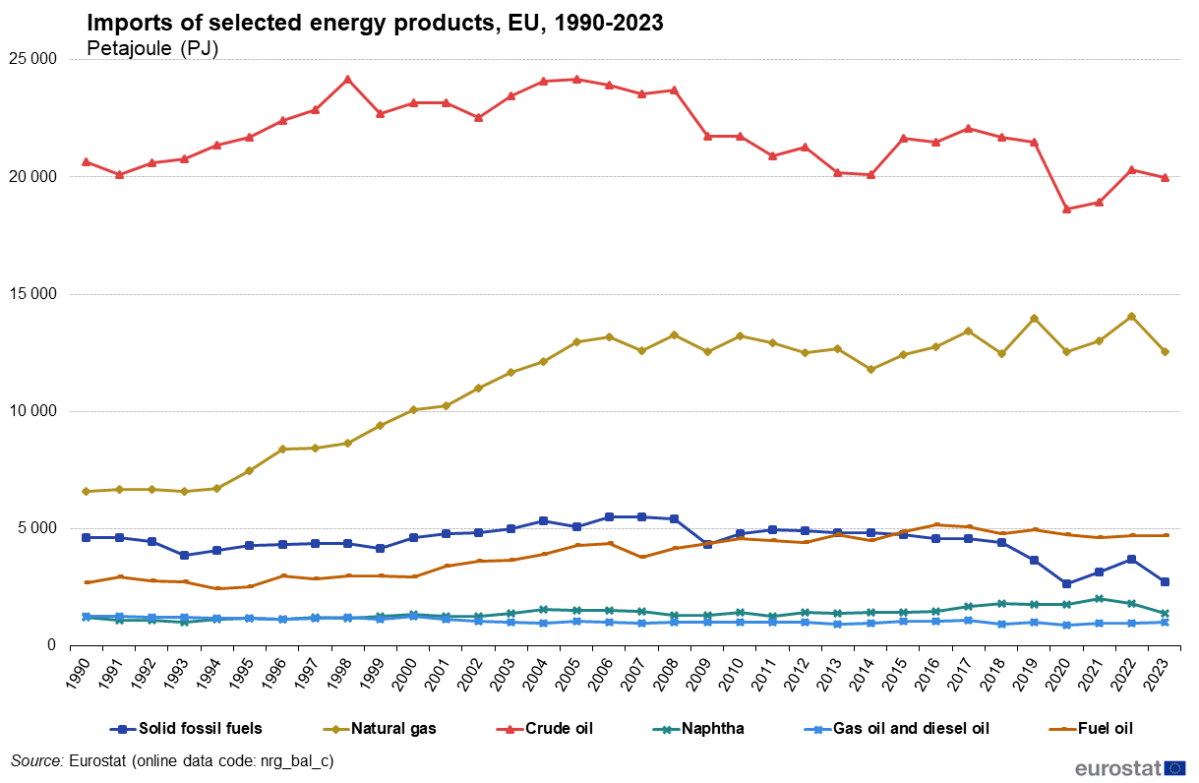
Chart of imports of raw materials and fuels into the EU [1997–2023]
Source: Eurostat
Europe’s biggest dependency in this respect is not crude oil or fuel, but natural gas, which, despite difficulties, still reaches Europe, among others, from Norway or the US.
Europe imports about 95% of its crude oil, but only about 10% of diesel fuel. When it comes to gasoline, Europe is a net exporter. Therefore, a hypothetical ban on diesel exports from the US would be a challenge, but not a catastrophe.
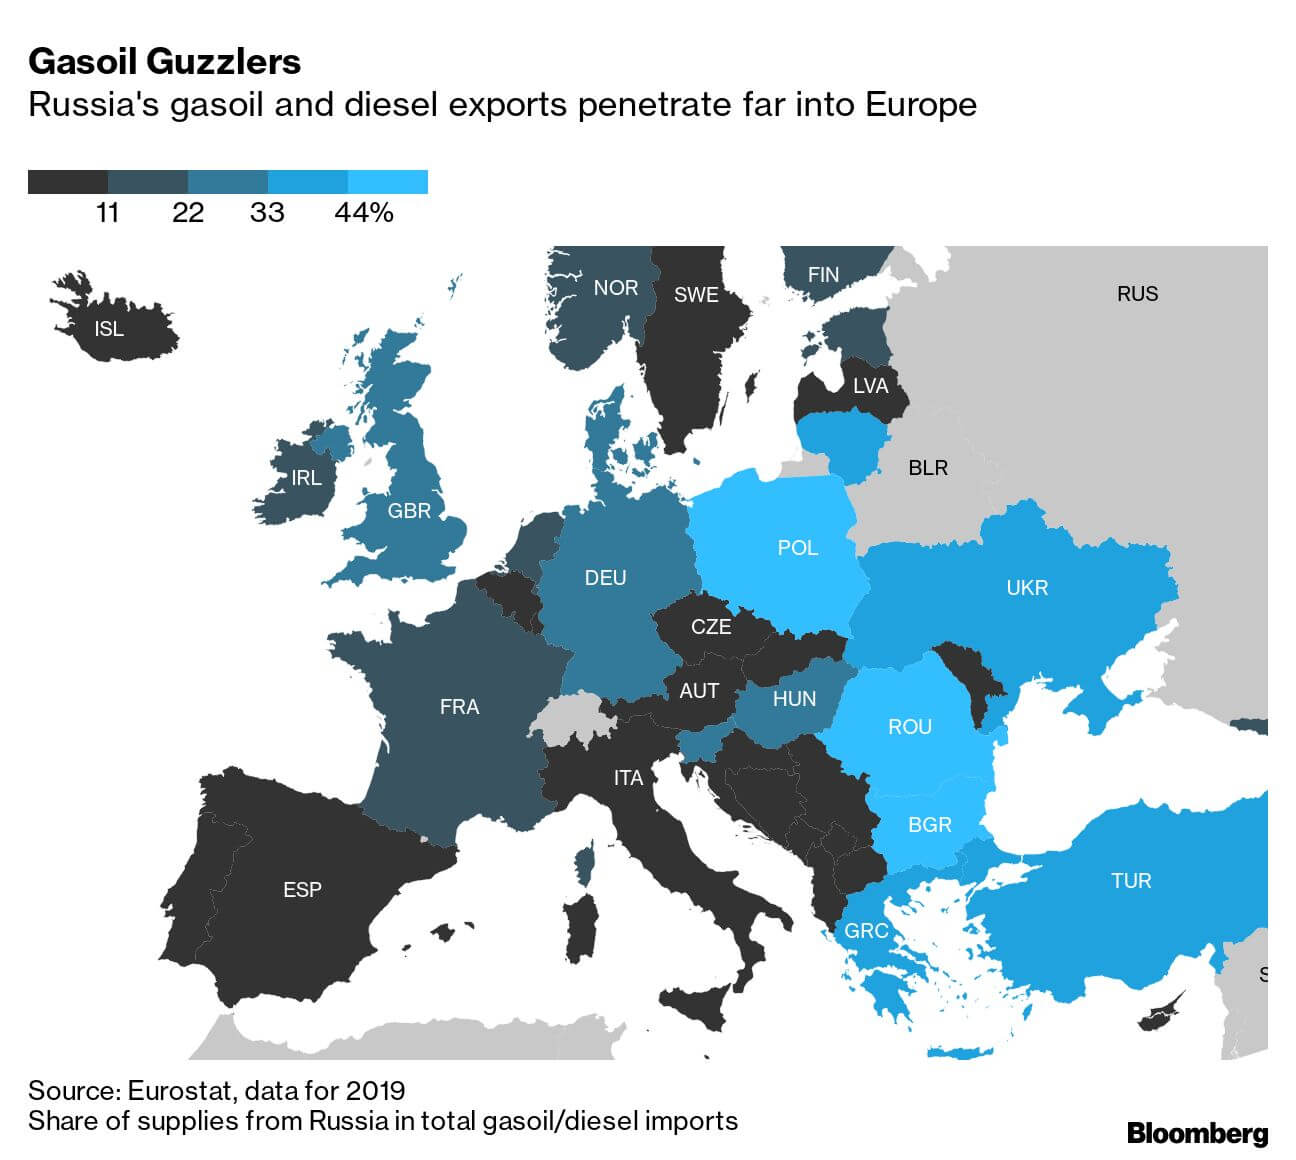
Imports of Russian diesel [2019]
Source: Bloomberg Finance LP
However, this challenge is not distributed evenly across the continent. Central and Eastern European countries may be more exposed to changes in prices and the supply balance, among other reasons due to major delays in meeting the assumptions of the EU’s environmental policy. As a result, this may lead to higher inflation in countries in the region, but shortages are not currently expected.
Kamil Szczepański
Financial Markets Analyst, XTB



Daily Summary: US dollar reaches new highs, Wall Street, gold and bitcoin fall (23.09.2026)

US Open: Nasdaq drops from the all-time high (23.09.2026)
BREAKING: Strong PMI indicators do not help the euro! EURUSD tests key 1.1400 level



🛢️WTI crude tests $90. Brent below $100
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.