


Rising oil prices and weak results from Lam Research are triggering another leg of the pullback in US stock indexes. At the open, US100 futures are down about 1.8%. Indexes with a smaller technology weighting are holding up better: US500 is down just under 1%, while US30 and US2000 are off around 0.6%.
- Energy commodities are back on the rise. On Wednesday there was a drone attack on the Shaybah oil field in Saudi Arabia. Production was not halted, but investors fear further strikes. Markets and regional countries are preparing for the possibility of another escalation wave between the US and Iran. Saudi Aramco instructed employees to leave its headquarters in Dhahran, and the US is reducing its diplomatic presence in Gulf countries. Oil is up more than 2%, taking Brent back above $108 per barrel.
- Gains are even stronger in natural gas futures. European contracts are up more than 4% on worries about further supply disruptions. US gas prices are also rising despite forecasts for warmer weather, additionally supported by contract rolling effects.
- The market is awaiting Anthropic’s S-1 prospectus filing for its IPO, expected as soon as Friday (tomorrow).
- More US polling data related to the midterm elections is coming in. Democrats have a clear lead in the race for the House, with an advantage of more than 8%. At this stage, that implies a gain of around 10 seats in the House.
- Despite higher oil prices, bond yields are posting a moderate decline. US 10-year yields are slipping toward 5.04%.
- After today’s session, Western Digital and Bloom Energy will report quarterly results. These reports should provide key clues about real demand for data storage infrastructure and power solutions for AI data centers. Gold production leader Newmont will also release results.
Company news
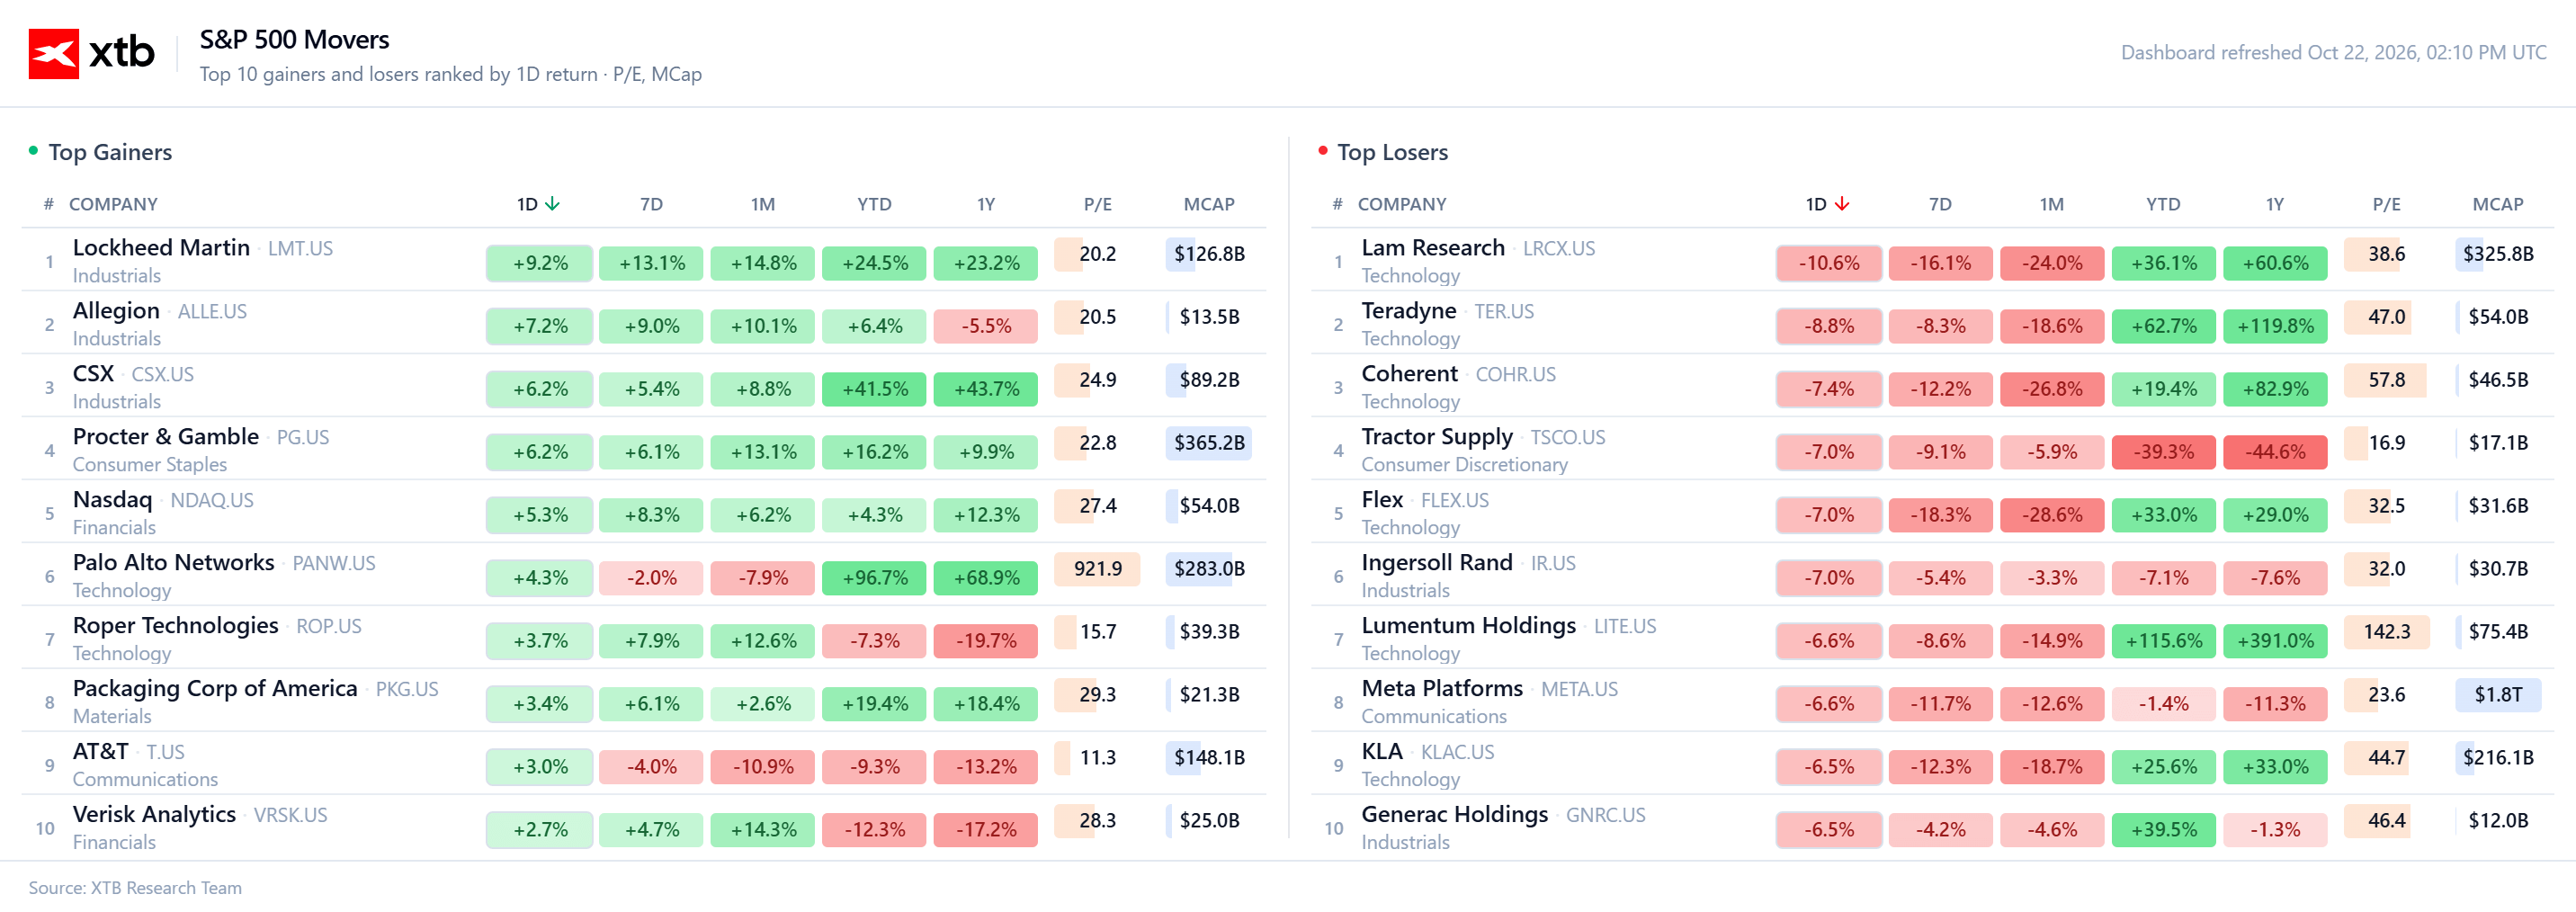
- Lam Research (LRCX.US): Despite posting over 50% year-over-year growth and a record margin, the stock is down about 8% after earnings. This reflects extremely high market expectations, as investors anticipated a much larger lift to forward guidance than the roughly 2% above consensus provided by management. Negative sentiment quickly spread across the market and is driving multi-percent losses for most companies in the sector.
- IBM (IBM.US): Although quarterly results beat expectations, the market is negative on the outlook for further growth, pointing to a bearish price impulse at the start of the session. Shares are down about 7%.
- Meta (META.US): The stock fell 6% to around $650. While last quarter’s results beat consensus and Mark Zuckerberg spoke enthusiastically about monetization potential for the “Muse” assistant, investors were unsettled by another increase in CAPEX guidance.
- Tesla (TSLA.US): Shares are down about 3%. Sentiment was hurt by trimmed CAPEX plans while keeping high operating costs tied to robotics and autonomous systems development.
- Lockheed Martin (LHM.US): The defense company reported results well above consensus. Higher sales in missile systems and aeronautics, along with guidance raised above consensus, are supporting a share price gain of over 4%.
- P&G (PG.US): The stock is up about 3% at the open. The move is supported by better-than-expected quarterly results (EPS $2.00 vs $1.88) and an increase in the company’s sales growth forecast.
- Spotify (SPOT.US): Shares of the streaming platform are up about 6.0%. Investors welcomed strong subscriber growth and updated guidance pointing to further, sustained operating margin expansion.
US100 technical analysis
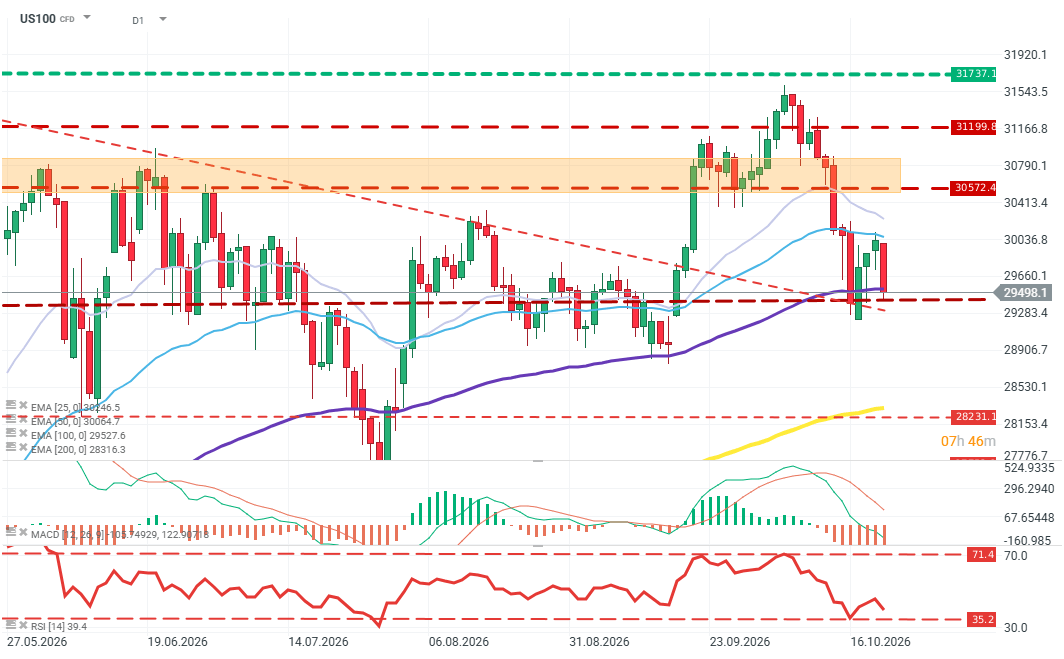
The US100 technology benchmark has reached a critical technical area, sliding toward 29,520 points. From a medium-term perspective, today’s drop is pushing the contract to test the converging EMA50 and EMA100. To maintain the broader uptrend, buyers need to defend support defined by this moving-average cluster around 29,500. Negating bearish pressure would require a return above the psychological 30,000 resistance, which would open the way for another attempt at the highs. Conversely, a sustained break below the moving-average cluster would confirm a deeper correction and could open the path toward a decline to the local low near 28,800. Source: xStation5
Macroeconomic data
- The US Leading Index reading (for September) showed no change, versus expectations for a 0.1% decline.
- At 16:30, the EIA will publish weekly changes in US natural gas inventories. The market currently prices in an increase of 78 bcf.



Market Wrap: "Decent" results are not enough – tech stocks fall further; oil highest since May (22.10.2026)


Lam Research: Strong Numbers, Limited Upside Surprise

US100 drops 1.8% 🚨

Economic Calendar: Markets Await Reports from Procter & Gamble and Western Digital 💡
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.