

- Investors turn risk averse as crude oil continues to rise (Brent above 111 USD per barrell).
- Lockheed Martin shares rise 7.8% following an upgrade to full-year earnings guidance and strong missile segment profits.
- SpaceX plans to acquire base stations for a mobile network, driving Crown Castle shares up by 11%
The opening of Friday's session on the New York stock exchange is taking place in an atmosphere of pronounced risk aversion and a flight of capital toward safe havens. Market sentiment remains under pressure from the ongoing conflict in the Middle East, which has driven up energy commodity prices, fuelling concerns over a return of inflationary pressure ahead of the upcoming US congressional elections.
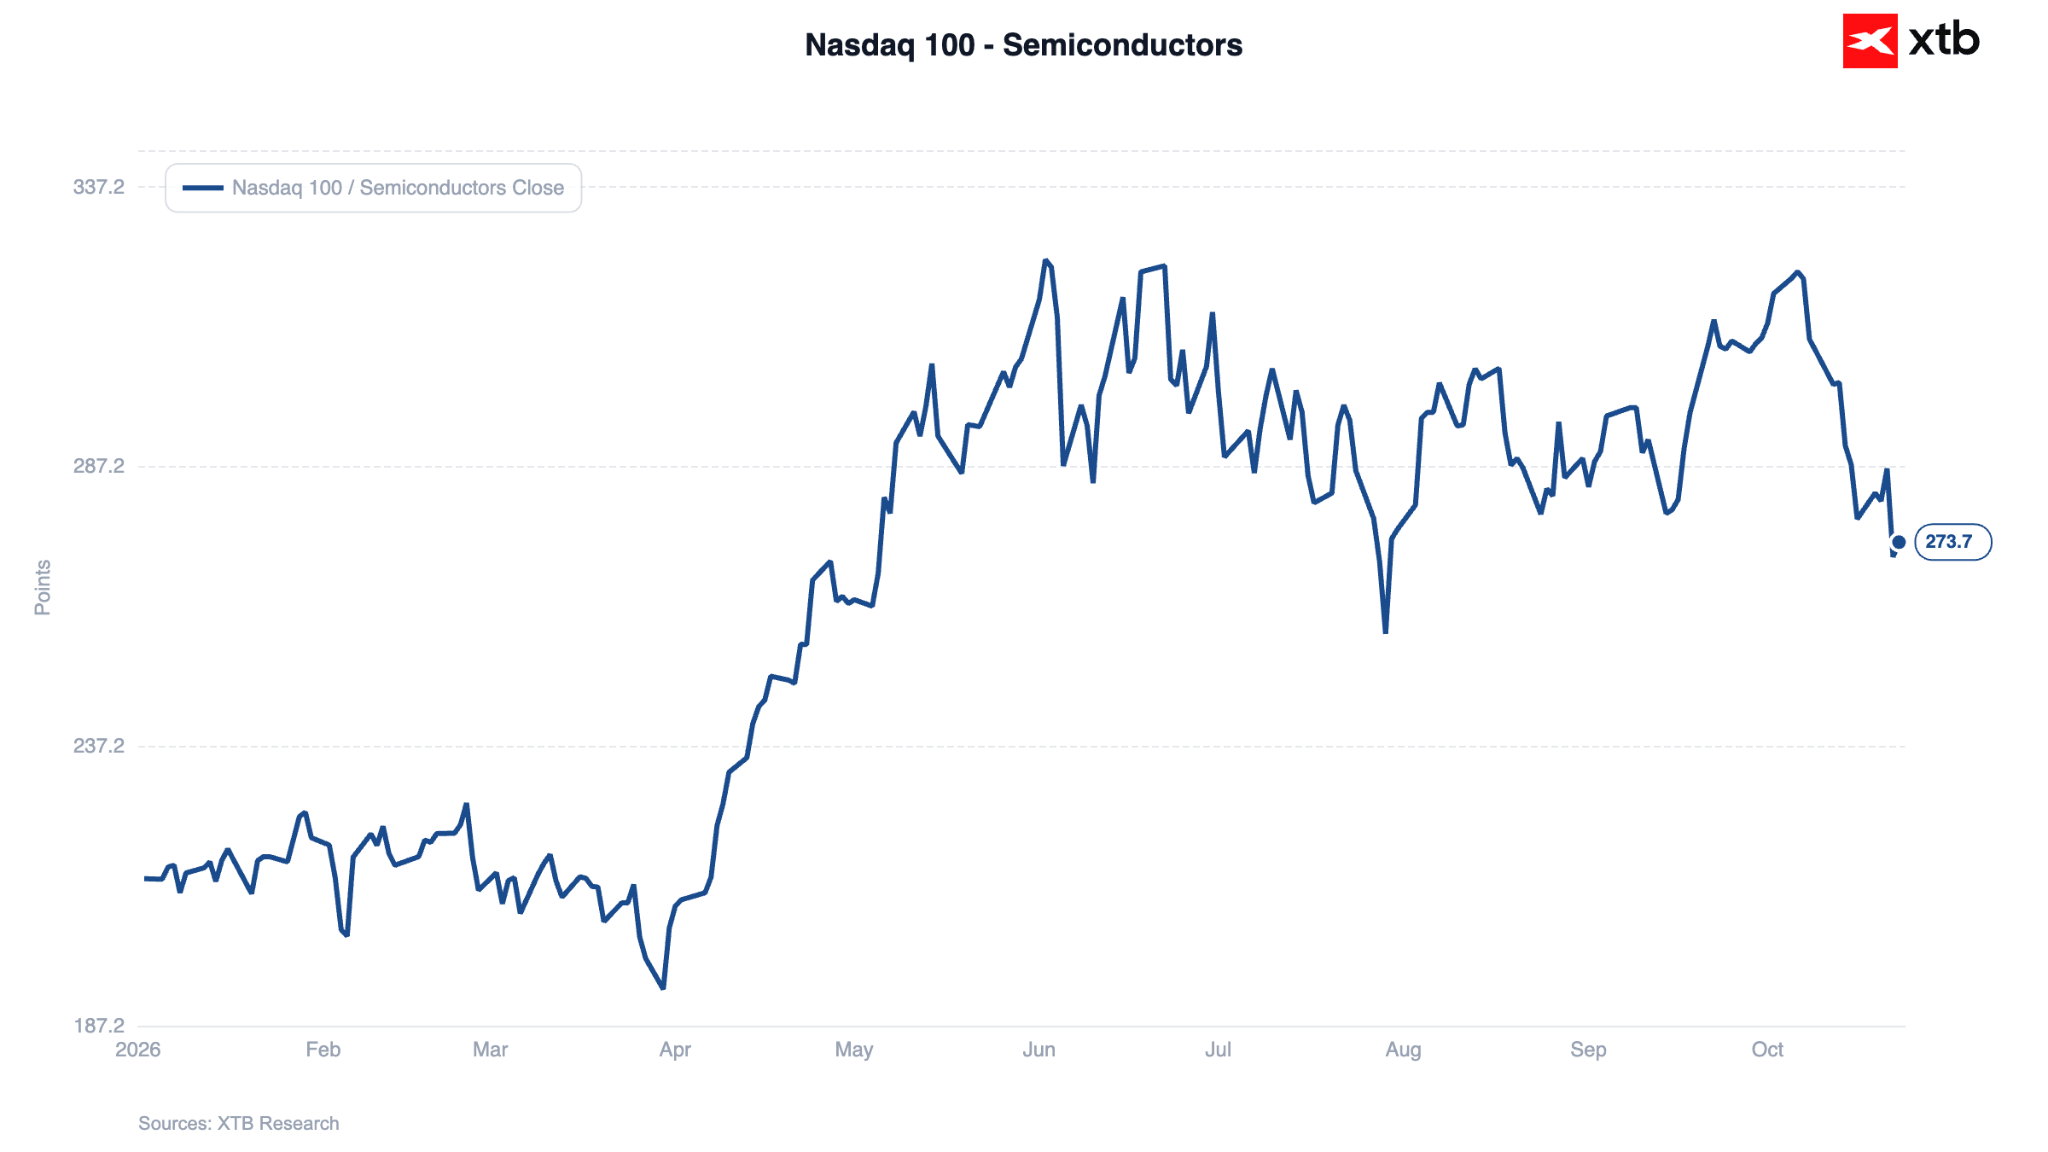
At the same time, institutional investors continue to reassess valuations of beneficiaries of the artificial intelligence revolution, shifting liquidity from the semiconductor sector to defensive industries such as consumer staples and public utilities.
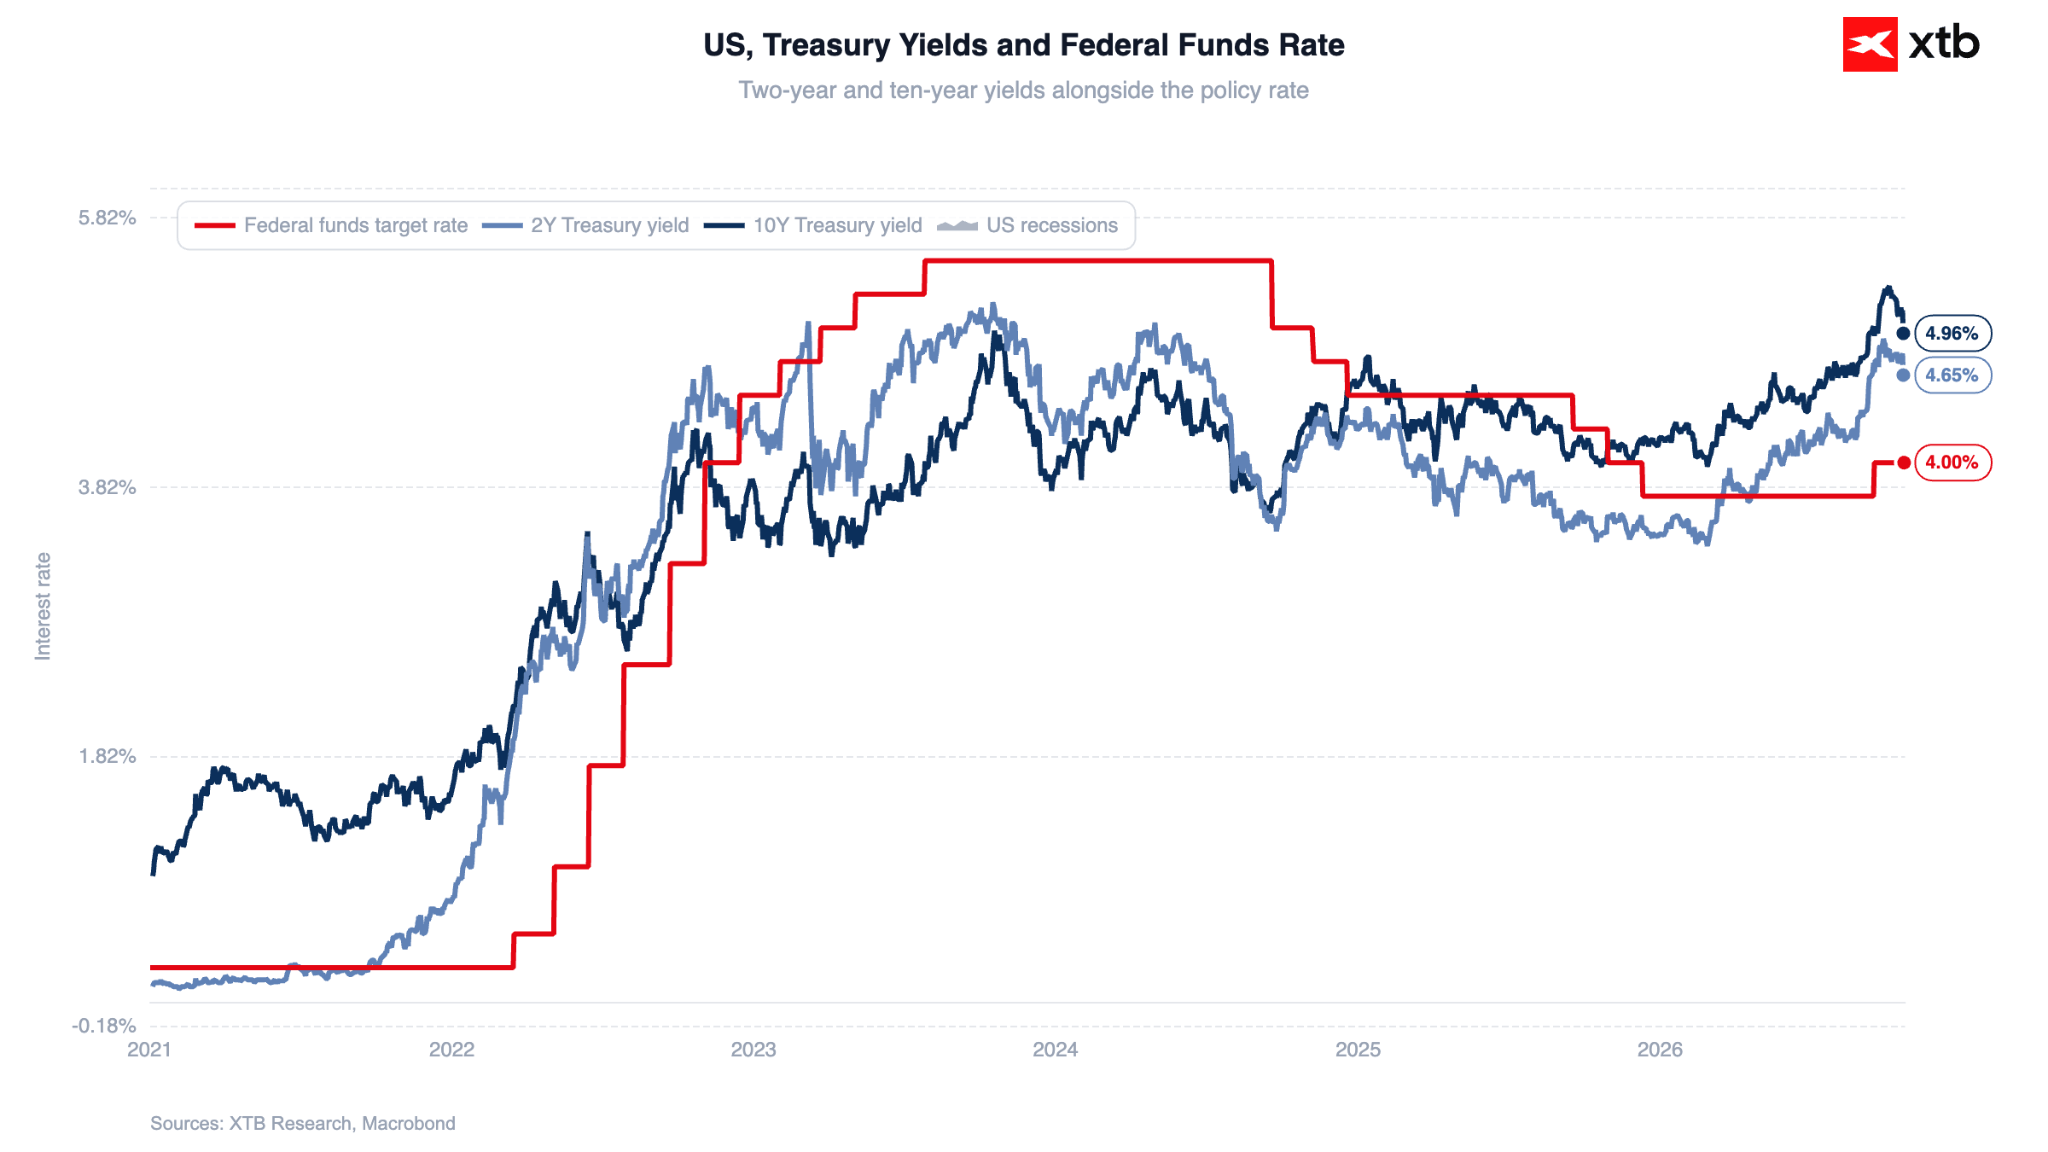
Regarding the debt market, the fall in yields on 10-year US Treasury bonds halted near the psychological barrier of 5%.
Figure 1: Federal Funds Target Rate and 2-Year and 10-Year US Treasury Yields (2021-2026)
 Source: XTB Research, 23.10.2026
Commodity pressure dictates market direction
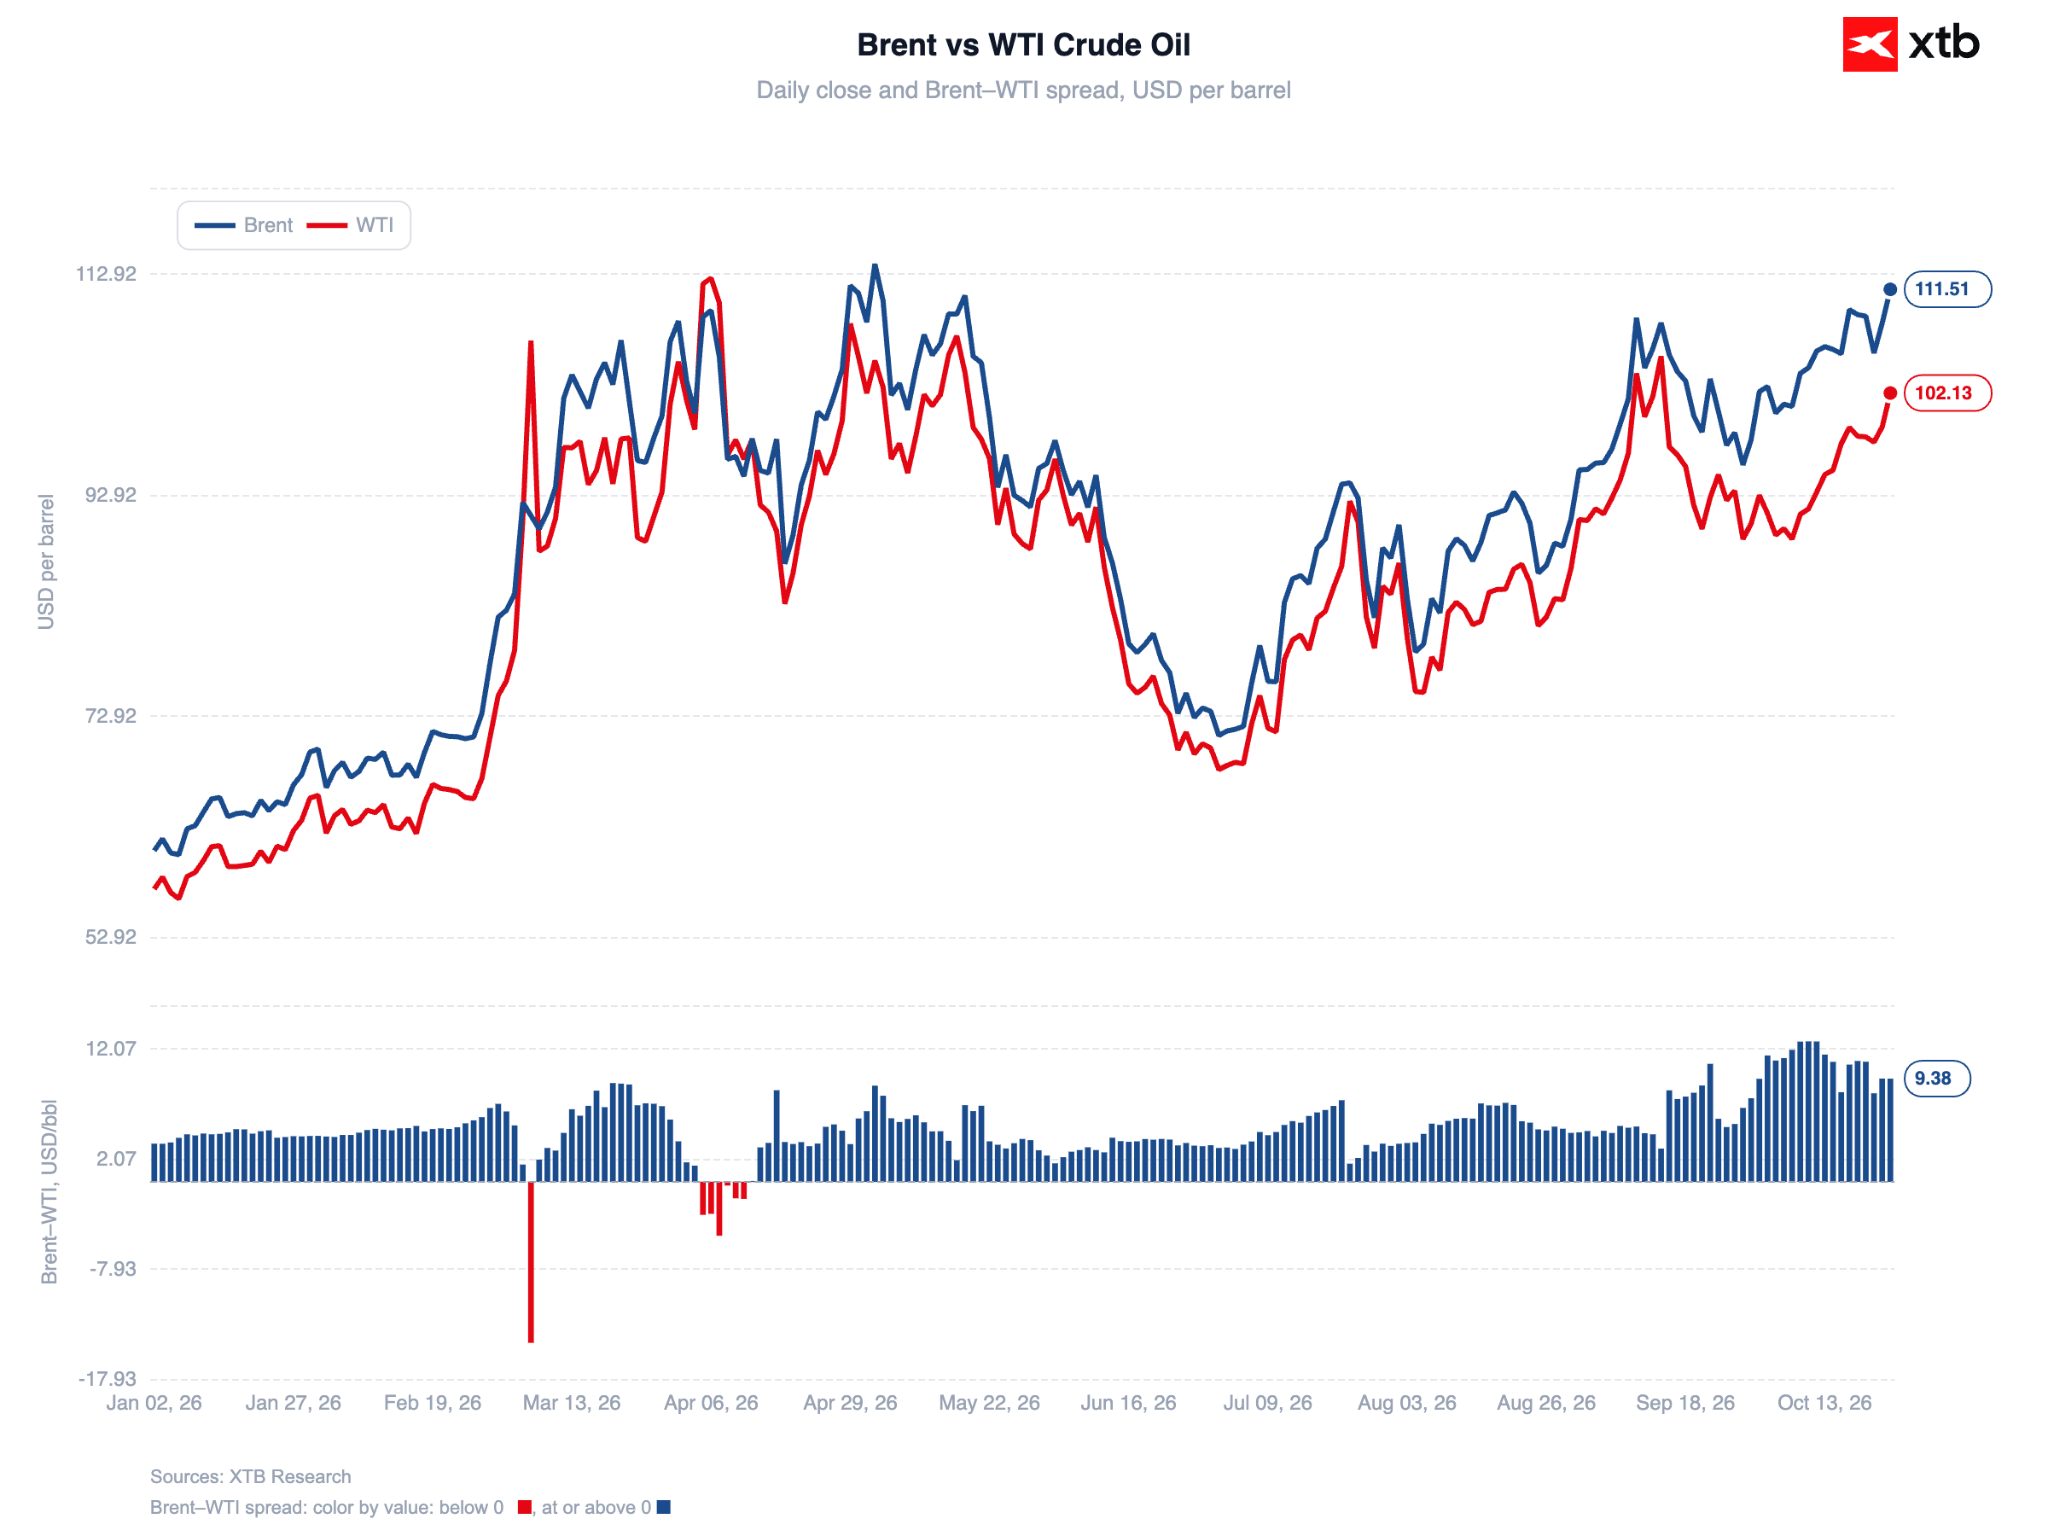
Following attacks by Houthi militants on the Saudi port of Yanbu and Aramco oil facilities, Brent crude prices surged past USD 111. WTI is hovering near USD 102 per barrel. The oil market is ignoring reports of temporary deliveries of Russian diesel to the US, pricing in the risk of a prolonged military impasse in the Strait of Hormuz area.
Figure 2: Brent and WTI Crude Oil (2026)
 Source: XTB Research, 23.10.2026
Cracks in the AI narrative
Meanwhile, in the AI segment, credit spreads are widening significantly. Investors are beginning to ask a key question: who will finance the rapidly mounting expenditure of hyperscalers with debt yields reaching 5%, given that OpenAI itself had to lower its target valuation from USD 1.4tn to USD 1.25tn.
Figure 3: Nasdaq 100 - Semiconductor Companies (2026)
 Source: XTB Research, 23.10.2026
Mixed picture in PMI data
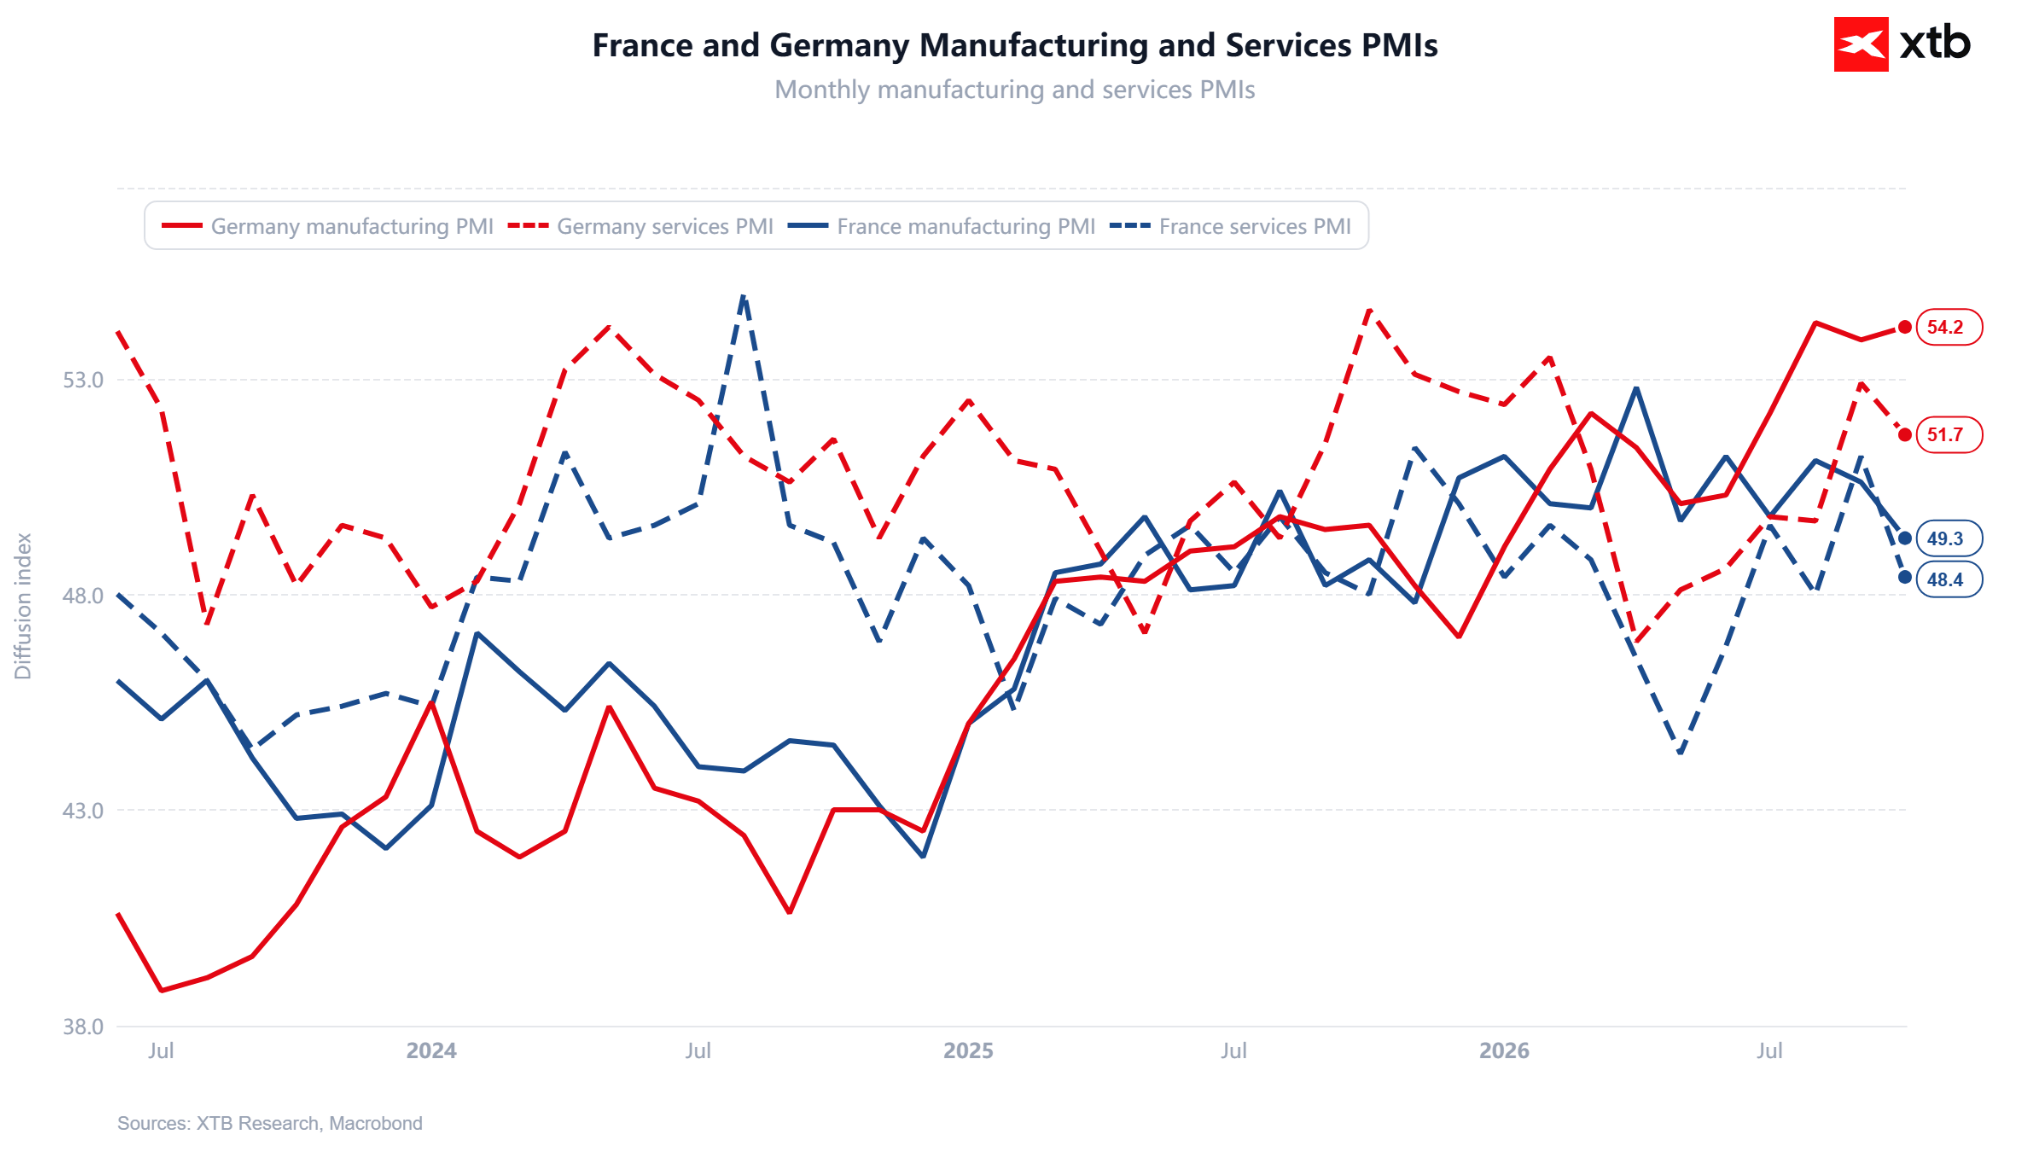
In Europe, PMI readings disappointed (a drop in the composite index for the eurozone to 51.9), largely due to France (composite indicator at 48.4).
Figure 4: PMI Indicators for Germany and France (2024-2026)
 Source: XTB Research, 23.10.2026
- Excluding the pandemic period, business confidence in France fell to its lowest level since the 2012 debt crisis.
- Employment in France contracted, whereas it grew in Germany and the rest of the eurozone.
- The growth rate of raw material purchases accelerated to its highest level in 4.5 years (inventory building, similar to April).
- Input prices were the highest since May, output prices lower than in September (suggesting margin compression).
- Data consistent with further tightening, though issues in France could stand in the way.
In the United Kingdom, the reading was surprisingly strong (53.1 pts).
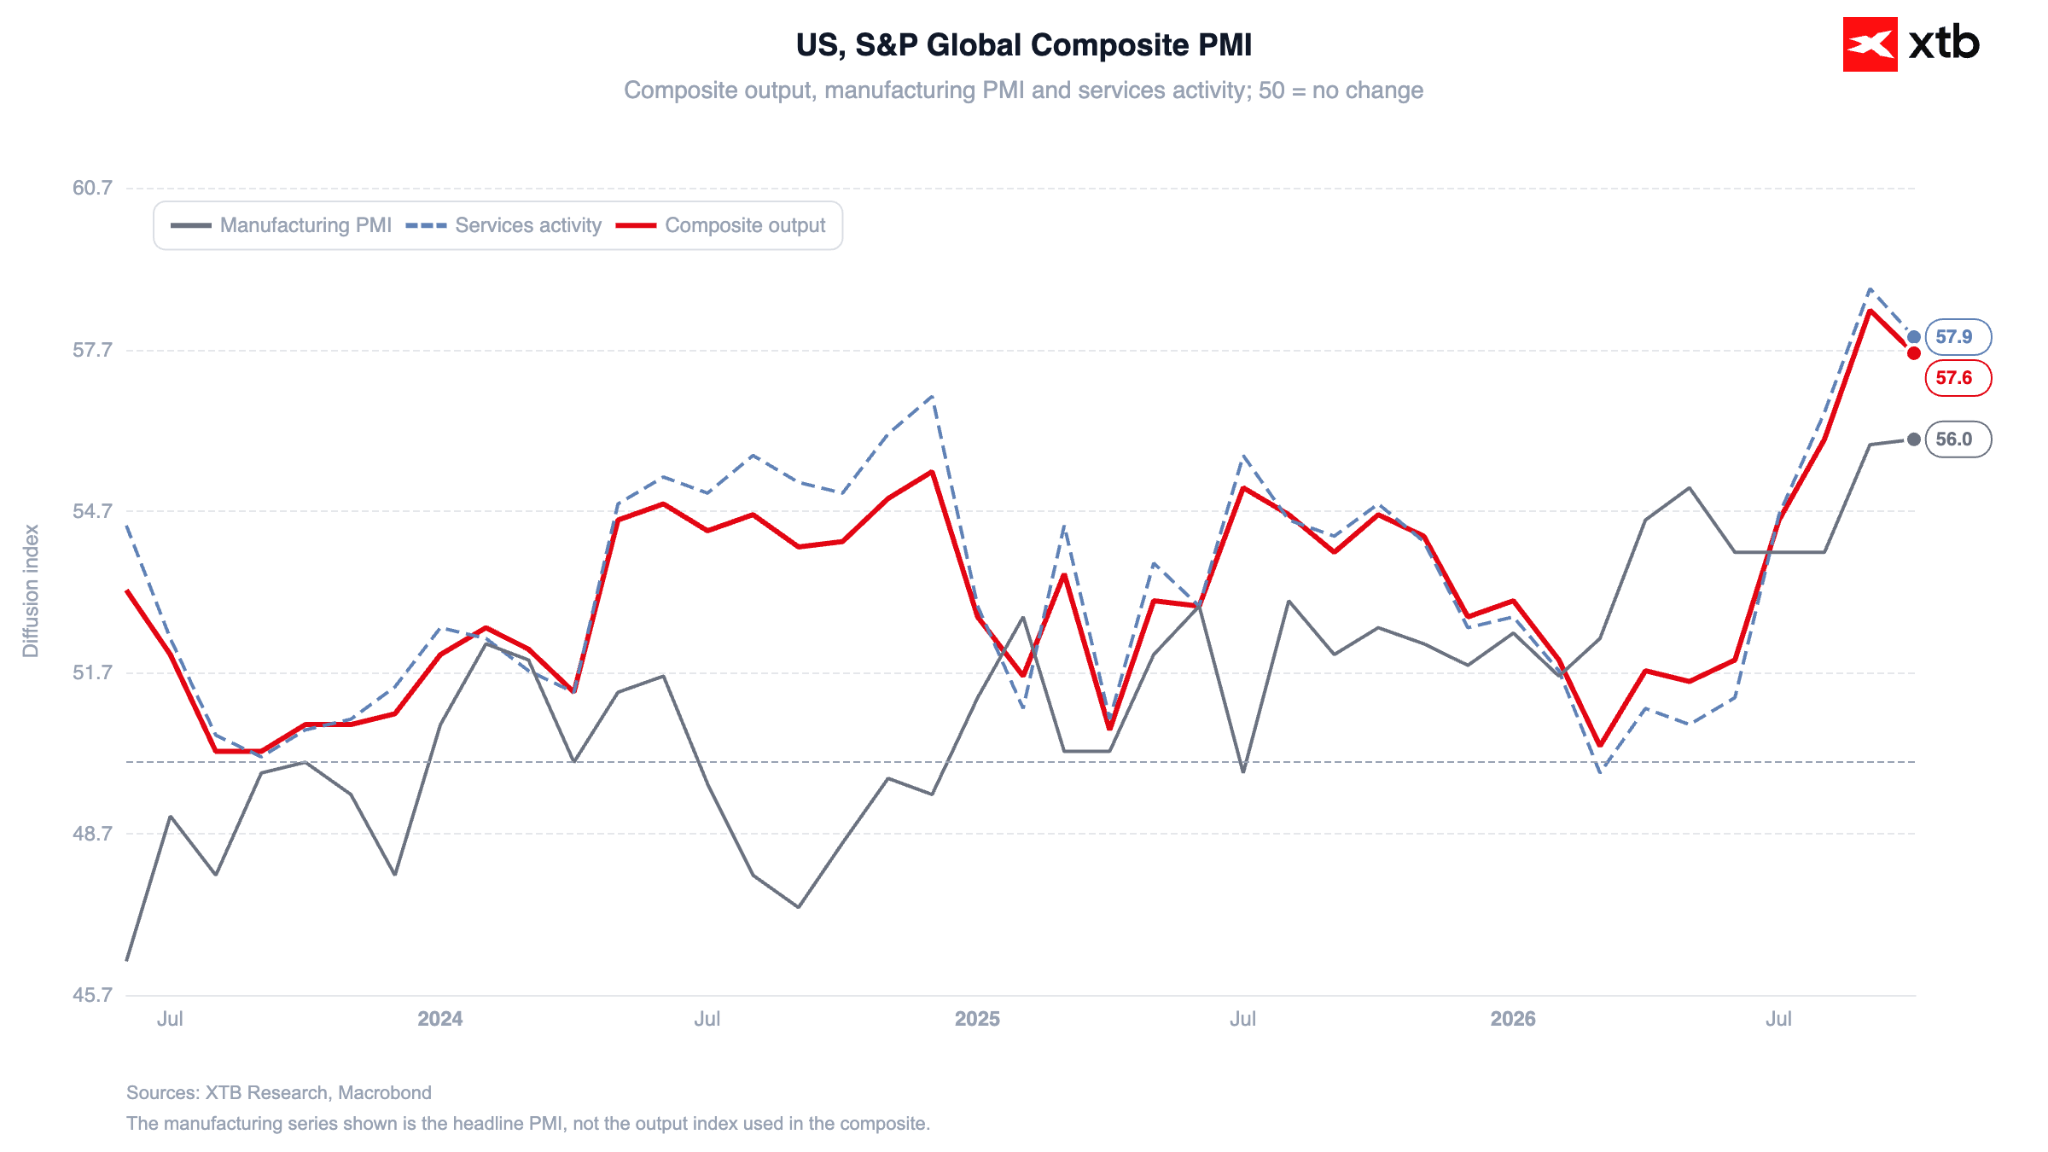
Data from the US slowed, yet still points to GDP growth of around 4% (Q3 Nowcast stands at 3.5%). Manufacturing (56) performed slightly worse than services (57.9).
Figure 5: PMI Indicators for the United States (2024-2026)
 Source: XTB Research, 23.10.2026
- It is worth noting, however, that in terms of the 12-month outlook, the situation is reversed. Furthermore, manufacturing employment is growing at its fastest pace since March 2012.
- Prices are rising faster in manufacturing than in services (which seems fairly intuitive given the sharp rise in oil prices).
- New export orders for goods are growing for the first time since June last year, while service exports are expanding at their strongest pace since July 2023.
Indices
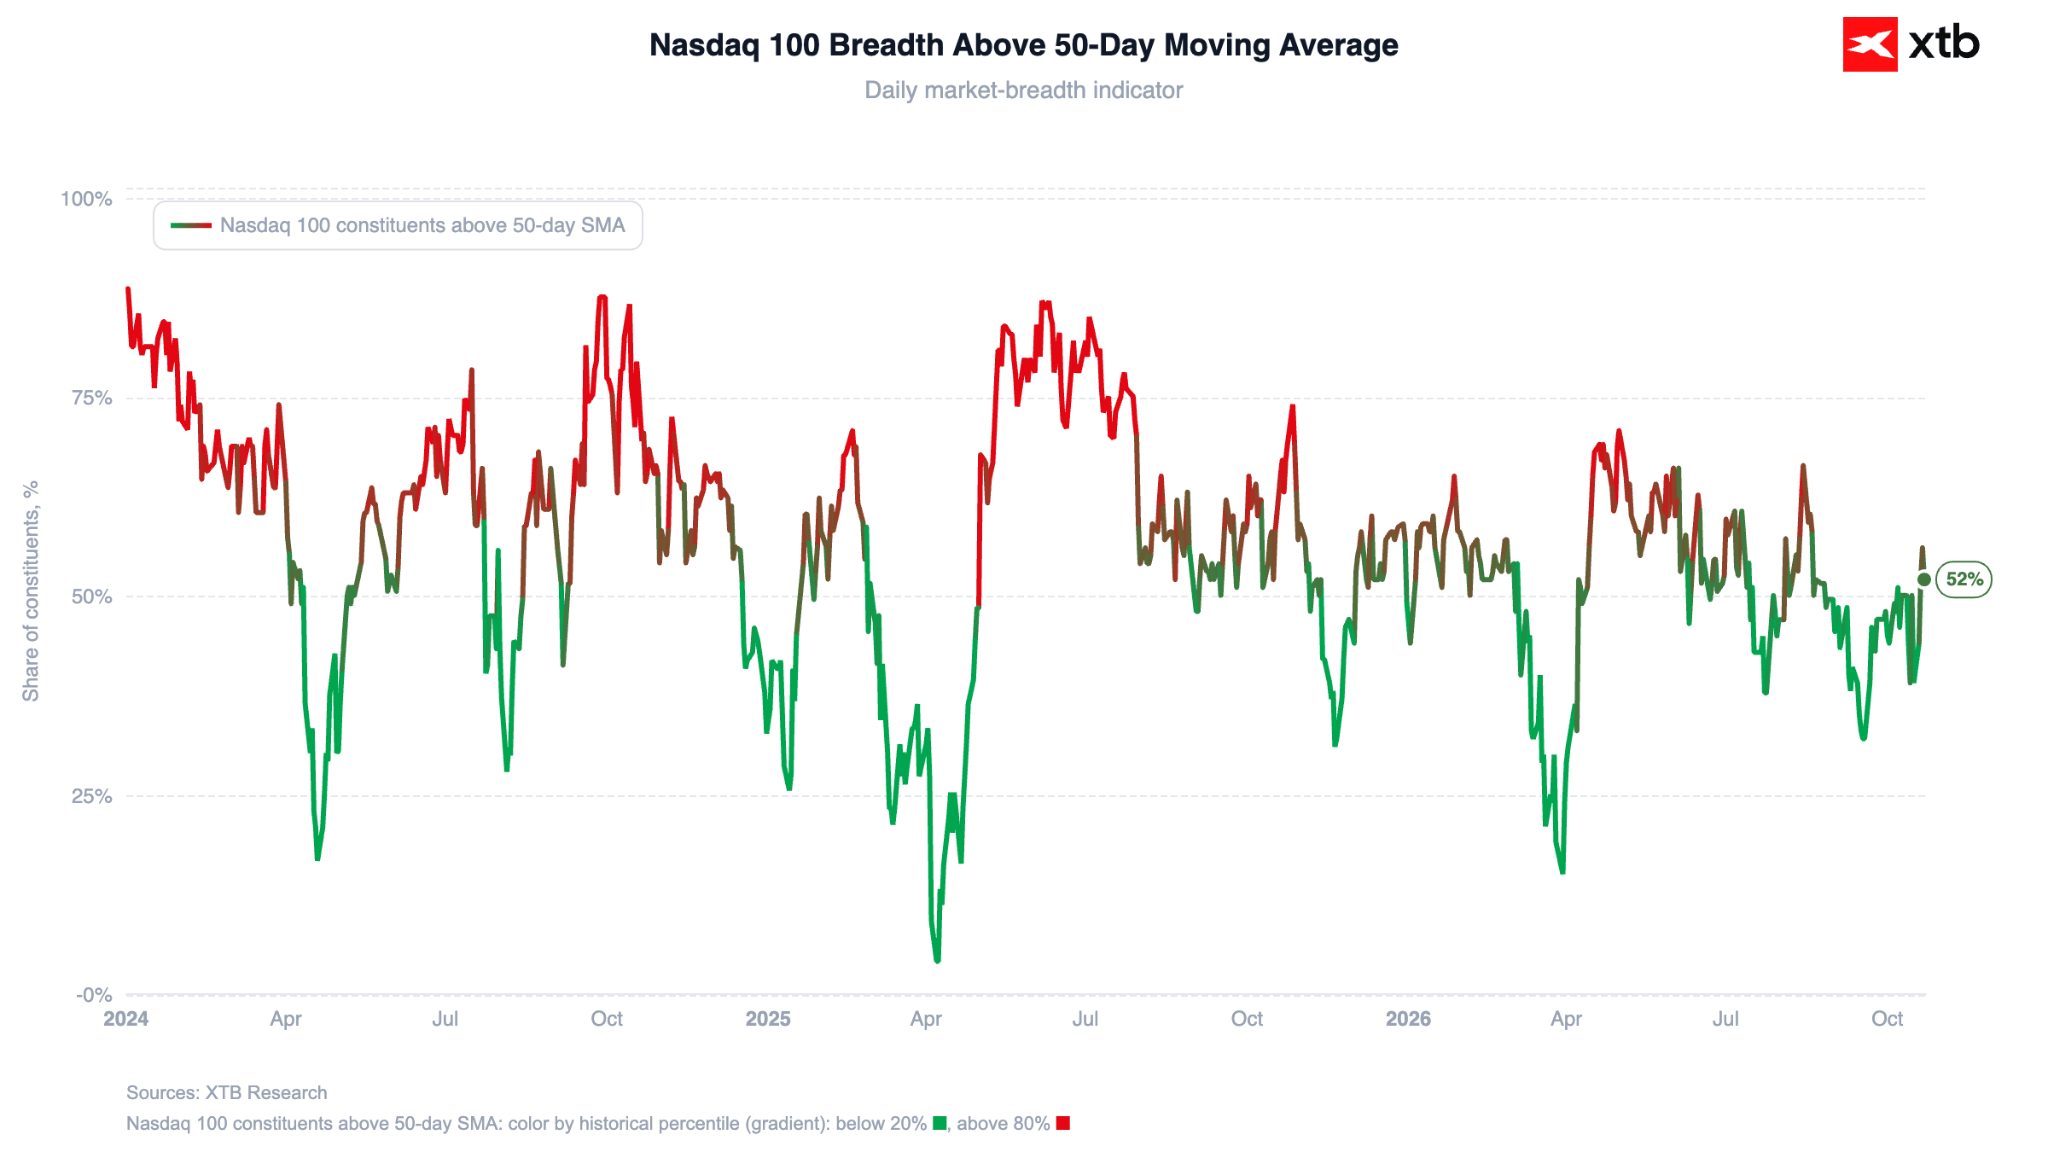
Red dominates Wall Street, though the scale of the sell-off in technology leaders is showing initial signs of stabilising:
- US500: 7,665 pts (-0.5%); the index remains under pressure from megacap selling, but strength in defensive stocks is curbing the pace of declines.
- US100: 29,071 pts (-0.1%); following Thursday's sell-off, the technology benchmark is stabilising thanks to selective dip-buying in discounted equities.
- US30: 52,485 pts (-1.1%); the session's weakest performer due to a sell-off in the financial sector, which is vulnerable to tightening credit conditions.
- US2000: 2,774 pts (-0.6%), small-cap segment losing ground amidst high oil prices and elevated debt servicing costs.
Figure 6: Percentage of Companies Above 50-Day Moving Average in Nasdaq 100 (2024-2026)
 Source: XTB Research, 23.10.2026
Key corporate news
- Telecommunications reshuffle (SpaceX plans): Reports regarding SpaceX's intention to acquire at least 80,000 base stations to launch its own mobile network triggered a massive capital rotation in the sector. Passive infrastructure owners surged, with Crown Castle (CCI.US) rising by approximately 11% and American Tower (AMT.US) gaining nearly 8%. At the same time, traditional operators face the prospect of intense competition: AT&T (T.US) plunged 4%, while T-Mobile US (TMUS.US) lost 5%.
- Lockheed Martin (LMT.US): Shares in the defence giant rose approximately 7.8% following an upgrade to full-year earnings guidance (adjusted EPS of USD 30.35-30.75 versus market consensus at the lower end of the range). Results are driven by a 24% YoY surge in operating profit within the missile segment and a record backlog reaching USD 292bn amid conflicts in the Middle East and Ukraine.
- Moderna (MRNA.US): Shares dropped by roughly 6% to around USD 189 (extending weekly losses to over 13%). Investors offered a cool reception to the latest clinical trial data from advanced studies on a personalised melanoma vaccine.
- Deckers Outdoor (DECK.US): Shares tumbled 8% in response to a cut in full-year net revenue forecasts for UGG and Hoka brands below market consensus, triggering a wave of broker downgrades (including a reduction to "underweight" by Piper Sandler).
- RingCentral (RNG.US): The company surged about 15.2% after raising its full-year guidance for adjusted operating profit.
- Meta Platforms (META.US): A 1.8% decline to around USD 637 pushed weekly returns down to -10%. Despite solid fundamentals, the firm is suffering from a broader retreat from tech; RSI slid to an overbought/oversold reading of 36.8 with a P/E ratio of 22.0.
- American Express (AXP.US): Shares dropped 1.9% (-12% YTD) as Q3 transaction volume and revenues came in slightly below analyst expectations, despite maintaining sound credit portfolio quality.
- General Motors (GM.US): The company is heading towards its worst week in over 20 months (down roughly 8% on a weekly basis). Nevertheless, Wall Street analysts (including BNP Paribas and StoneX) broadly recommend buying the dip, pointing to extremely low valuation multiples and growing cash generation.
- SLB (SLB.US): The oilfield services firm gained 2% after adjusted Q3 profit beat market expectations, driven by a clear rebound in Middle East drilling activity.
Main market themes
- Bubble popping or opportunity of a lifetime?: Retail investors are increasingly debating the phenomenon of "cash burning" on cloud infrastructure, highlighting the growing divergence between a 93-fold increase in model usage and the lack of direct monetisation among providers.
- Jealousy towards defence: The rise in Lockheed Martin shares (+17% across nine sessions) triggered discussions over missed gains in defensive sectors benefiting from geopolitical instability.
- Fear of forced deleveraging: Anxiety is palpable surrounding reports of the worst week for global hedge funds since the pandemic. Some investors fear a wave of forced position liquidations in semiconductors, though a growing group of bargain hunters is expecting a sharp rebound following the sell-off.
—
Michał Jóźwiak, Financial Markets Analyst at XTB



Market Wrap: "Decent" results are not enough – tech stocks fall further; oil highest since May (22.10.2026)


Tesla was supposed to burn $5 billion, but posted a positive result. Will Tesla still be a car company in a year?


Record-breaking Meta, though with a cash loss. Investors (for now) are buying Zuckerberg's plan anyway



Daily Summary: SpaceX and the tech sector drive Wall Street, oil retreats sharply below $97
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.