


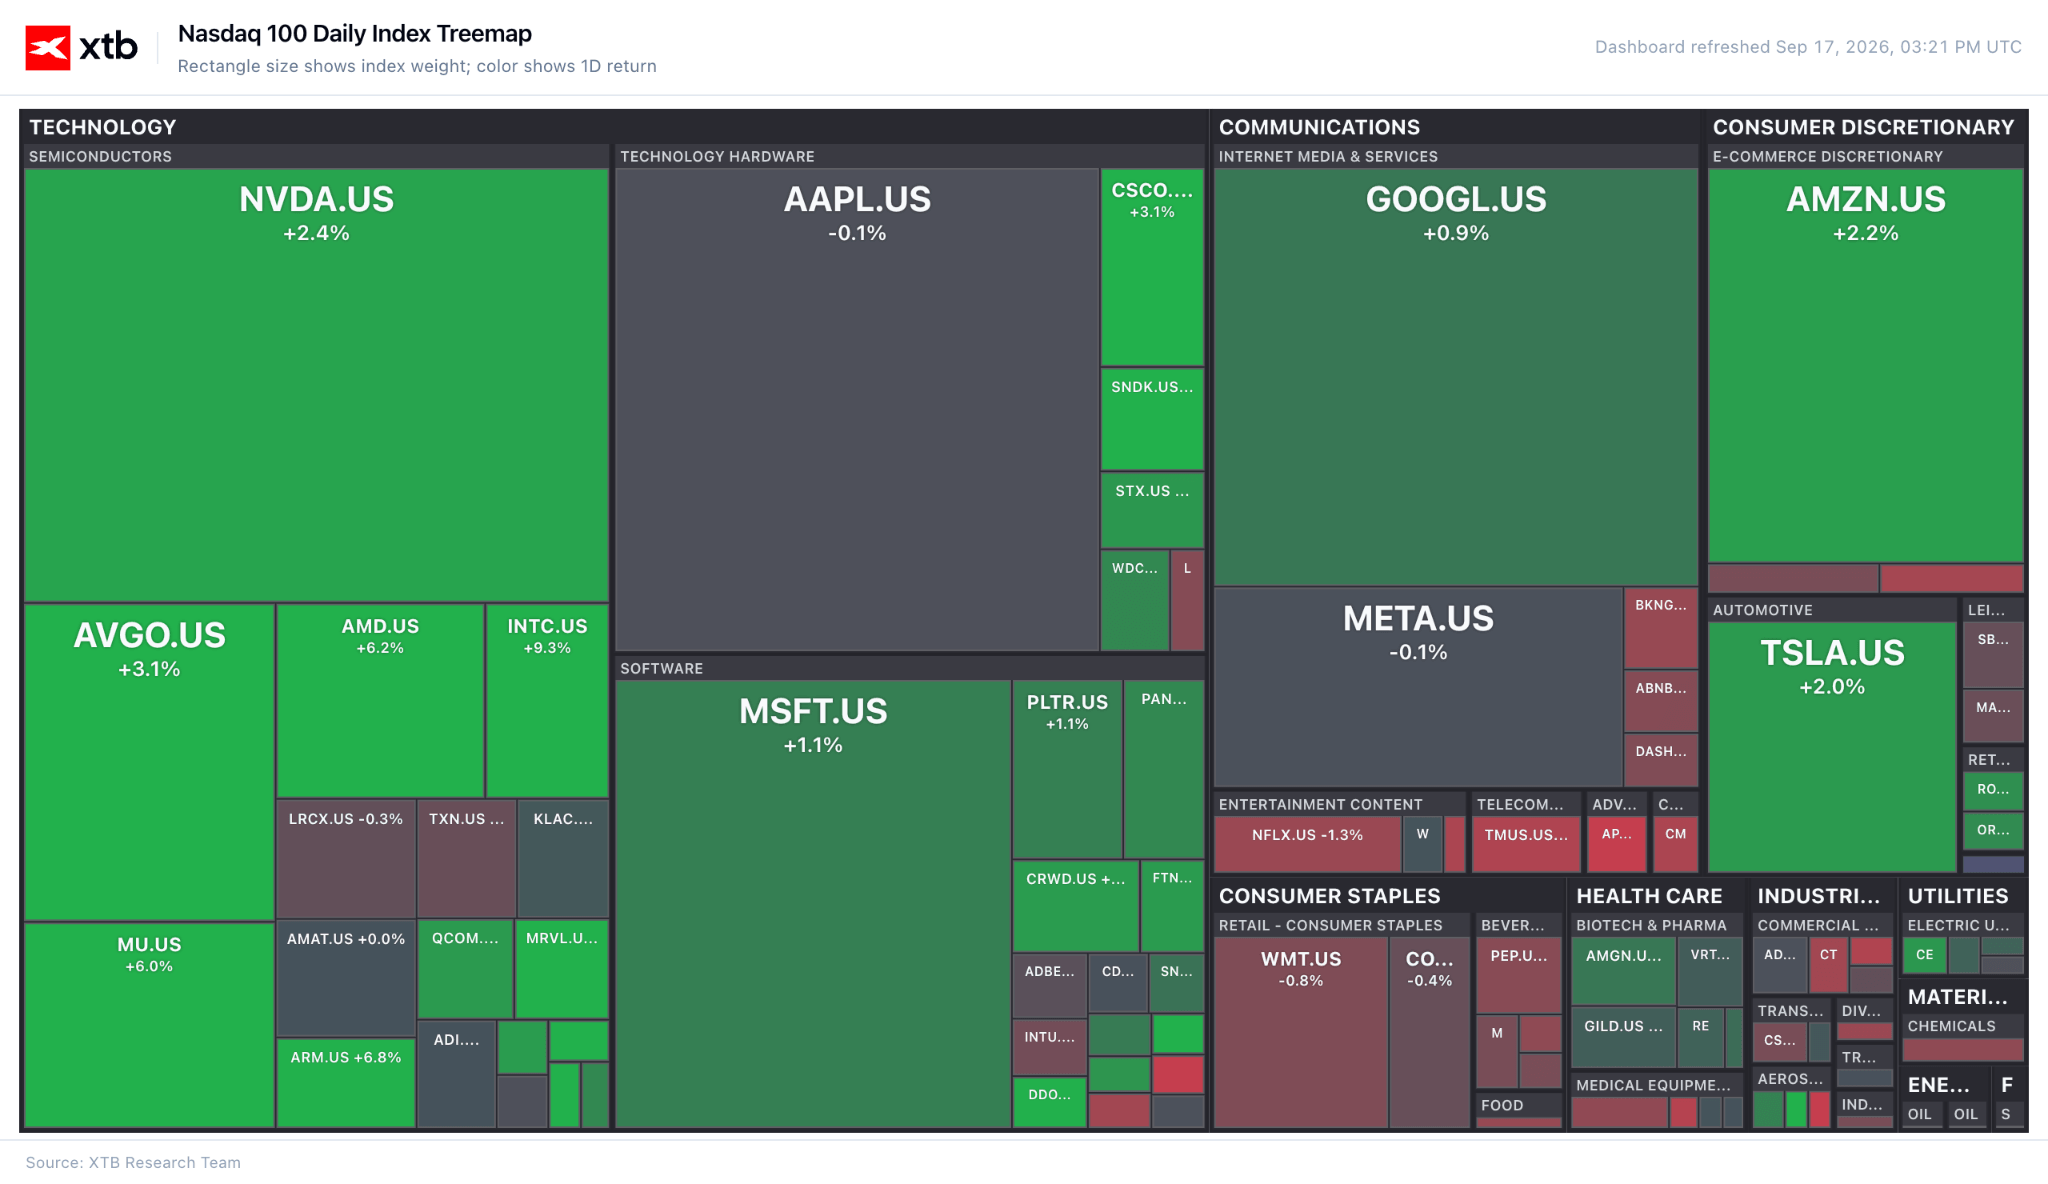
A day after Wednesday’s Federal Reserve decision – the first interest rate hike since July 2023 – US indices are rallying sharply. For both the S&P 500 (+0.9%) and the Nasdaq 100 (+1.5%), this marks one of the strongest market opens in recent weeks.
Figure 1: Treemap for Nasdaq 100 (17.09.2026)
 Source: XTB Research, 17.09.2026
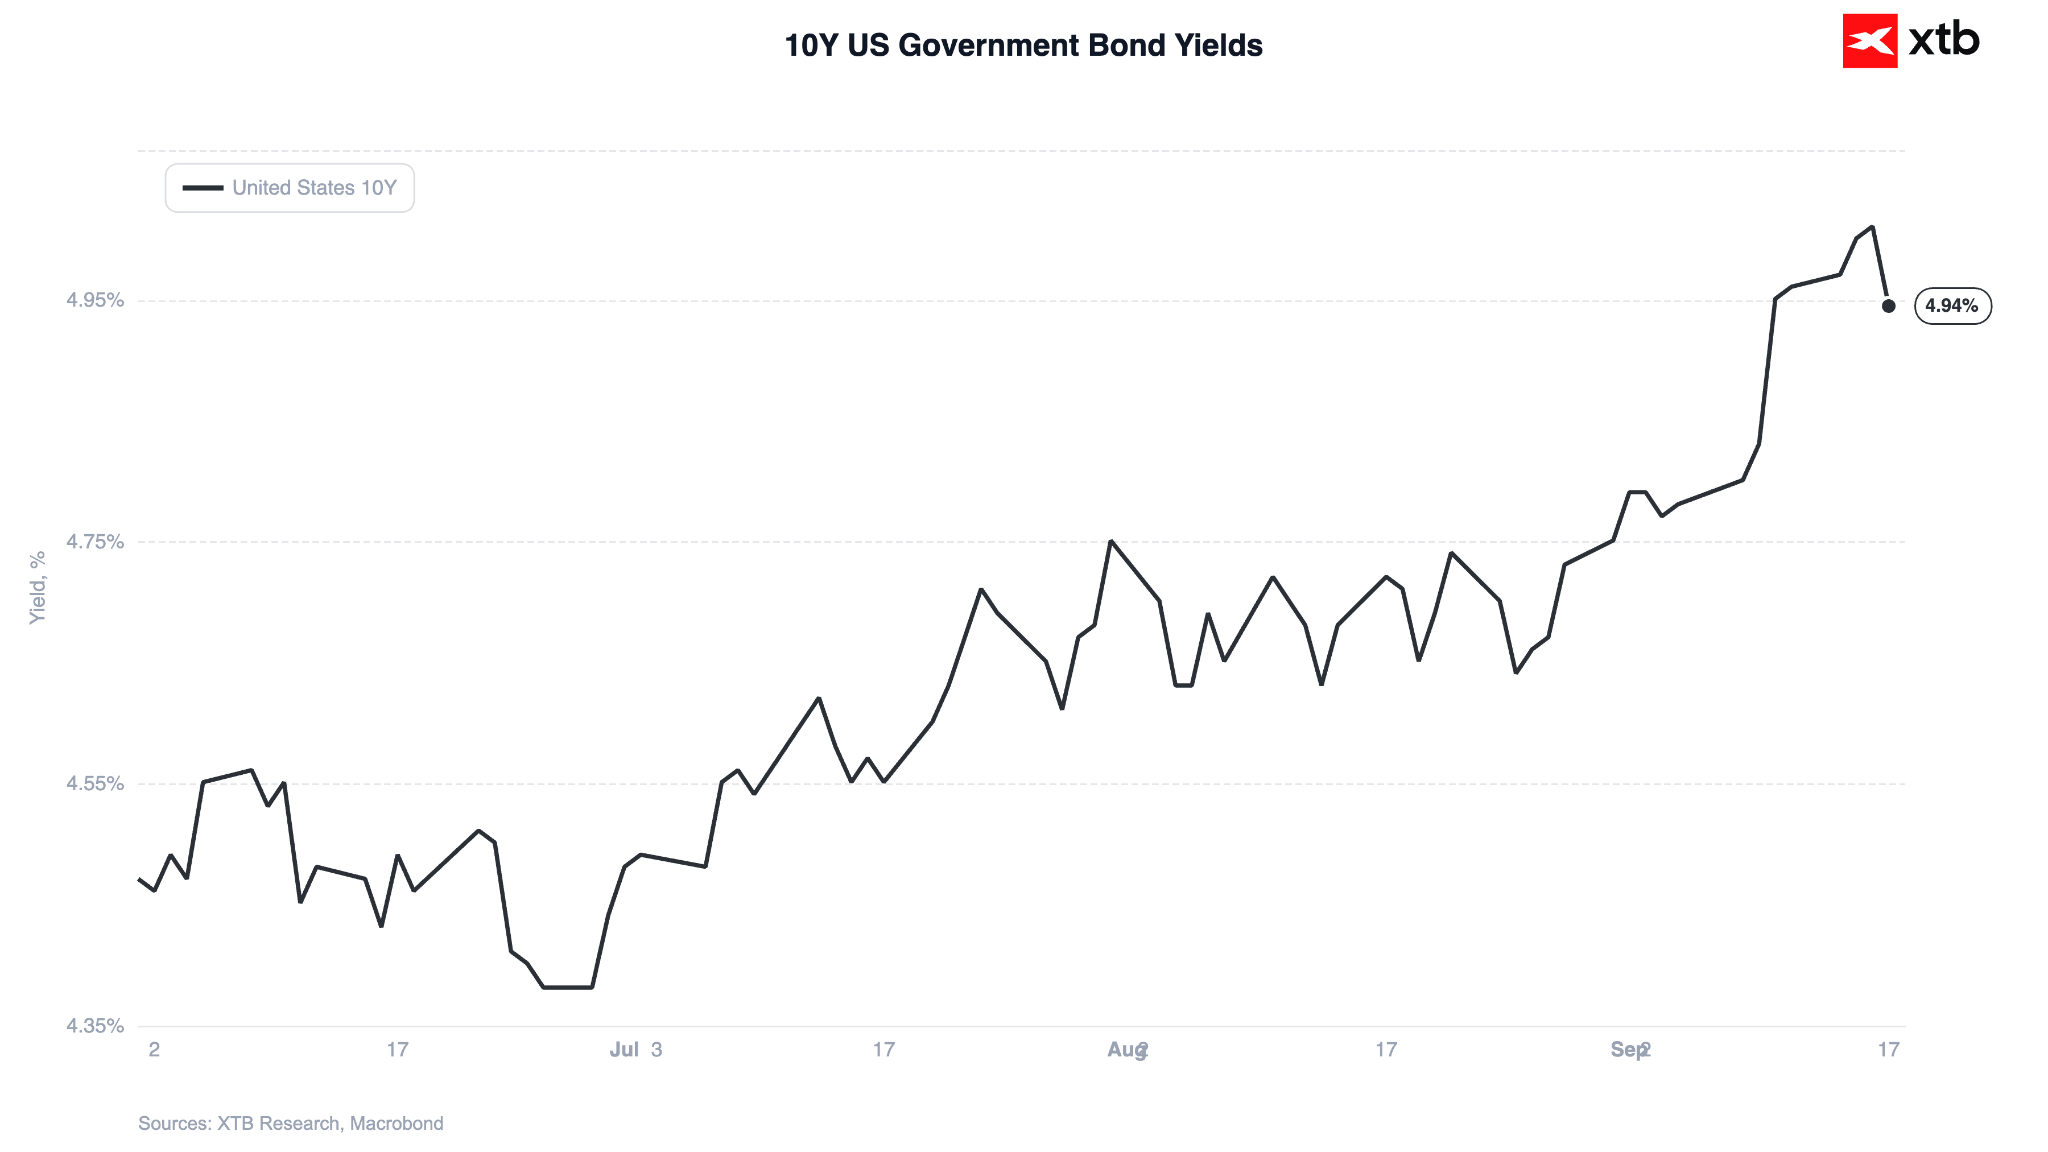
This is by no means an intuitive move. However, the stock market is receiving firm support today from a drop in 10-year US Treasury yields (down by a full 1.6%). We attribute this movement both to easing concerns regarding the FOMC’s loss of independence and to falling crude oil prices.
Figure 2: 10-Year US Government Bond Yields (06.2026 - 09.2026)
 Source: XTB Research, 17.09.2026
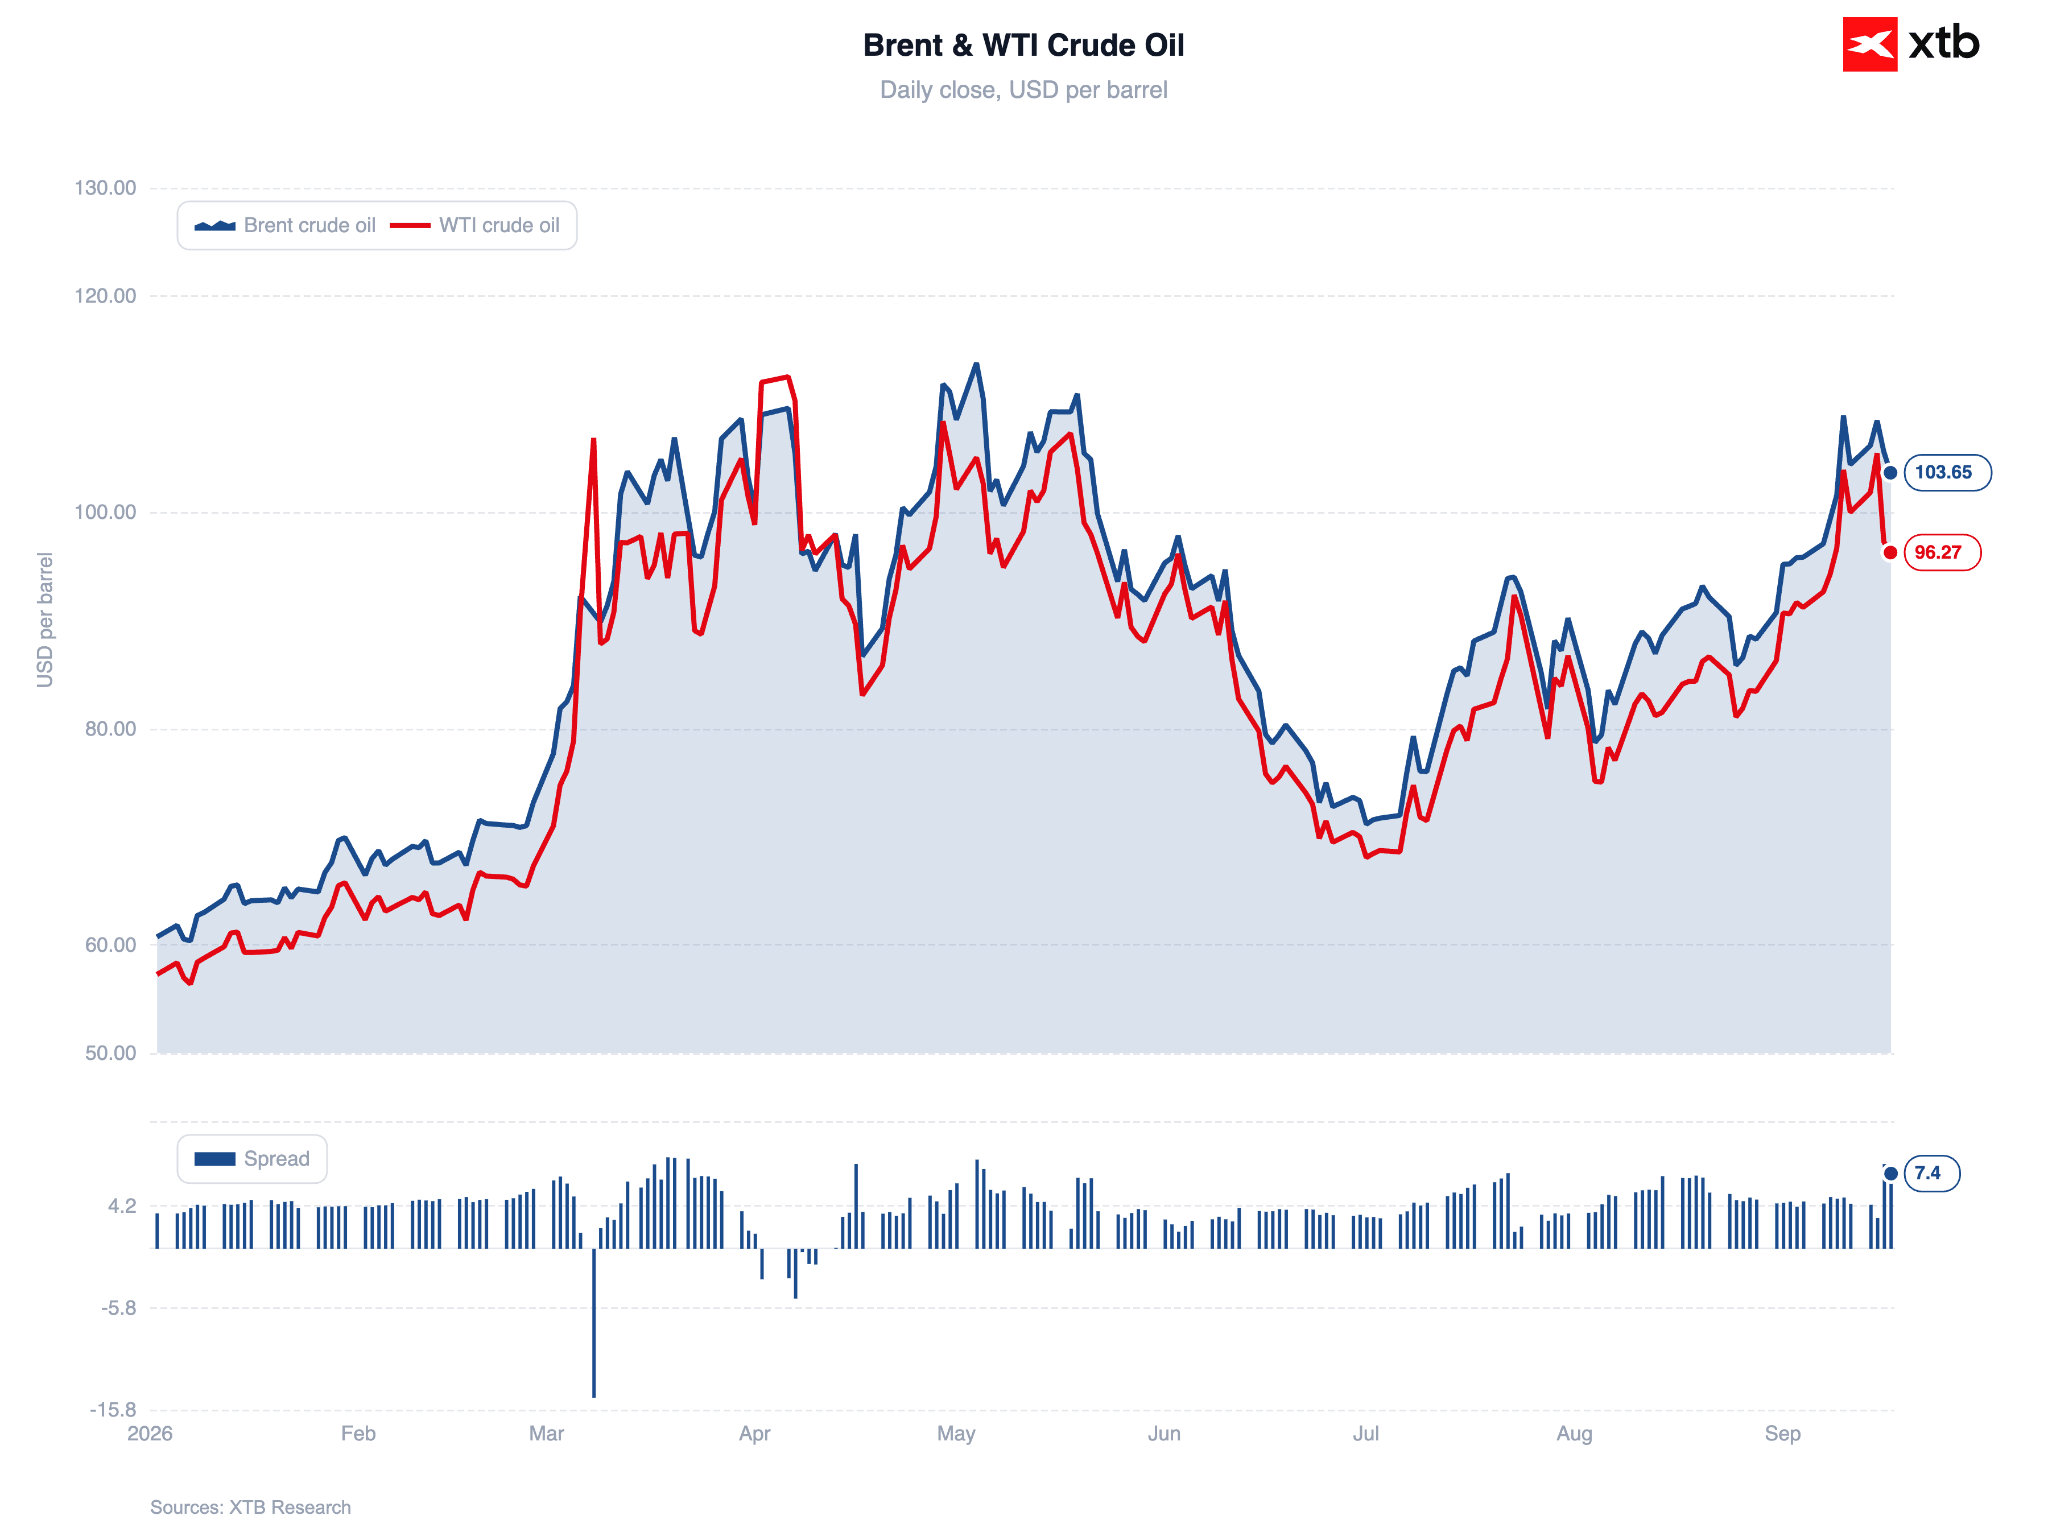
A barrel of Brent crude oil is currently trading at just over $103, representing a fall of around 5% from the local highs recorded earlier this week. This decline is supported, among other factors, by the rerouting of a portion of Saudi crude oil exports previously transported via the East-West pipeline through Oman. Investors also welcomed assurances from the US side that the damaged pipeline is expected to resume operations within the next few days.
Figure 3: Brent and WTI Crude Oil (2026)
 Source: XTB Research, 17.09.2026
Concurrently, investor and public attention is focused on an AI safety summit convened by King Charles III in the UK, where speakers included Nvidia CEO Jensen Huang.
As noted earlier, at the open, the Nasdaq 100 is up by approximately 1.5%, whilst the S&P 500 gains 0.9%. The Dow Jones posts more modest gains (+0.4%). The semiconductor sector, which is highly sensitive to bond yields (a key factor in discounting future cash flows), is performing particularly well, with the popular SOXX index up by over 3% today.
Figure 4: Winners and Losers in the Nasdaq 100 (17.09.2026)
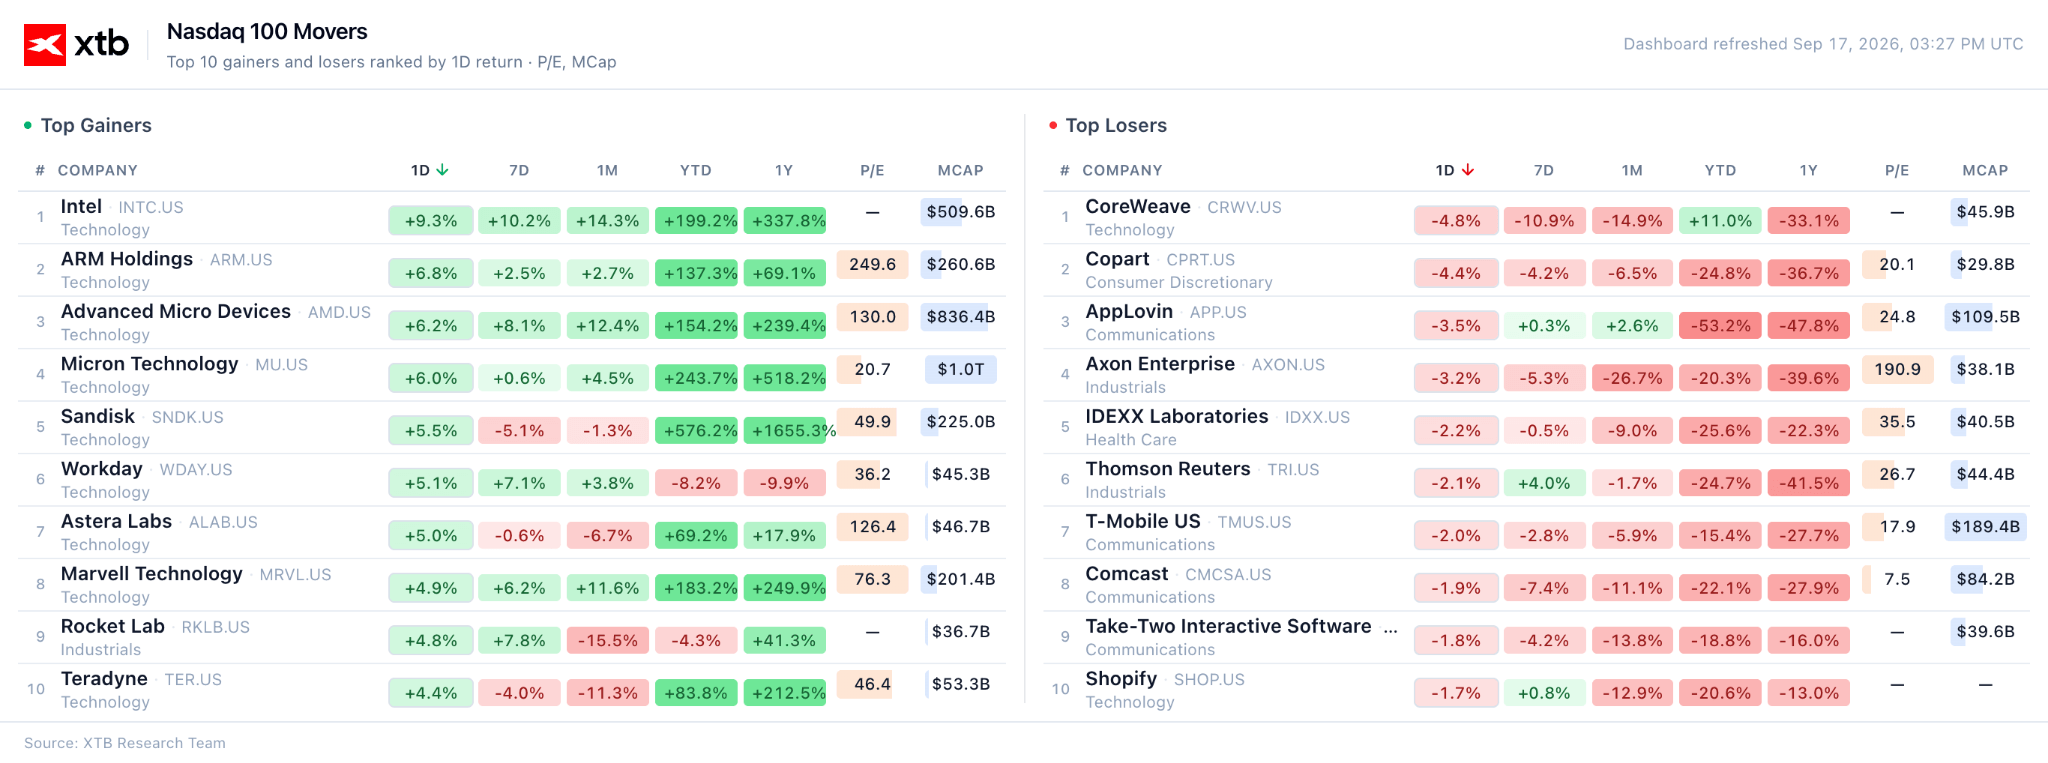 Source: XTB Research, 17.09.2026
Markets Digest the Hawkish Fed Meeting
Wednesday’s rate hike triggered a modest and ultimately short-lived sell-off on Wall Street. For investors, restoring faith in the Fed’s independence and effectiveness proved more important than the increase in borrowing costs. Confidence has returned that the central bank will manage to rein in inflation, which ultimately led to a drop in bond yields across the entire curve.
This environment benefits not only equities but precious metals as well. Gold is up over 2% today to around $4,360 per ounce, whilst silver has surged by more than 4% to $65.7.
Figure 5: Gold (17.09.2026)
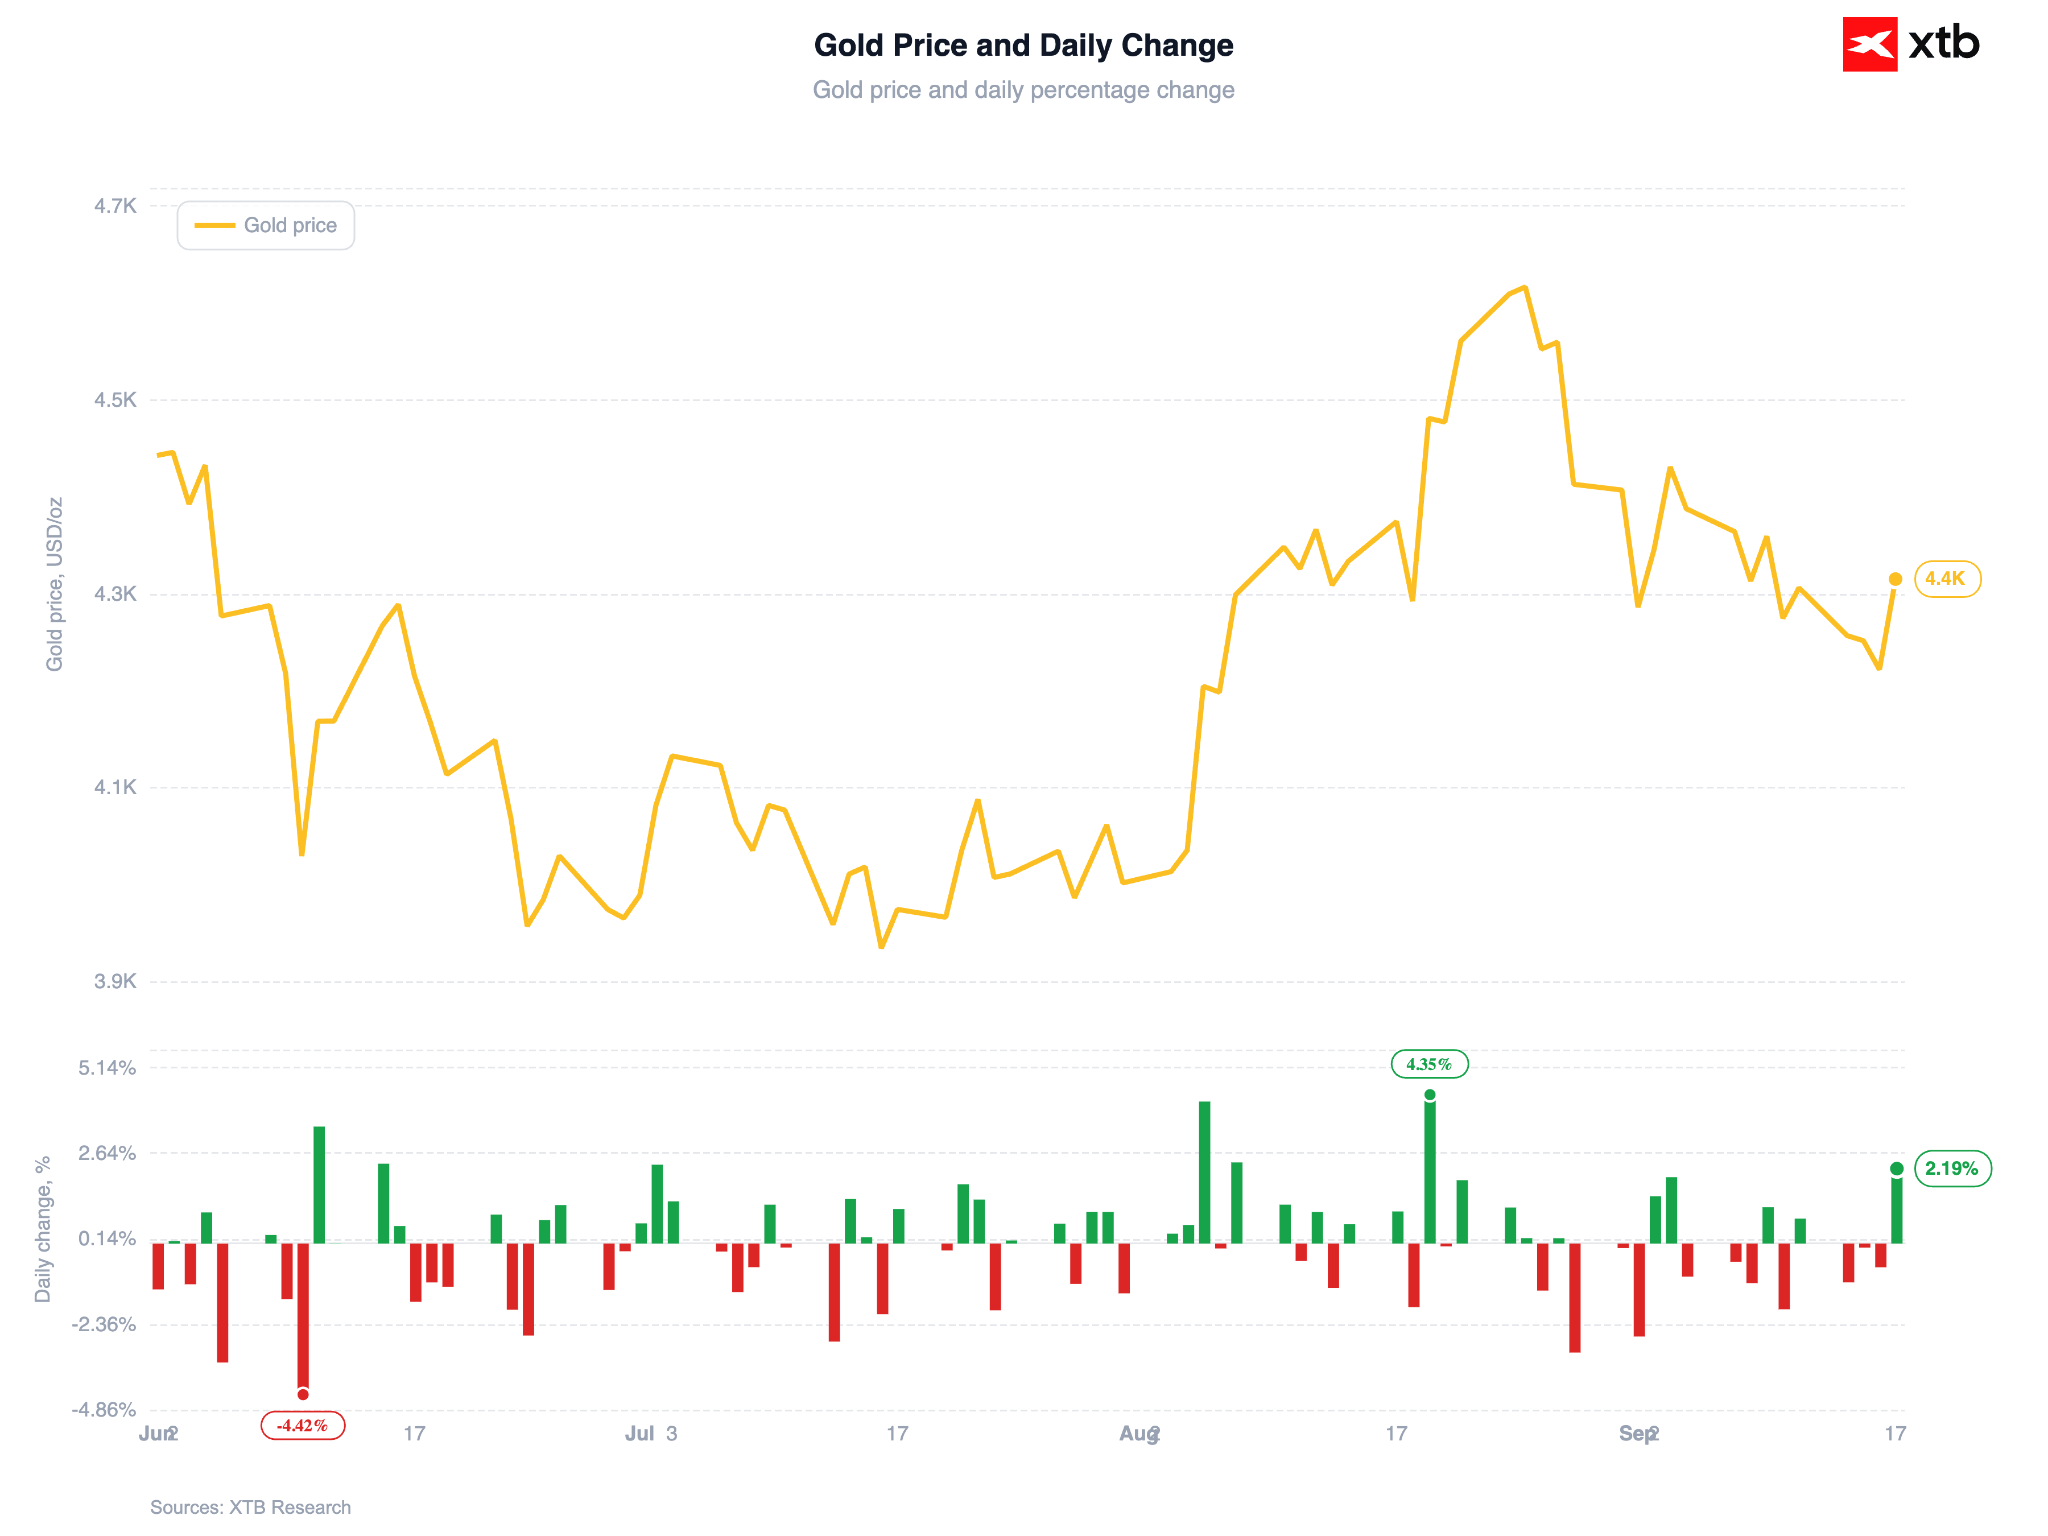 Source: XTB Research, 17.09.2026
Bank of England Refrains from Following Fed’s Lead
The Fed’s decision was not the sole major monetary policy event this week. The Bank of England kept interest rates on hold today and opted for a very gradual balance sheet reduction, resulting in a marked drop in 10-year gilt yields.
Overnight, the Bank of Japan will announce its interest rate decision. Failure to raise rates to 1.25% would be viewed as a major surprise by the markets.
Figure 6: USDJPY (2026)
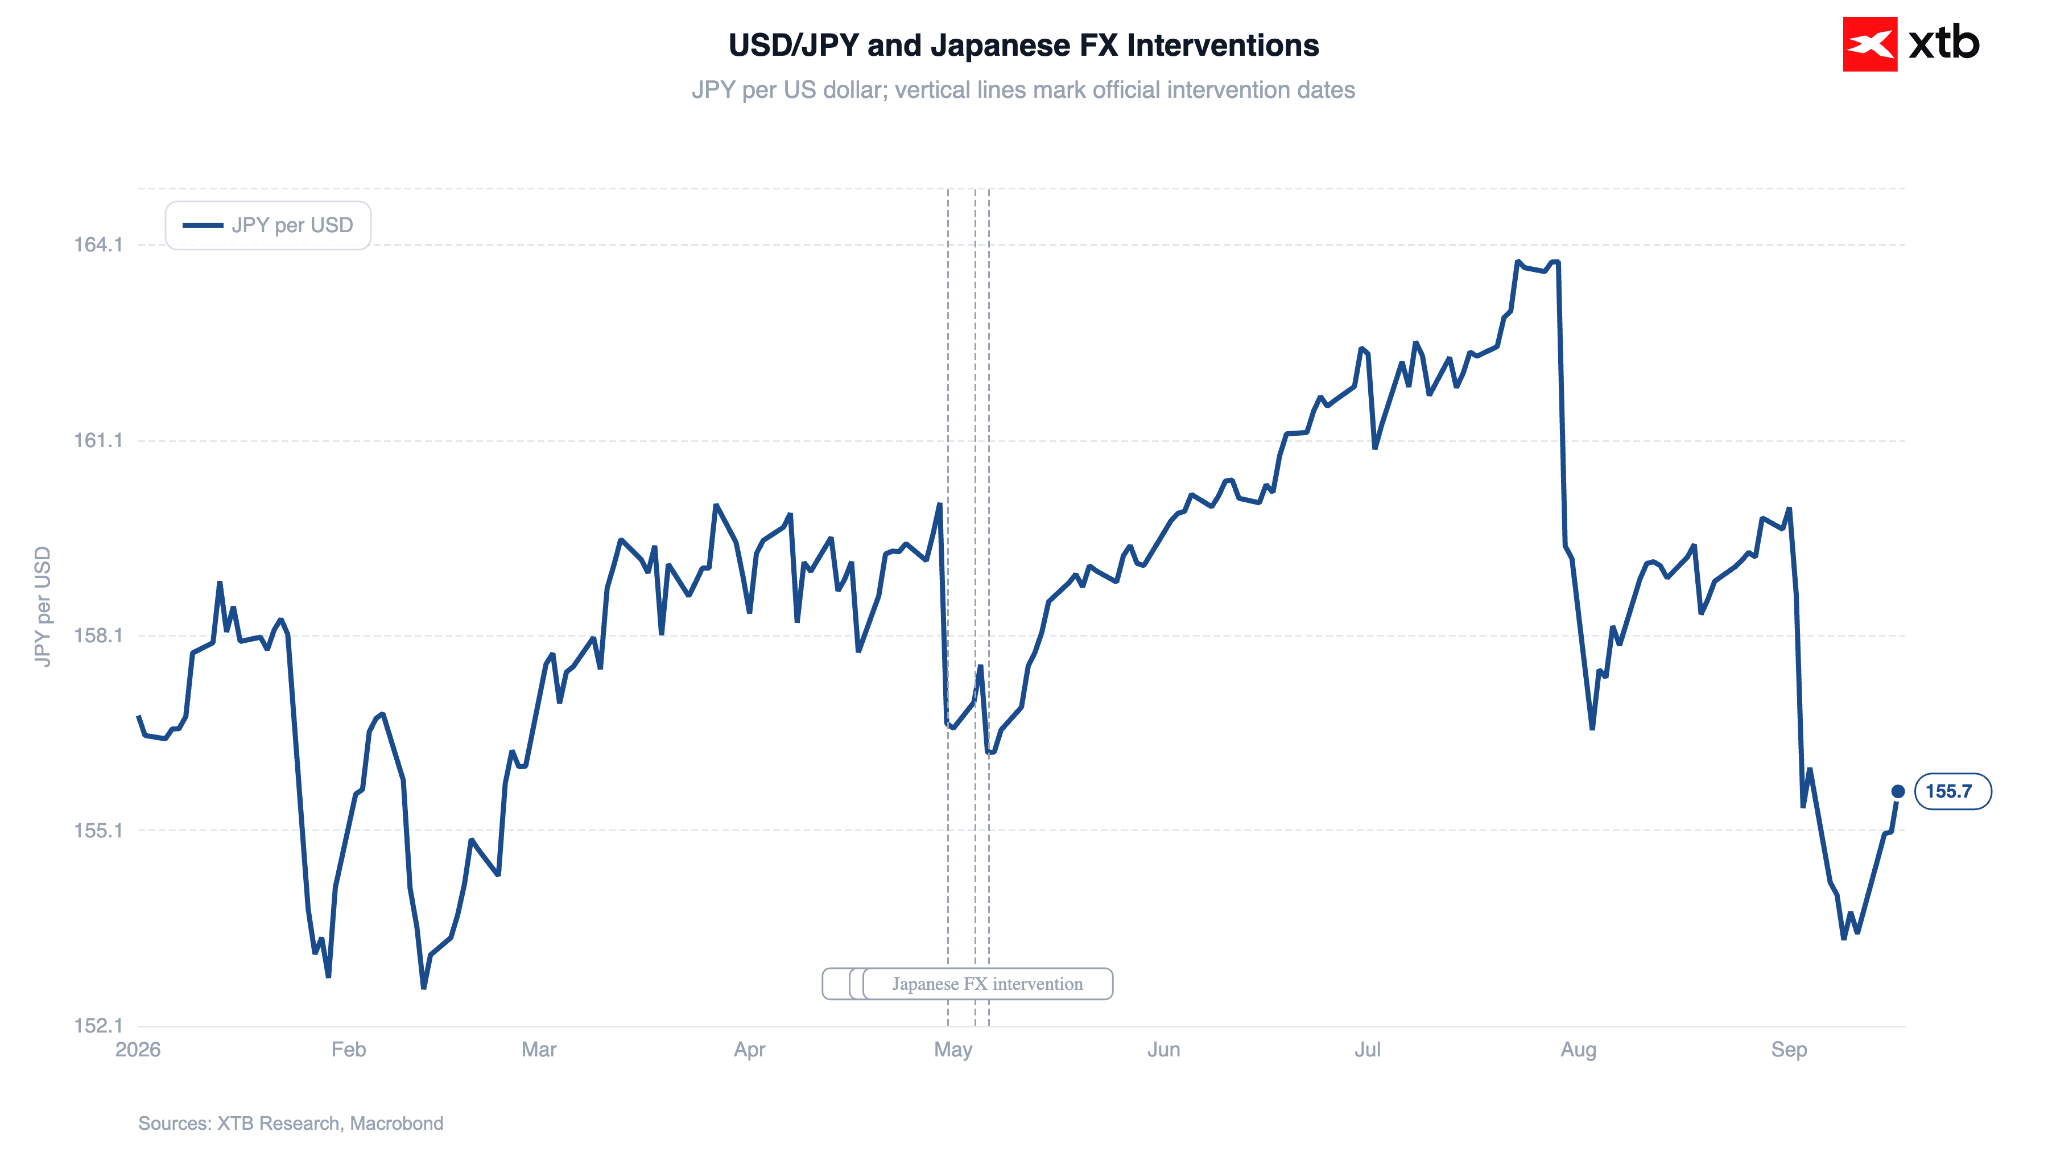 Source: XTB Research, 17.09.2026
Nvidia CEO Calls for Rigorous Testing
Against the backdrop of market events, an AI safety summit convened by King Charles III took place in Scotland, attended by Jensen Huang (Nvidia), Demis Hassabis (Google DeepMind), Sarah Friar (OpenAI), and Tino Cuellar (Anthropic), among others. Huang urged AI developers to rigorously test their systems and halt the deployment of products that are not sufficiently safe.
The meeting followed a widespread debate sparked by a weekend essay from Anthropic CEO Dario Amodei calling for a slowdown in the development of the most advanced AI models – a proposal supported by OpenAI CEO Sam Altman. Huang, however, spoke against additional regulation of the sector.
Although the AI safety debate is not the main driver of valuations today, tech companies in the Magnificent 7 group are posting solid gains – Nvidia and Amazon are up by over 2%, whilst Tesla, Alphabet, and Microsoft gain over 1%.
Company News
Fluence Energy ($FLNC.US)
Shares in the energy storage provider are down by over 15% following a downgrade to its full-year revenue guidance, which analysts attribute to production bottlenecks.
Generac ($GNRC.US)
Shares in the generator manufacturer are surging nearly 20% today. The company signed an agreement with an Amazon-affiliated entity to supply data centre generators valued at approximately $8 billion.
CoreWeave ($CRWV.US)
The AI cloud computing provider launched a new funding round comprising a $3 billion convertible bond issuance and arrangements for a potential equity offering.
Pegasystems ($PEGA.US)
Shares in the software developer are down more than 2% today after JPMorgan downgraded its rating to Neutral, citing weaker growth prospects following a meeting with the company's management.
—
Michał Jóźwiak, Financial Markets Analyst at XTB


🇬🇧 Will the pound recover after the BoE?



📊Daily Summary - Hawkish Fed raises rates and signals more. Dollar gains while gold falls


Hawkish move from the Fed! Warsh takes no prisoners in the fight against inflation. US500 at its lowest since August 3, and gold already below $4,300.

⬇️EURUSD below 1.15 following hawkish Fed
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.