


Wall Street opened Tuesday’s session without a clear direction, with the Nasdaq 100 up 0.4%, while the S&P 500 and DJIA are slightly lower. Investors remain cautious ahead of a series of important U.S. macroeconomic releases. The coming days will bring key data on the labor market and consumer activity, including consumer confidence indicators, as markets look for signs of whether the U.S. economy is genuinely losing momentum into year-end.
- Tensions remain elevated in the bond market. The U.S. 10-year Treasury yield is hovering around 5.25%, while September remains a very weak month for Treasuries, although historical seasonality suggests October has often been more supportive for bonds.
- U.S. data came in mixed: JOLTS job openings rose to 7.079 million versus 7.228 million expected and 7.271 million previously, while the Conference Board Consumer Confidence Index fell to 81.9 from 89.4, below the 89.0 forecast.
- At the same time, the oil market remains an important source of risk for inflation and sentiment. Brent futures are holding near $95 per barrel, while investors continue to monitor developments in the Middle East.
- Geopolitical risk linked to the Middle East conflict also remains in the background. Donald Trump once again suggested that he is trying to reach an agreement, but his comments have done little to reduce market scepticism over the prospect of a quick end to hostilities.
- Among individual stocks, CarMax is outperforming after reporting better-than-expected second-quarter results. AstraZeneca is also gaining after announcing a deal worth up to $2 billion related to cooperation on a new oncology treatment.
- On the weaker side, Fair Isaac came under pressure after reports that the U.S. housing regulator plans to change the way mortgage pricing and credit-scoring models are used, raising concerns about the company’s future market position.
- Friday’s labor-market data will be particularly important. A weaker report could strengthen expectations for a more dovish Fed stance, while stronger data could keep upward pressure on Treasury yields.
- Investors will also closely follow comments from Federal Reserve officials, including Austan Goolsbee and Christopher Waller, for additional clues on inflation, the labor market, and the future path of interest rates.
US100 Chart (H1 Interval)
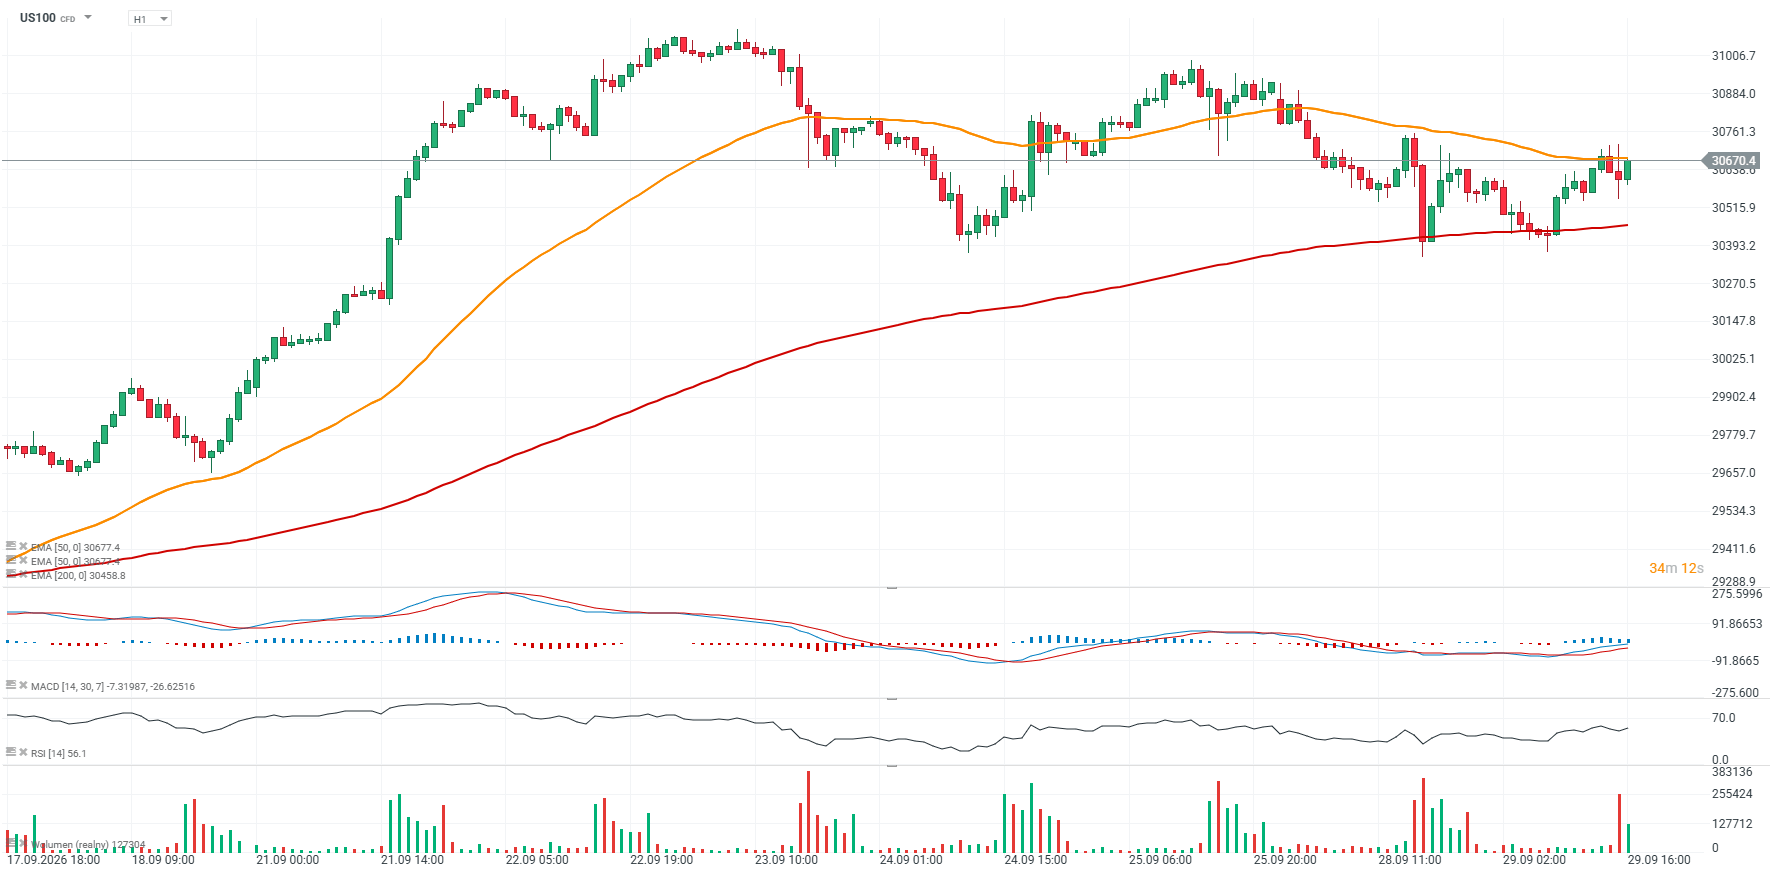
Source: xStation5
Among the largest Nasdaq 100 companies, the technology sector is clearly leading today’s gains, with Lumentum, ARM, Applied Materials, and KLA at the top of the table. On the weaker side are Palo Alto Networks, Datadog, and Cadence Design Systems, although their one-day declines remain relatively modest compared with their earlier gains. Walmart, Intuitive Surgical, and Autodesk are also underperforming and remain under pressure over longer time horizons as well. Overall, the market picture is mixed, but there is a clear rotation of capital toward selected technology and semiconductor stocks.
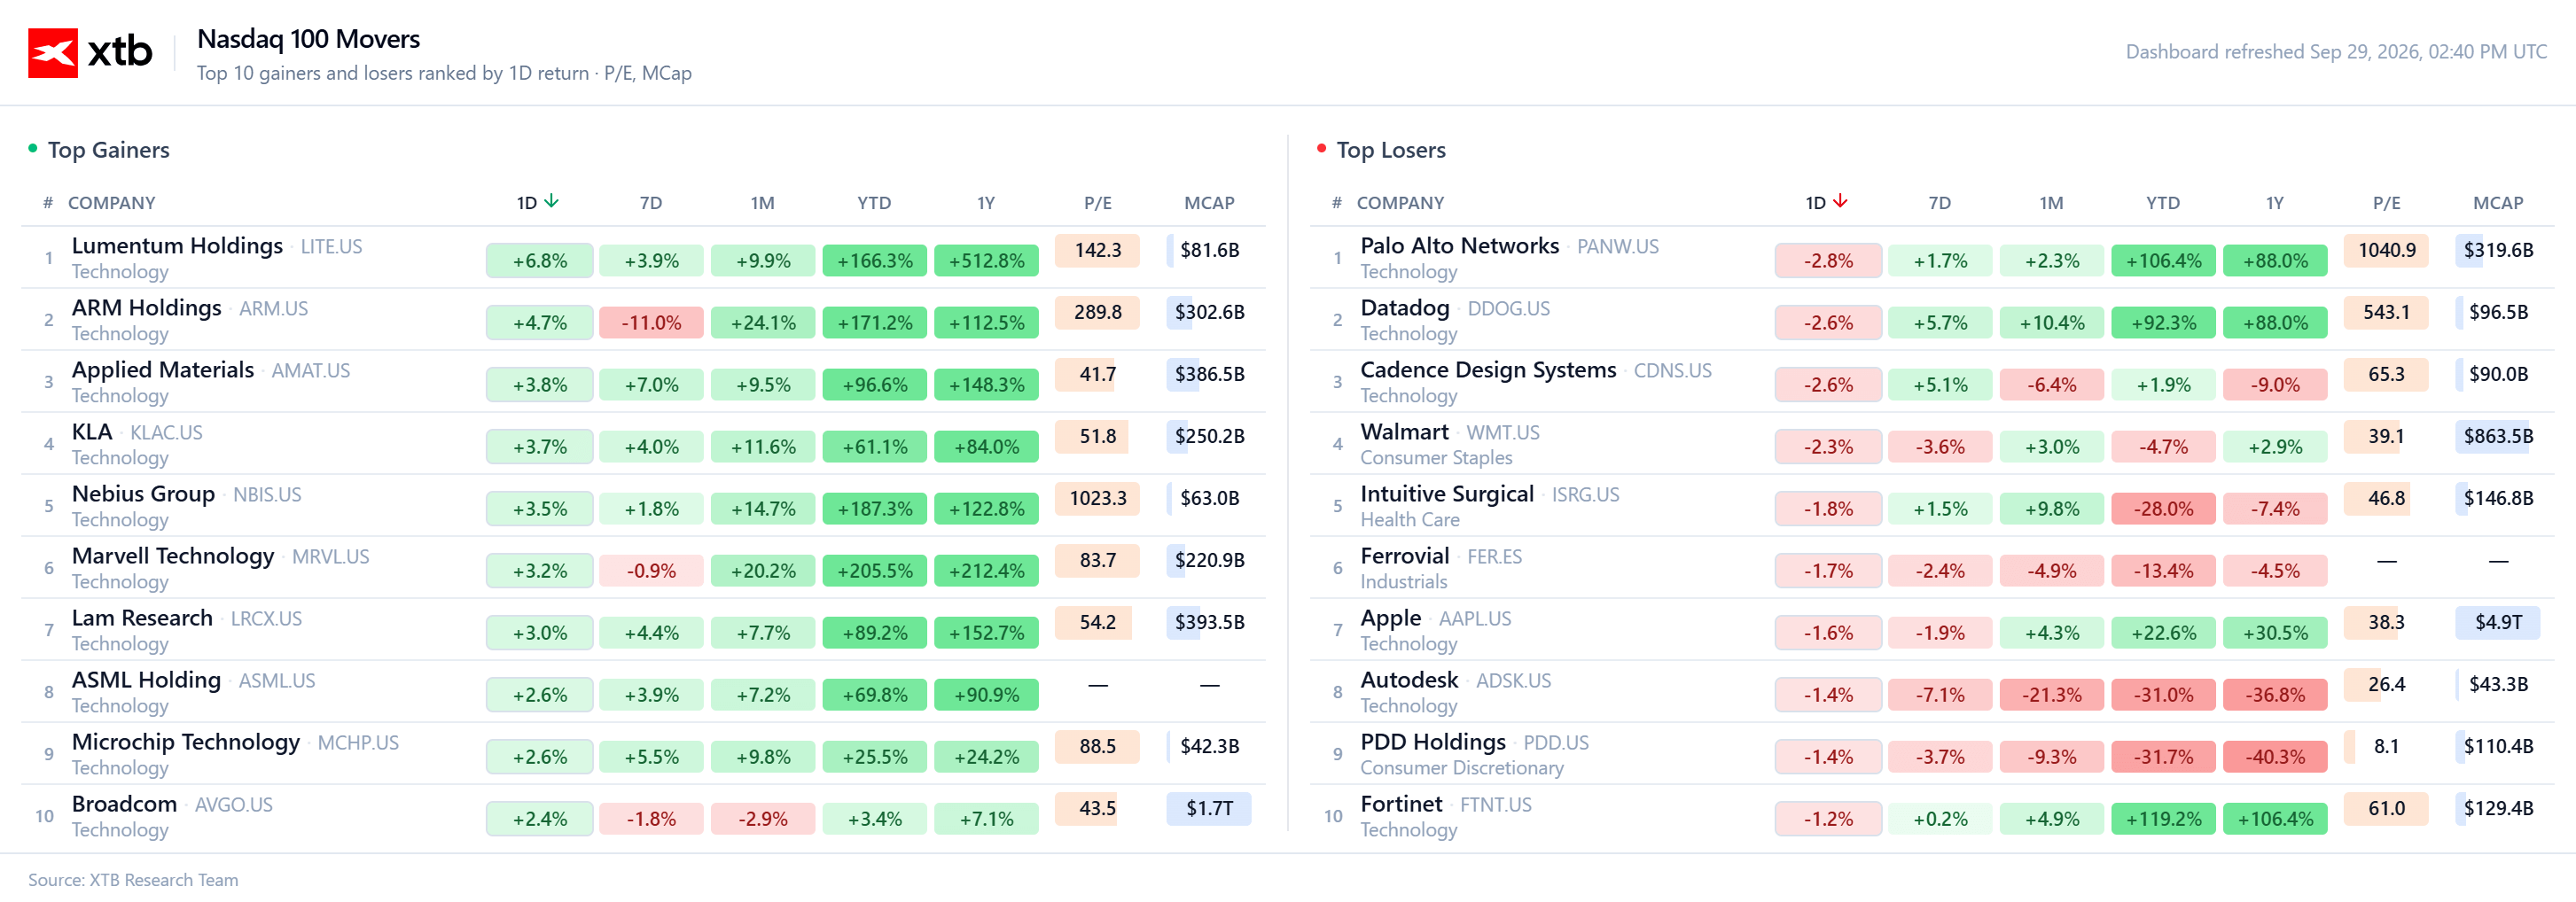
Source: XTB Research
U.S. Consumer Confidence Weakens Sharply
The Conference Board Consumer Confidence Index fell to 81.9 in September from 88.6 a month earlier, while economists had expected an increase to 89. Consumers’ assessment of current business conditions turned negative for the first time since September 2024, while perceptions of the labor market also deteriorated. Looking ahead, households expect both business conditions and employment to weaken over the next six months, while expectations for household income growth have also become less optimistic.
JPMorgan Downgrades XPeng
XPeng shares fell 4.2% on Tuesday, reaching a 52-week low of $9.51, after JPMorgan downgraded the stock from “overweight” to “neutral.” The bank remains cautious on the broader Chinese auto sector, citing weaker demand, rising input costs, and persistent structural challenges that could continue to weigh on the industry into 2027. JPMorgan also noted that while XPeng is developing advanced AI technologies for its vehicles, investors may be reluctant to assign significant value to those initiatives until they begin making a direct contribution to earnings.
Company News
- Fair Isaac (FICO) is an analytics and technology company best known for its FICO credit-scoring models, which are widely used by banks and the U.S. mortgage market. Shares fell 18% after the Federal Housing Finance Agency announced plans to simplify mortgage pricing and combine FICO Classic and VantageScore within a single pricing grid, which the market viewed as a potential threat to FICO’s competitive position.
- Summit Therapeutics is a biotechnology company developing cancer treatments, including ivonescimab and sonesitatug vedotin. Shares surged 18% after AstraZeneca announced a $2 billion investment and a strategic clinical collaboration, strengthening the perceived credibility and commercial potential of Summit’s pipeline.
- Bloomin’ Brands is a restaurant operator that owns chains including Outback Steakhouse and focuses on the casual dining segment. Shares gained 5% after JPMorgan upgraded the stock from “underweight” to “neutral,” citing operational improvements such as menu changes and a reduction in the number of tables assigned to each server during peak hours.
Fair Isaac (FICO.US) Share Price Chart, D1 Interval
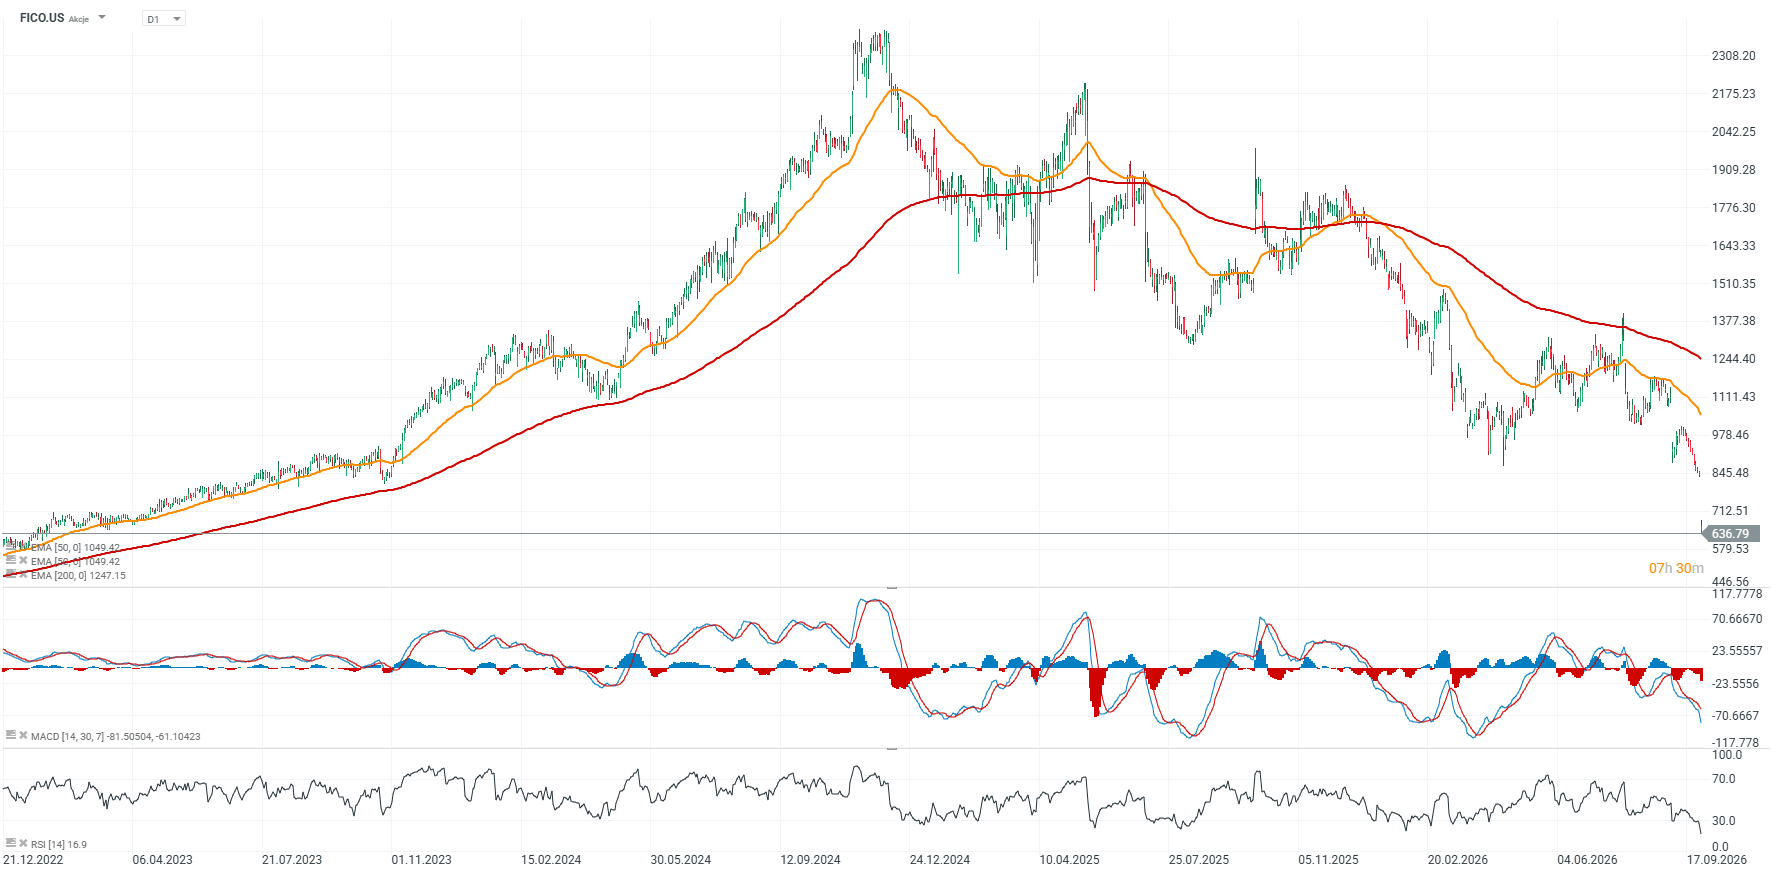 Source: xStation5


🚩 Oil extends losses


Wall Street: Does the S&P 500 Still Have Room to Rise?


AMD Goes Shopping: Is Its $8.2 Billion Investment a Good Move?

Chart of the day: Weather offsets high rollover on NATGAS (29.09.2026)
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.