


Wall Street opens lower, despite earlier hopes for a rebound after Nvidia’s results. In CFD trading, the Dow Jones is down about 0.7%, the S&P 500 about 0.3%, and the Nasdaq 100 also about 0.3%. Optimism following the chipmaker’s report is fading, and the market is returning to concerns about interest rates, as investors fully price in a December Fed hike. Yesterday the S&P 500 lost about 1%, and all 11 sectors declined. Yesterday the S&P 500 lost about 1%, and all 11 sectors declined.
Nvidia published its first report since Jensen Huang stepped down as CEO. Revenue rose 103% y/y to $115.8 billion, and the Q4 guidance is $130 billion, against expectations of about $125 billion. The company also raised its sales growth forecast for the next fiscal year from 70% to 75%. Part of the market feared that no guidance would be given at all, so its mere presence is reassuring. At the same time, Nvidia halted shipments of licensed Hopper chips to China. Despite that, and the after market rise of 3%, Nvidia quickly slides down to around -1%.
The second theme is so-called circular financing, meaning financing customers who then buy chips from Nvidia itself. Interim CEO Colette Kress spoke of “disciplined” and “rigorous” evaluation of future investments, commitments and guarantees. This sounds like a signal that the safety net under the entire AI ecosystem may become more selective. That matters because the financing needed for the AI buildout could reach as much as $8 trillion, and the question of who will provide it remains open. For now the market is reacting calmly, as neocloud stocks are rising after the results.
The results are pulling up the entire supply chain. South Korea’s Kospi is back above 5,000 points and closed the session about 2% higher, after gaining more than 3% at the open. Samsung Electronics and SK Hynix are gaining because Nvidia’s commitments to memory suppliers rose to $390 billion. In the US, Coherent, Lumentum, Credo, Micron, AMD and Broadcom, among others, are rising, gaining from about 3% to over 6%. The broader context, however, does not support full optimism: Nvidia is about 24% lower this month, bond yields are high, and the market fully prices in a 25 bp Fed rate hike in December. The next test for the AI sector will be Anthropic’s stock market debut tomorrow. The company is aiming for the top of, or above, the $70-78 per share range, which would imply a valuation of about $1.4 trillion.
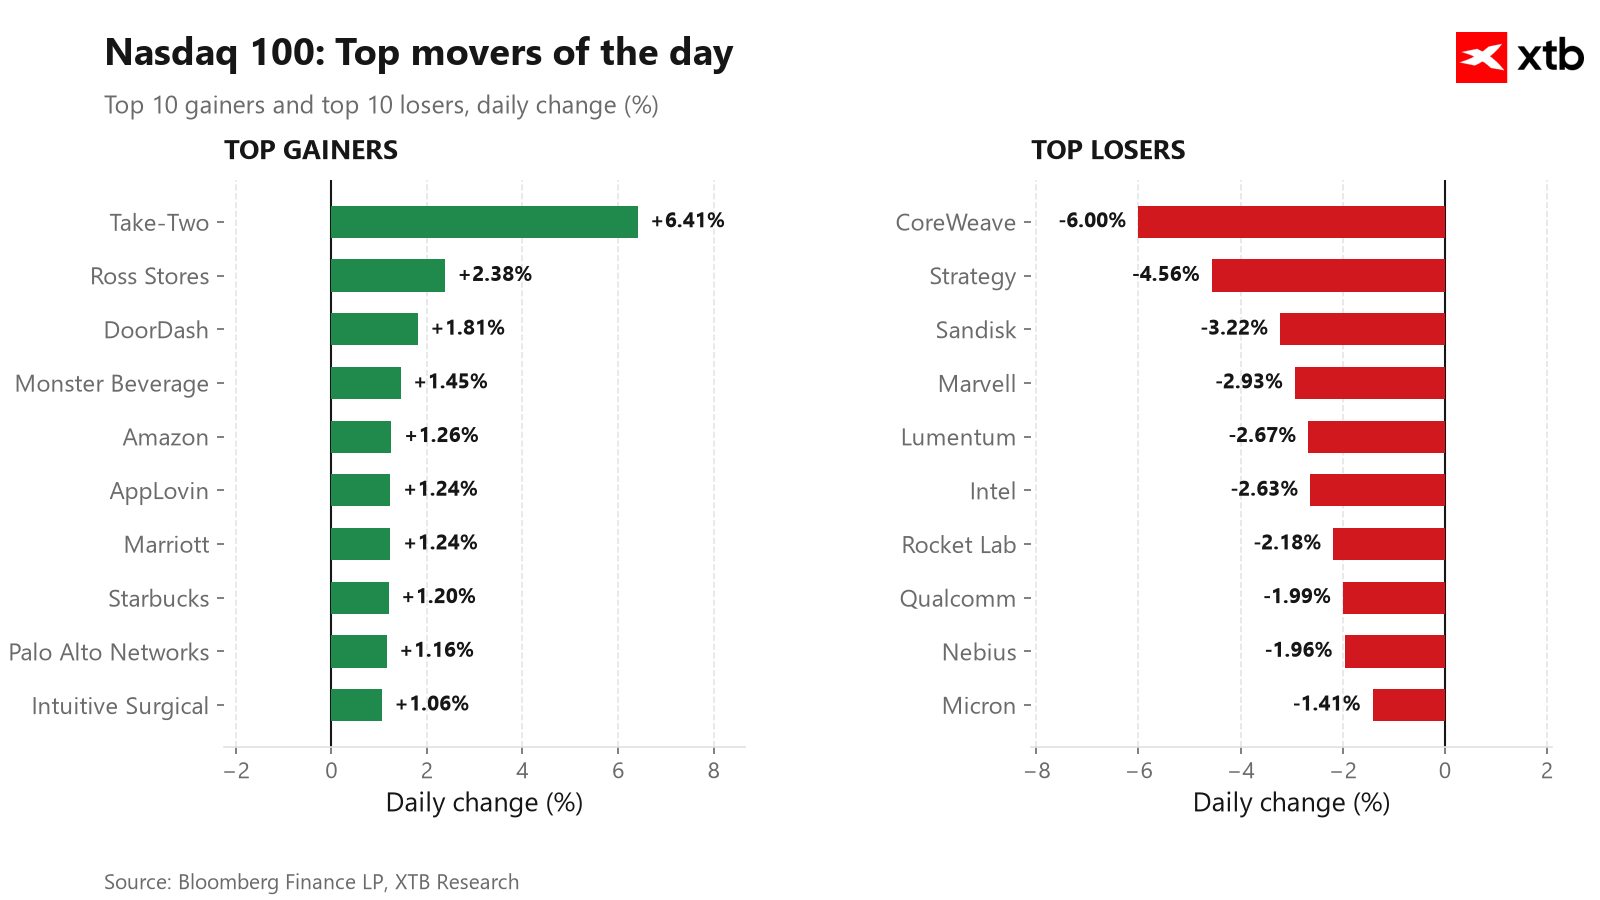
Chart 1 presents the biggest moves among stocks listed on Wall Street.
Company news
- Take-Two Interactive (TTWO.US): Reviews of Grand Theft Auto VI are outstanding. The game has a score of 99 on Metacritic, matching the record held by The Legend of Zelda: Ocarina of Time. Bloomberg called the title a “masterpiece,” and GameSpot gave it 10/10. The launch on PS5 and Xbox Series X/S is on Thursday at midnight local time, and the standard edition costs $79.99. Take-Two maintains its guidance of $8-8.2 billion in net bookings for the fiscal year, and CEO Strauss Zelnick said that pre-orders exceed initial expectations. Analysts estimate that sales in the first three days will reach about 20 million copies, while expecting about 40 million by the end of March 2027. The first sales figures may appear as early as Friday. (up about 6.5%)
- Bullish (BLSH.US): The crypto exchange beat expectations in Q3. Adjusted EBITDA was $35.6 million (42% margin), revenue was $84.4 million against forecasts of about $80 million, and management announced a share buyback program of up to 300million.Spottradingvolumesareweaker,however(32.1 billion versus $41.6 billion a year ago), and bitcoin itself is stuck around $64,000. (up about 5%)
- CoreWeave (CRWV.US): The GPU cloud provider is down reversing its earlier gains after Nvidia’s results. The company is one of the main beneficiaries of Nvidia’s guarantees to date, so the market is focused on whether Nvidia will limit its financial support and whether neoclouds can secure funding elsewhere. (down about 5%)
- Lowe’s (LOW.US): The home improvement retailer beat forecasts in Q3 (adjusted EPS of $3.10 versus about $2.90), but this was also helped by tariff refunds, and management lowered its full-year operating margin guidance while maintaining its EPS guidance. These assumptions imply a weaker Q4 than expected. (down about 3%)
- Applied Optoelectronics (AAOI.US): The maker of optical components for data centers is falling after announcing a stock offering program of up to $550 million. It is already the fourth such program this year, so investors fear dilution, despite record revenue and strong demand from AI data centers. (down about 10%)
Technical analysis US100 (D1)
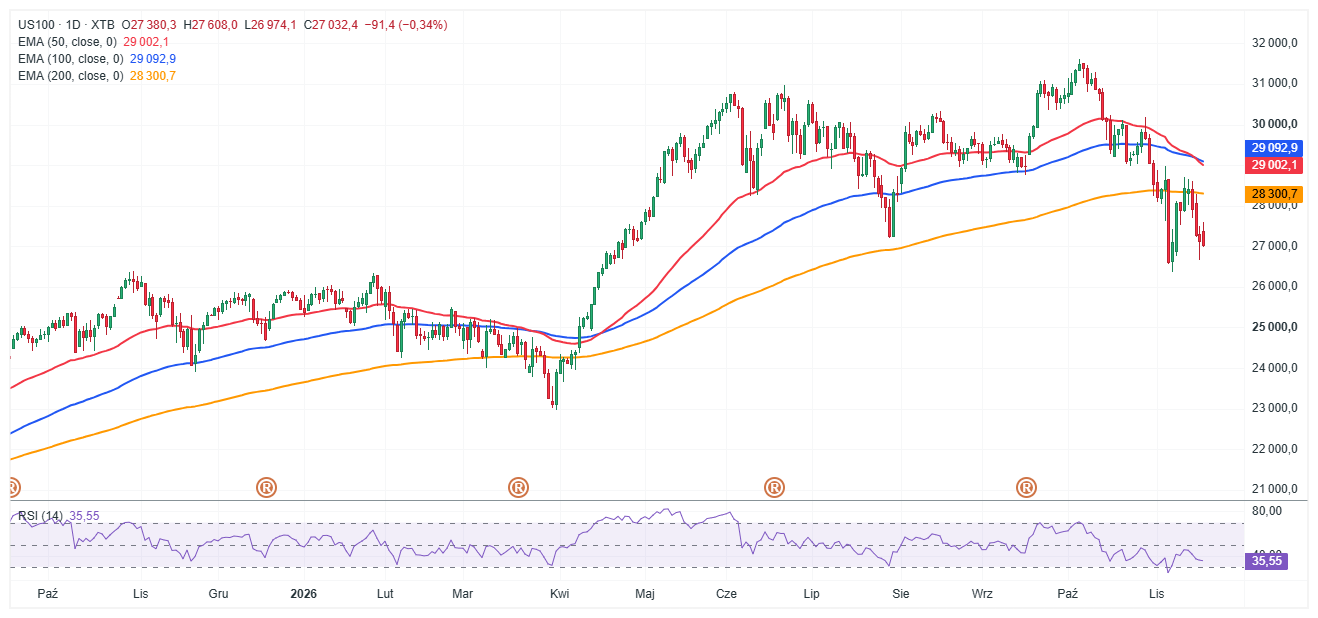
US100 is bouncing from a low around 26,400 points and is trading near 27,200 points, still clearly below all moving averages. The nearest resistance is the EMA 200 around 28,300 points, and higher up is the zone around 29,000 points, where the EMA 50 and EMA 100 run. The two averages have started to cross (the EMA 50 has dropped below the EMA 100), which worsens the medium-term picture. The RSI (14) is below 40 points, so momentum remains weak, but it has moved away from extreme oversold levels. If buyers defend the recent lows and the index returns above 28,300 points, the way to a test of 29,000 points will open. If the rebound fades, a renewed test of the low at 26,400 points will be very likely. Source: xStation5
Calendar for the rest of the session
- 20:00 - Minutes from the October FOMC meeting (the market is looking for how broad the support is for further hikes)
- 20:30 - Speech by John Williams (Fed)



Market Wrap: Stocks under pressure, Iceye reaches for Avio



Daily Summary: Tech Stock Selloff Weighs on Markets, Fed Outlines AI Scenarios


US OPEN: Tech selloff continues ahead of Nvidia earnings and Anthropic’s debut

Daily Summary: PPI Inflation slows down, but EURUSD approaches 1.10
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.