

- US500 and US100 futures edge lower as cooling diplomatic hopes halt recent market rallies.
- Tesla and SpaceX confirm committees to evaluate a potential merger valued at 3.5 trillion USD.
- Super Micro Computer shares jump over 12 percent following strong preliminary revenue figures driven by AI demand.
- Netflix drops nearly 5 percent after issuing a disappointing revenue forecast for the fourth quarter.
- Futures on US500 and US100 are slightly on the defensive (-0.20% and -0.18%, respectively) during the cash market open, testing key technical resistance after market diplomats cooled hopes for an immediate agreement between Washington and Tehran.
- Tesla (TSLA.US) gains 2.31%, and SpaceX stock surges by over 8% in pre-market trading after Elon Musk confirmed the establishment of special committees to evaluate an unprecedented merger between the two giants, estimated to be worth $3.5 trillion.
- Super Micro Computer (SMCI.US) jumps over 12% driven by impressive preliminary revenue powered by AI infrastructure demand, while Netflix (NFLX.US) drops nearly 5% following a disappointing revenue forecast for Q4.
Wednesday's opening on the New York floor is taking place in an atmosphere of anticipation and a slight cooling of yesterday's enthusiasm. Markets attempted to extend the rally driven by reports of a compromise proposal by Qatar and Pakistan regarding a US-Iran agreement, but denials from diplomats directly involved halted the wave of aggressive buying.
A tone of moderate risk reduction (risk-off) dominates the trading floor ahead of key Big Tech earnings releases scheduled for the evening, forcing a sector rotation toward defensive sectors and companies with confirmed cash flows. An additional factor dampening sentiment remains US debt yields, which stay at elevated levels awaiting Friday's PMI readings.
Investors are reluctant to take on excess risk ahead of financial reports from Tesla and Meta, which will provide answers on whether massive capital expenditures on tech infrastructure are yielding tangible returns.
Diplomatic stalemate in the Middle East and rotation in the shadow of Big Tech
Conflicting geopolitical signals from the Middle East became the main driver of sentiment swings in the broader market. Following yesterday's optimistic reports from Al-Arabiya regarding a potential breakthrough in Washington-Tehran relations ahead of the upcoming midterm elections, equity markets began pricing in a de-escalation scenario that would ease the inflation path and give the Fed room for a softer monetary stance. However, these hopes were partially extinguished by diplomats directly involved in the talks, who emphasized that a final agreement remains far off.
Paradoxically, despite reports of military incidents and mining of routes in the Strait of Hormuz by the Iranian Revolutionary Guard, energy commodities experienced a sharp sell-off. Brent crude dropped nearly 3.9%, and US natural gas extended its weekly decline to over 13%, driven by weather conditions. In the bond market, 10-year US Treasury yields stabilized around 5.13%, with 2-year yields at 4.80%, while the effective federal funds rate stood at 3.88%. In this environment, Wall Street indices are entering a wait-and-see phase:
- US500: trading around 7,769 pts (-0.20%); the index is consolidating just below key technical resistance, with investor caution offset by strong openings from select semiconductor stocks.
- US100: around 29,841 pts (-0.18%); the tech sector balances between euphoria over preliminary results from SMCI and SpaceX, and the sell-off in Netflix along with caution ahead of Meta Platforms' evening report.
- US30: around 52,728 pts (-0.20%); traditional blue chips give back part of yesterday's gains under pressure from declines in the industrial and automotive sectors.
- US2000: trading near 2,802 pts (+0.34%); small caps demonstrate relative strength today, gaining on local positioning for cheaper financing in the event of easing commodity price pressure.
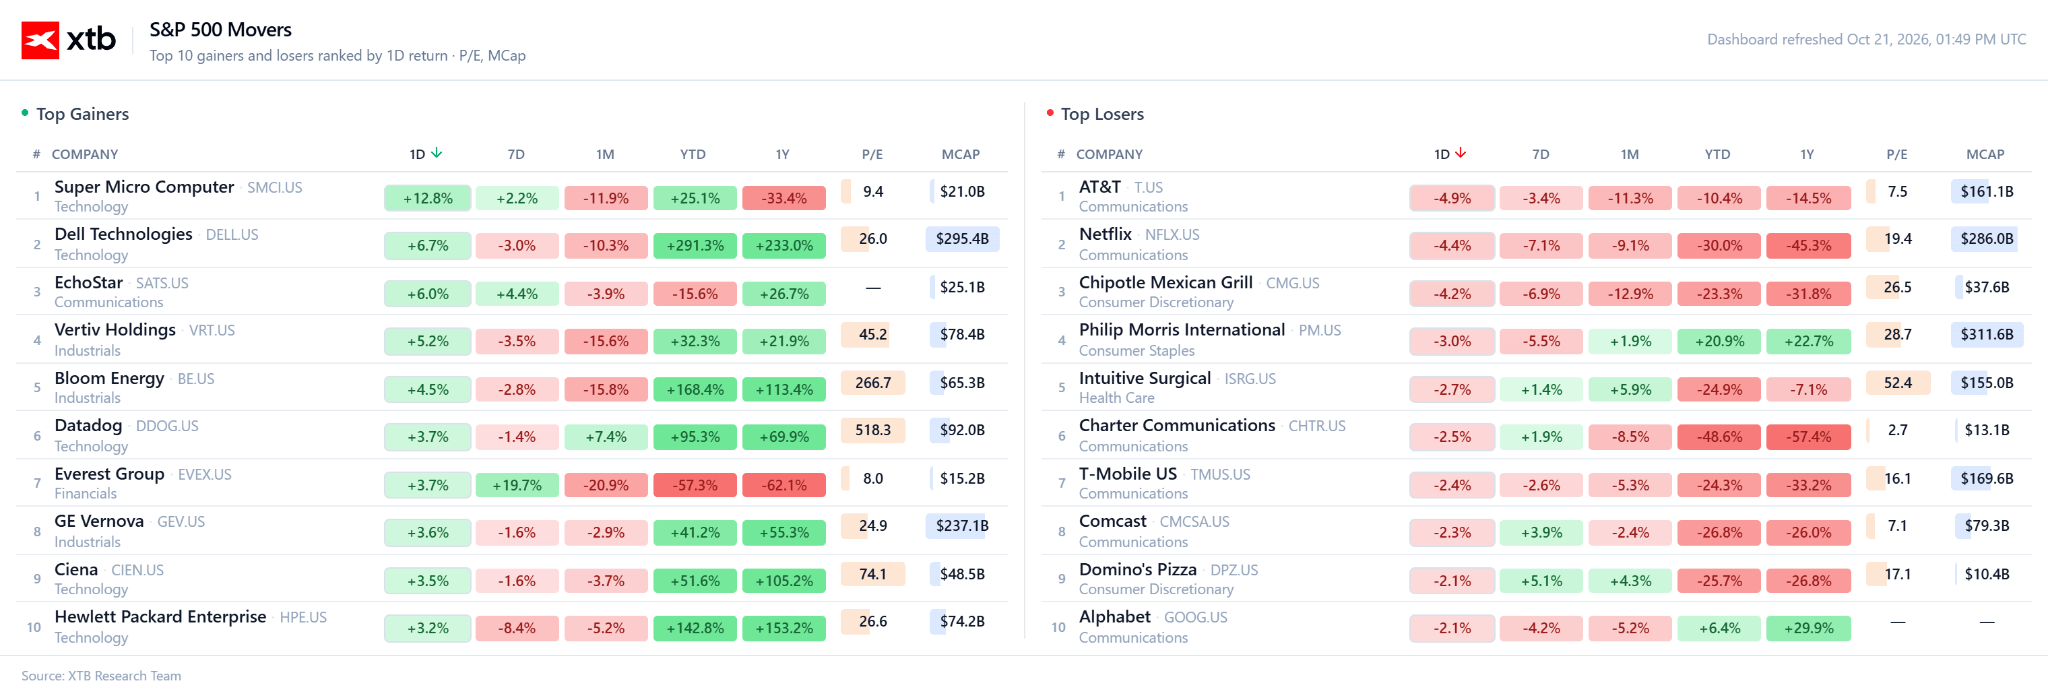 Netflix is one of the worst-performing stocks during Wednesday's open. SMCI and Dell are rising strongly. Source: XTB
Technical Analysis of S&P 500 (US500)
On the daily chart for the US500 contract, we observe stabilization near recent record highs. Quotes sit just above the 50-period simple moving average (SMA 50: 7,738.3 pts) and slightly below the 25-period average (SMA 25: 7,785.4 pts), confirming consolidation within a short-term trend. Technical indicators suggest neutral sentiment: the RSI (14) indicator is around 50.8 pts, while MACD remains in a mild downward correction, signaling a wait for a decisive directional move.
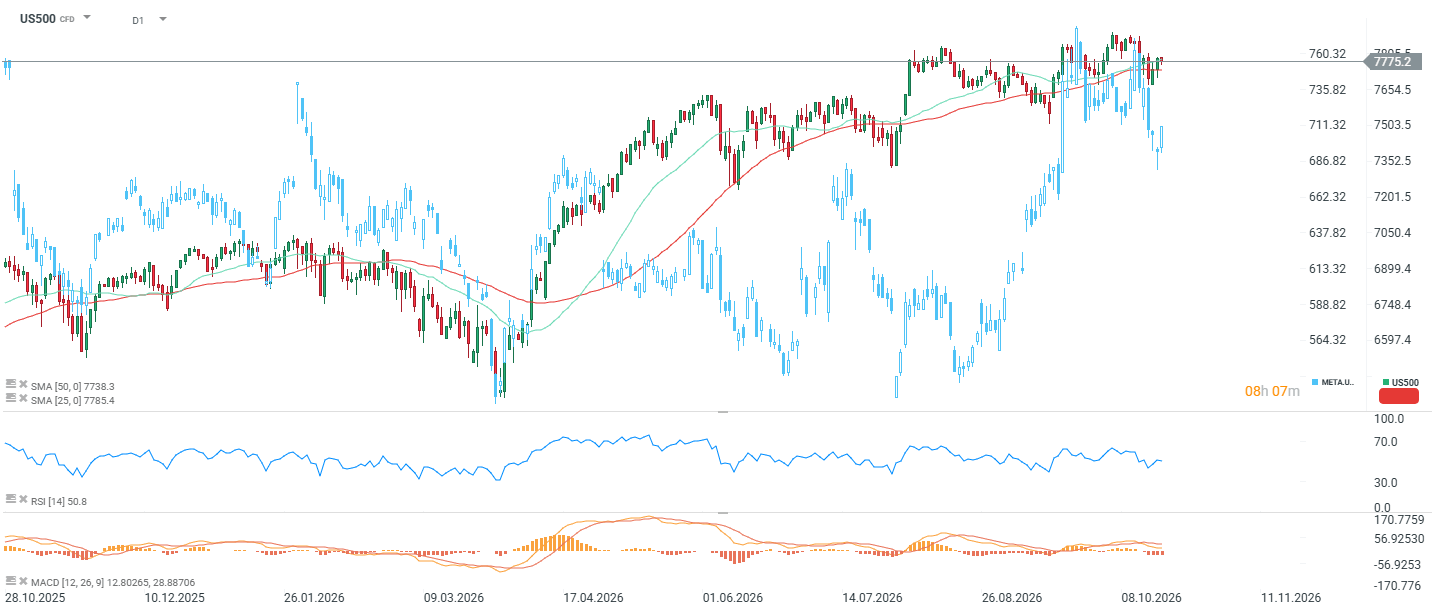
The technical setup outlines two clear scenarios for upcoming sessions:
1. Bearish scenario (baseline in the short term): Rejection of local resistance at 7,775–7,805 pts and a return below the 50-period moving average (7,738.3 pts) will open the door to a deeper correction toward support levels visible on the chart: the 7,654.5 pts zone and a key low at 7,503.5 pts.
2. Bullish scenario: A sustained breakout and daily close above resistance at 7,805.5 pts will open the path to new all-time highs and a continuation of the uptrend toward higher resistance levels.
Key Company News
- Mega-merger in Musk's empire: Tesla (TSLA.US) and SpaceX (SPCX.US): Shares of Tesla rise by 2.31% (around $382), while previously private shares of SpaceX surged over 8% in pre-market trading. This move came after Elon Musk confirmed the formation of independent committees to explore a merger of both entities with a combined valuation of $3.5 trillion. Markets also enthusiastically received SpaceX's Q3 results, where the company reported a surprise operating profit driven by the expansion of AI services. However, Tesla's valuation remains demanding (P/E ratio at 387.95 with a consensus target price of $422.40). Tesla will report earnings after the market close today.
- Infrastructure boom in servers: Super Micro Computer (SMCI.US) and Nvidia (NVDA.US): Super Micro Computer shares jump 12.20% after reporting preliminary fiscal Q1 revenues that comfortably beat market expectations due to insatiable demand for AI compute clusters. Meanwhile, Nvidia gains 1.63% (around $220; RSI at a moderate 40.89 signals room for upside), supported by Jensen Huang's presentation in Berlin revealing shipping-ready server racks for the Vera Rubin architecture and an alliance with Amkor in South Korea.
- AMD (AMD.US): Shares of the semiconductor maker advance 2.54% (around $548), recovering from earlier consolidation. Demand returned on optimism sparked by SMCI and reports of surging demand for HBM memory.
- Netflix (NFLX.US): Shares of the streaming giant tumble nearly 5% (to around $65). Investors penalized the company for disappointing Q4 revenue guidance, fueling concerns that current subscriber growth drivers are exhausting themselves. Despite the drop, consensus analyst price targets remain high near $115.56, seeing an entry opportunity with a P/E ratio of 19.37 and RSI near 40 points.
- Weakness in telecoms: AT&T (T.US): The company's stock falls 5.30% in response to a quarterly report where postpaid mobile subscriber additions missed Wall Street estimates. An additional drag is growing margin pressure risk from Starlink Mobile's potential entry into the wireless market.
- Pressure in healthcare: Abbott Laboratories (ABT.US) and Intuitive Surgical (ISRG.US): Abbott loses 3.80% after cutting the upper end of its full-year earnings guidance and announcing plans to spin off its nutrition segment into a separate public company. Simultaneously, Intuitive Surgical plummets 6.70% after releasing data pointing to a slowdown in da Vinci robotic procedure growth in US hospitals.
- Clinical trial breakthrough: Roivant Sciences (ROIV.US): Shares of the biotech firm soar 8.80% after confirming that its experimental drug brepocitinib met primary endpoints in both key Phase III studies (CLARITY-1 and CLARITY-2) in patients with non-infectious uveitis.
- Automotive sector under pressure: General Motors (GM.US): The Detroit automaker's stock drops 0.70% after the opening bell (losing up to 7% intraday within the S&P 500), aligning with broader margin concerns for legacy automakers amid price wars and government subsidy uncertainty.
Retail Investor Sentiment
- Hype around Tesla and SpaceX merger: Communities on r/wallstreetbets and r/stocks are focused entirely on the combination of Elon Musk's assets. Retail investors mostly view it as the "deal of the century," though warning voices point to shareholder dilution and pulling Tesla into capital-intensive space programs.
- Harsh reality check on Netflix: Long position holders in NFLX stock face steep losses post-earnings. Forums are dominated by disappointment over slowing business momentum, and "catching a falling knife" memes dominate daily discussion threads.
- AI capex bubble fears vs. excitement over Anthropic figures: Disclosure of Anthropic's compute expenditure plans (up to $750 billion) triggered fierce debate over the sustainability of the tech rally. Retail traders highlight massive cash burn by AI startups, contrasting with short-term euphoria driven by SMCI's stellar report.
- Aggressive buying on leveraged ETFs: Social platforms show a return to extreme leverage in tech funds (including SOXL), indicating that retail investors continue to aggressively buy every local dip in the chipmaker segment.
Economic Calendar
- Today after market close: Quarterly earnings from tech titans – Meta Platforms (META.US) and Tesla (TSLA.US) (market focus will center on AI capex spend and SpaceX merger details).
- Today after market close: Financial reports from Texas Instruments (TXN.US) and IBM (IBM.US), crucial for evaluating the health of the semiconductor industry and corporate IT spending.
- Friday, October 23: Flash manufacturing and services PMI readings for the US (the key macroeconomic release of the week for assessing economic slowdown risk).


Tesla Preview: Will Robotaxis Save Earnings?

SpaceX Results: Can Starlink Carry the AI Revolution?

CoreWeave: Record Demand Collides with Crushing Costs


Chart of the Day: US100 (Nasdaq 100). Rebound in AI trade vs. weakening technical picture
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.