


US indices are continuing the strong downtrend that began in early October. Friday’s session opens with technology indices down by around 1%. Russell 2000 and Dow 30 futures are holding up slightly better. Futures tracking the NASDAQ 100 are now about 17% off the peak. This marks the second such strong downtrend in recent years for the index, second only to the 25% drawdown reached after tariffs were announced during the US “Liberation Day”.
Yesterday’s Anthropic IPO was an important test for Wall Street, and it appears to have failed it. During the first session, Anthropic shares rose 17% from the offering price, reaching USD 97. However, in after-hours trading the stock is already down more than 12%, sliding toward USD 86.
A meaningful impulse has appeared in the bond market. The sell-off in commodities and equities is supporting bond prices, and US 10-year yields are falling below 5% (about 4.98%).
This sentiment is not shared by analysts at major investment banks. Goldman Sachs and Morgan Stanley analysts estimate EPS growth slowing to 11% while the forward P/E multiple remains around 18, which implies the S&P 500 near 8,700 points by the end of 2027. Bank of America is more pessimistic, with strategists pointing to “post-bubble” price action and drawing parallels with 1999–2000, when the Fed raised interest rates to the point of triggering a recession.
The panic sell-off in technology assets is not the only pressure on markets. Saudi Arabia’s capital, Riyadh, was hit by a missile attack by the Houthis. The reaction in fuel and gas markets is limited, as traders are pricing in rising inventories. Natural gas in Europe is up about 3%, while Brent crude holds around USD 91.
Company news
- Intuit (INTU.US): The accounting software maker is down about 9% after cutting its annual guidance. The decline is said to be driven by pressure from AI platforms in the company’s key markets.
- Ross Stores (ROST.US): The retailer lowered its outlook for the next quarter, with management citing cost pressure weighing on margins. Shares are down about 4%.
- SK Hynix (SKHY.US): The company decided to convert bonds and buy shares in Kioxia, one of its main rivals in the NAND chip segment. After the transaction, SK Hynix becomes the largest single shareholder with an indirect stake of 14%.
- PayPal (PYPL.US): The stock is down about 4% after the company announced changes to key roles, including the CFO and the head of the division responsible for consumer financial services and Venmo.
Technical Analysis US100 (D1)
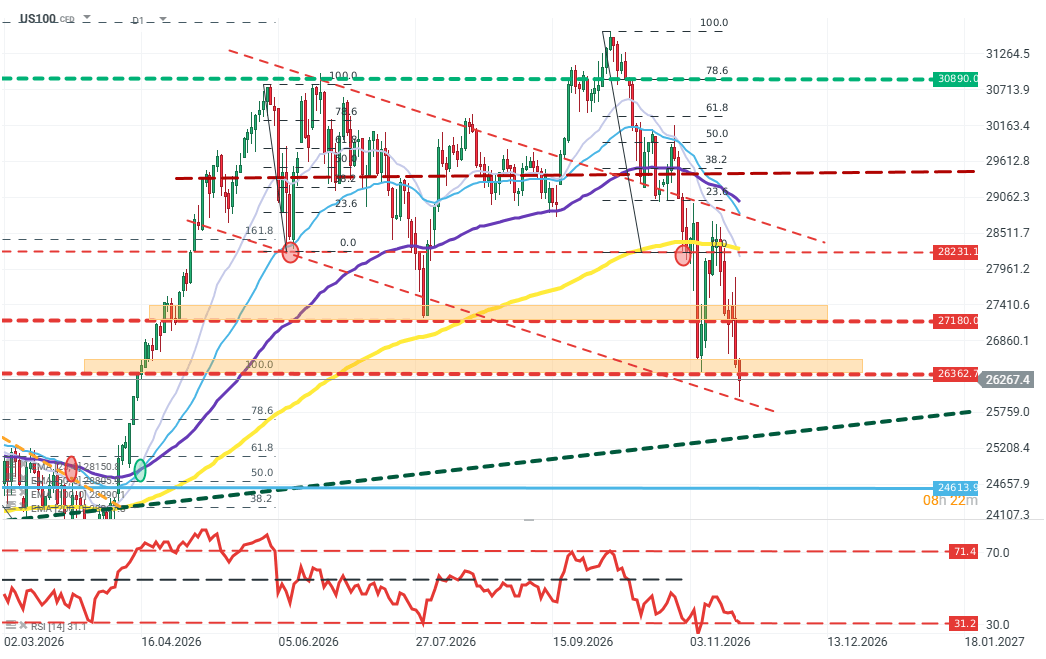
The daily technical picture points to continued seller dominance and a gradual deterioration in the trend structure. After an unsuccessful attempt to hold gains around 31,300 points, the index entered a phase of a sharp correction, breaking successive moving averages and the EMA200. A sequence of lower highs and lower lows, combined with prices remaining below a falling trendline, confirms the sellers’ advantage. The break below the support zone around 27,300 points is particularly important, as it opened the way for a test of the next demand area near 26,360 points. A sustained break below it would increase the likelihood of deeper declines toward around 25,500, where a long-term rising support line runs. At the same time, RSI(14) hovering near 31 points signals the market is approaching oversold territory, which, together with the pace of the recent sell-off, increases the probability of a short-term rebound. Source: xStation5
Macroeconomic data
- Half an hour after the market open, the University of Michigan consumer sentiment data will be released in the US. The market expects an improvement from 48 to 51.5.


Market Wrap: Global stocks post 7th consecutive session of losses, Anthropic failed to reassure the market (20.11.2026)
Market Wrap: Anthropic Lifts Sentiment, but a Hawkish Fed Keeps the Dollar High


Palo Alto Earnings: Another Record Riding the Cybersecurity Crisis Wave



Morning Wrap: Time for the largest stock market debut in history (19.11.2026)
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.