

- US stock index futures start trading positively, led by technology and AI infrastructure sectors.
- SK Hynix reports AI memory production capacity is sold out through 2029, boosting sector optimism.
- Markets price a 10% probability of a rate change at today's Federal Reserve meeting.
- WTI crude oil rises 1.4% above 101 USD per barrel amid growing geopolitical risks.
- Vertiv shares jump 14% after the company raises its full-year earnings guidance.
Futures on US stock indices start Wednesday’s trading in moderately positive sentiment. The tech-heavy US100 is leading up with moderate gains, up 0.4%, while the US500 adds only 0.2% and the US30 remains near yesterday’s close. The main driver of the moves higher remains technology companies and AI infrastructure producers, supported by very strong results from South Korea’s SK Hynix.
- The HBM memory maker reported that its AI-related production capacity is sold out through 2029. This statement strengthens expectations that investment demand for computing infrastructure will remain high in the coming years.
- Optimism in the sector is further supported by reports that OpenAI plans to buy TPU processors from Google. Positive sentiment is also spilling over to US semiconductor and memory makers.
- Despite gains in the tech sector, investors remain cautious ahead of the Federal Reserve’s decision this evening. The futures market prices the probability of a rate change at today’s meeting at just under 10%, assuming the range will remain at 3.75 to 4.00%.
- The Fed Chair’s press conference may matter more, as investors look for guidance on a potential tightening of monetary policy in December.
- In commodities, the geopolitical risk premium is rising again. WTI crude oil is up 1.4%, moving above $101 per barrel. The increase follows reports of US warnings to allies in the Persian Gulf about the possibility of an intensified military operation after the midterm elections.
- After the close today, Alphabet, Microsoft, and KLA Corporation will report quarterly results. Investors will focus especially on the pace of AI infrastructure expansion, cloud services profitability, and planned capex. High expectations for monetizing technology investments increase the risk of sharp price reactions.
Company news:
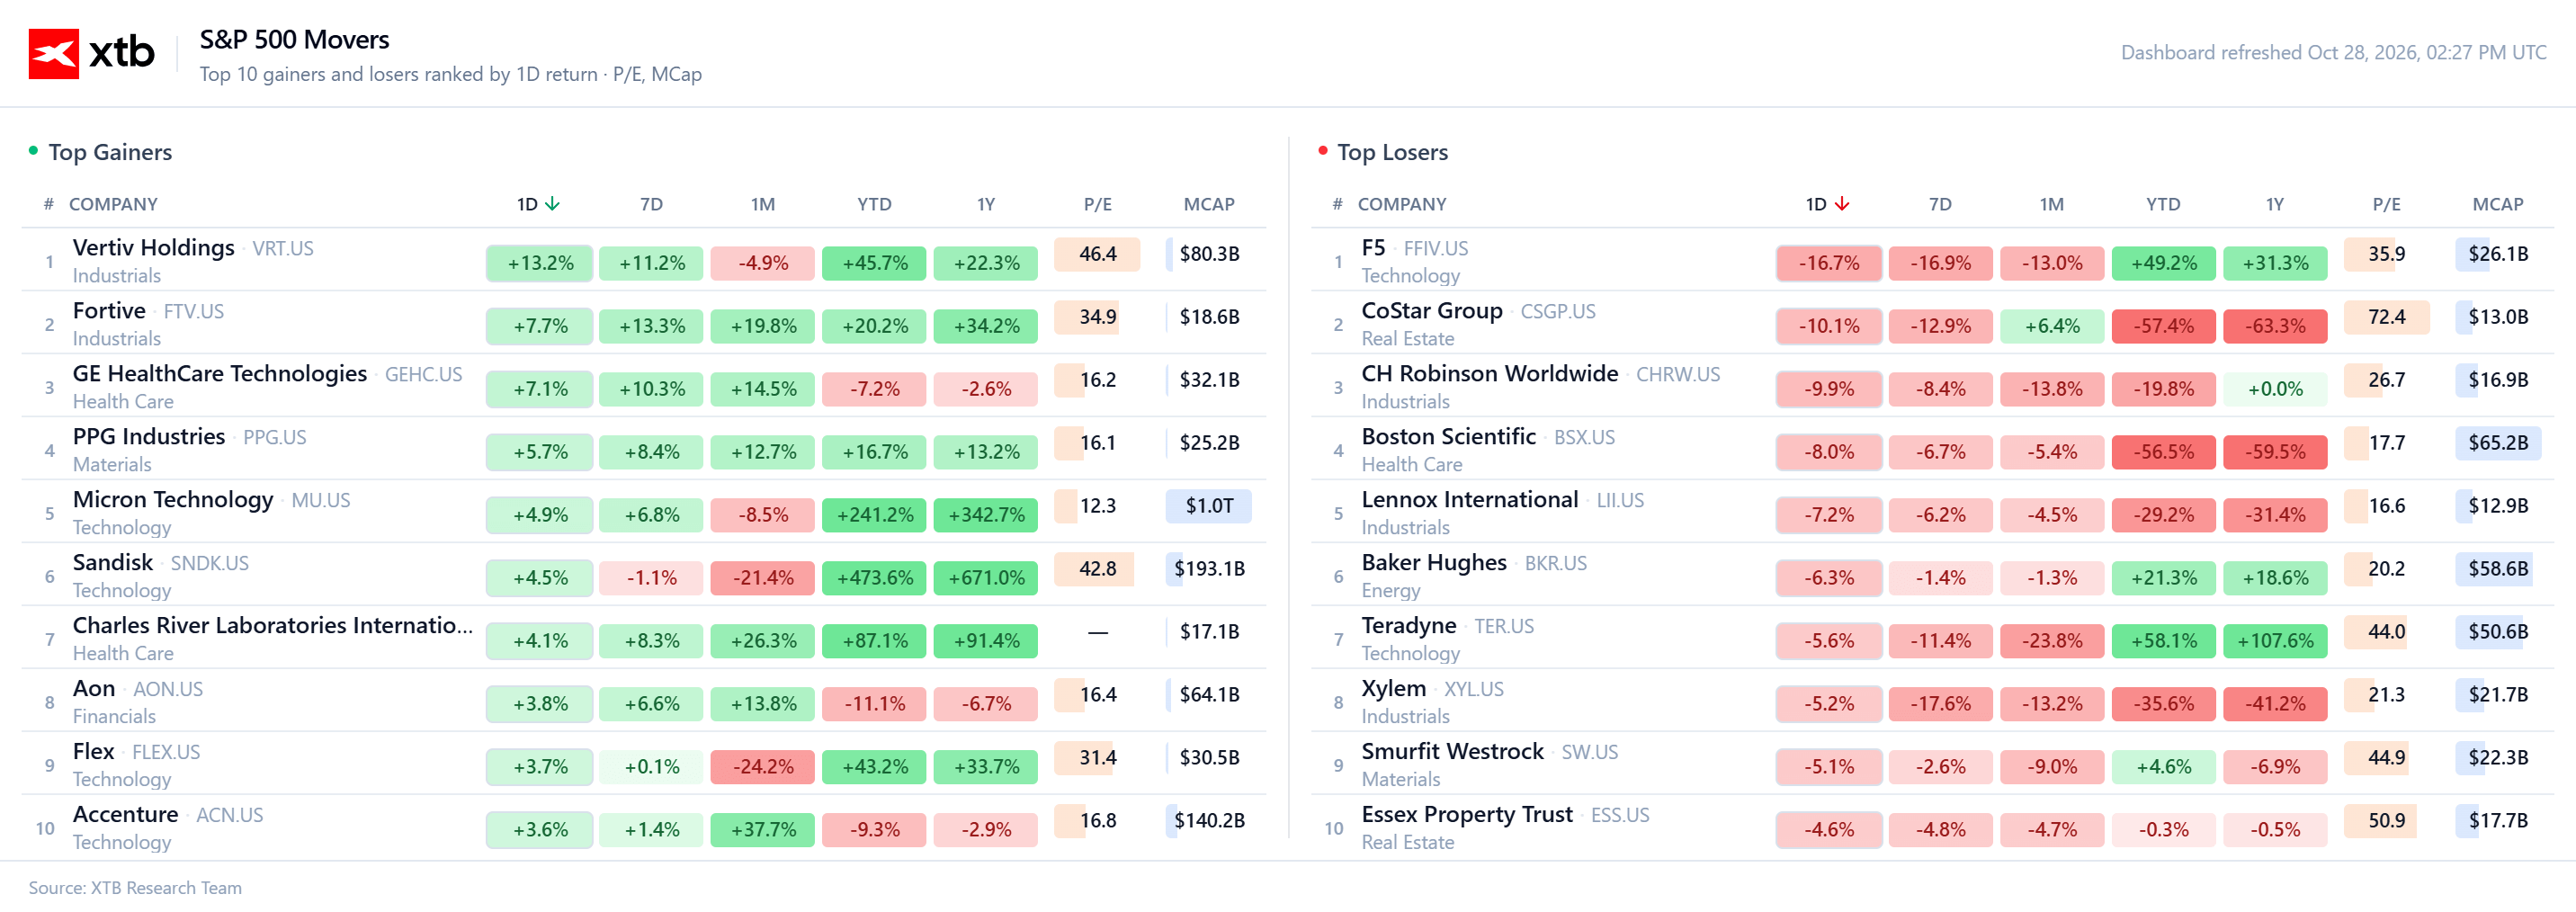
- Vertiv Holdings (VRT.US): Shares rise 14% after the company raised its full-year earnings per share guidance well above consensus. The data center power and cooling systems maker reported more than 100% growth in orders. Positive sentiment also extends to other AI infrastructure suppliers.
- Alphabet (GOOGL.US): The stock gains 1.2% on reports that OpenAI plans to purchase TPU processors. The deal could strengthen Google’s position in the AI computing infrastructure market.
- Microsoft (MSFT.US): Investors are awaiting results after the session, with special focus on Azure’s momentum. Consensus assumes the segment’s revenue will rise 45% year over year in constant currency. The company trades at a P/E of about 29.5x and has 68 buy recommendations.
- Ultralife (ULBI.US): Shares surge 145% after news that EnerSys will acquire the company for $16 per share in cash.
- Enphase Energy (ENPH.US): The stock drops 16% after the company presented disappointing guidance for Q4. Management points to the negative impact of high interest rates on consumer demand. Analysts are pushing expectations for a lasting recovery in the solar market out to 2027. Declines also include SolarEdge, down more than 5%, and Sunrun, whose shares fall about 2%.
- Boston Scientific (BSX.US): Shares fall 8% after the company issued a full-year adjusted net profit outlook below Wall Street expectations. The disappointment is also weighing on the broader medical devices sector.
- F5 Inc. (FFIV.US): Shares drop 17% after weaker than expected profit guidance for the first quarter of the fiscal year.
Technical analysis: US100 (D1)
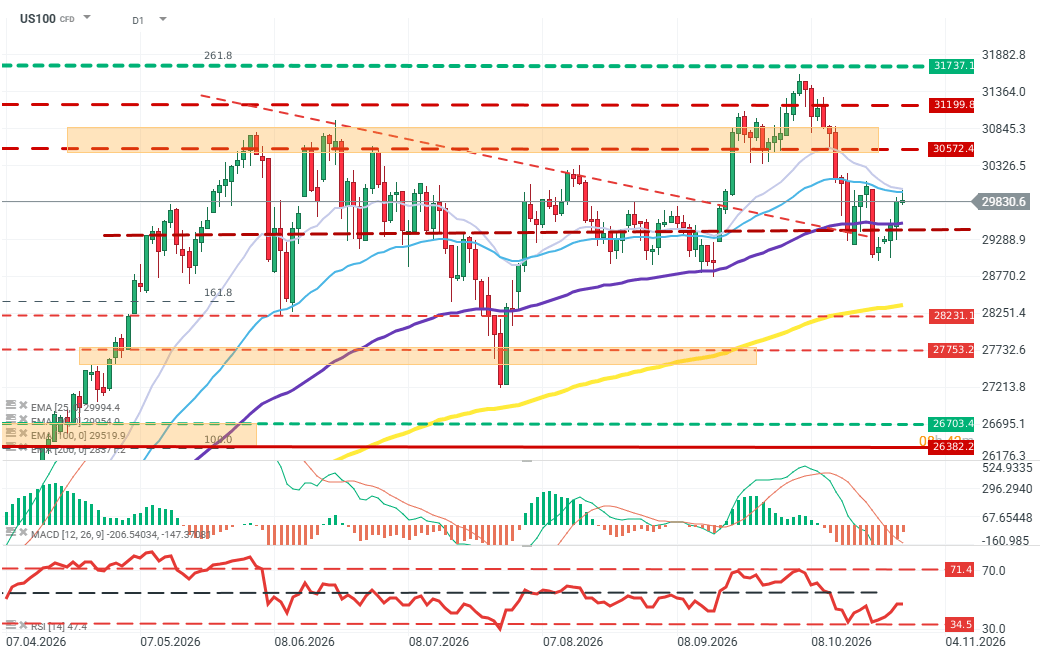
On the price chart, we can see an attempt to rebound after a strong correction from the October highs near 31,700 points. Prices have moved back above the key support at 29,300 points and are now testing the 29,800 to 30,000 zone, where the short-term moving averages EMA25 and EMA50 are located. A sustained breakout above this area could open the way for a retest of resistance around 30,570 points, and then 31,200 points. The bullish scenario is supported by the RSI bouncing from near-oversold levels, although its current reading around 47 still indicates no clear advantage for buyers. At the same time, MACD remains in negative territory, signaling persistent downward pressure. Failure to reclaim the moving averages would increase the risk of another test of support at 29,300 points, and a break below it could deepen the correction toward about 28,230 points, where another important technical zone lies. Source: xStation5
Macroeconomic data:
- At 13:30, US wholesale inventories for September will be published. Market consensus expects a 0.5% month-over-month increase.
- At 19:00, the Federal Reserve will announce its interest rate decision. The market expects the benchmark range to remain at 3.75 to 4.00%. At 19:30, the Fed Chair’s press conference will begin and may be significant for the bond market, the dollar, and US equity indices.

BREAKING: Bank of Canada hikes for the first time in 3 years but signals caution on further moves


Market Wrap: Deutsche Bank, UBS, and Santander earnings in the spotlight 🏛️

RBNZ surprises markets: New Zealand Dollar slumps after unexpected rate decision ✂️

Morning wrap (28.10.2026)
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.