


Broad indices are posting meaningful corrections, driven by mounting doubts about the profitability of the investment thesis concentrated around AI. The US market is performing moderately better than most of its developed market peers. Losses at the Wall Street open are hovering around about 0.5 percent and are focused on the technology sector. US100 futures are down about 0.8 percent. US30 and US2000 are doing notably better, holding near the previous close.
- Brent crude is back near 110 dollars, and European natural gas futures have reached 90 euros for the first time since 2022. The Houthi movement continues attacks focused on Saudi infrastructure, and the Strait of Hormuz remains under intermittent fire from Iranian forces.
- Donald Trump and the US administration are facing increasingly strong, bipartisan opposition to attempts to normalize trade relations with Russia. Efforts to increase trade volume between Russia and the US are also hampered by Ukraine’s regular strikes on port and pipeline infrastructure, which neutralizes the limited supply-side potential of this trend.
- The redeployment of additional vessels toward the Middle East, along with heightened activity by Israeli and Iranian air defense forces, points to the possibility of another escalation episode, adding an extra premium to commodity prices.
- Korean company Elice Group is down 32 percent in its market debut. The company’s disastrous entry adds another catalyst for sell-offs in the AI sector.
- Publications from major investment firms, including Societe Generale and Goldman Sachs, indicate that despite solid fundamentals, protective positioning against further declines in the AI industry is increasing.
Strong gains in the broader US market today are mainly being posted by energy and healthcare stocks, supported primarily by fundamental releases from the equity and commodity markets. The weakest performers are mainly AI and semiconductor companies, with particular pressure on firms with a more one-dimensional exposure to the AI boom.
Key for short-term investor sentiment in the US market will be today’s SpaceX and Netflix results, due after US trading ends.
Company news:
- 3M (MMM.US) is up 1.4 percent after beating Wall Street profit estimates and raising its full-year outlook for the second quarter in a row.
- Alvotech (ALVO.US): Shares are up 7 percent after the US FDA approved a new manufacturing process for the drug Simlandi.
- General Motors (GM.US): The company is down about 7 percent after cutting its full-year profit forecast.
- Halliburton (HAL.US): Shares are up about 3 percent after the oilfield services company reported third-quarter earnings per share that beat the average analyst estimate. The company also forecasts revenue growth of a mid-single-digit percentage through 2027.
- Hertz (HTZ.US): Oro Mobility, backed by the car rental firm, secured a strategic equity investment of 80 million dollars. Shares are up about 3 percent.
- MSCI Inc. (MSCI.US): The index provider reported adjusted third-quarter earnings per share that significantly exceeded the average analyst estimate (EPS: 5.11 dollars vs 5.02 dollars). Shares are up about 6 percent.
- NuScale Power (SMR.US): Barclays published a negative report on the company, citing risks tied to a lack of contracts. Shares are down more than 3 percent.
Technical analysis US100 (D1)
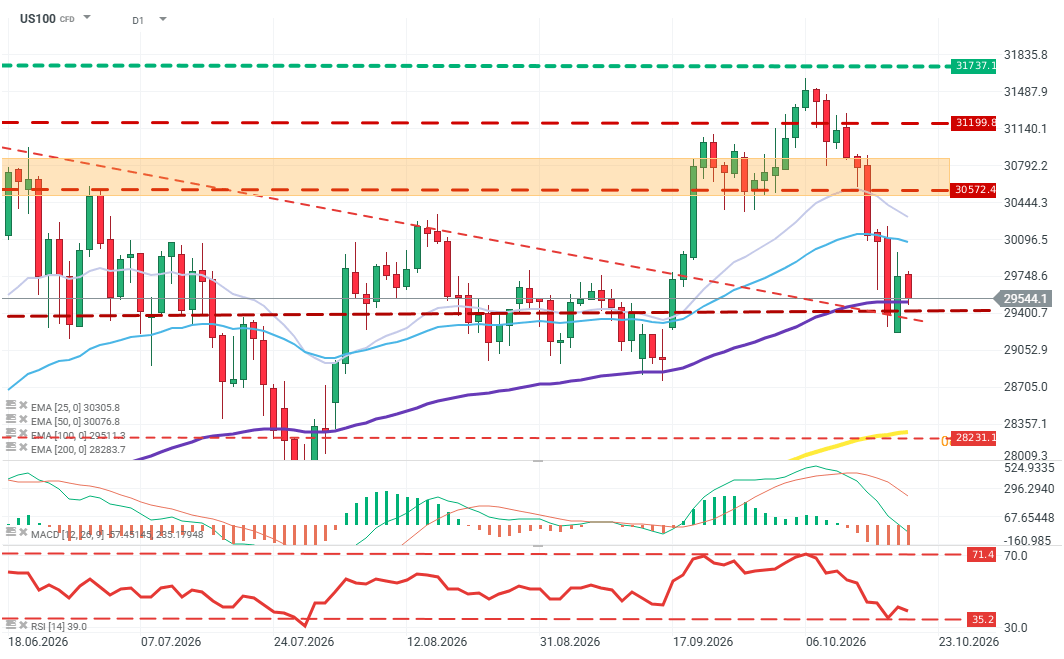
Price action shows sellers in control after a sharp drop from around 31,500. It is currently below EMA25 and EMA50, and the MACD signals downside pressure. RSI at 39.5 confirms buyer weakness, though it is approaching oversold territory in a way that could become risky for sellers. The key support for now is 29,400. A break could open the way toward around 29,000. Holding support and a move back above around 29,750 could initiate a larger rebound toward around 30,500. Source: xStation5
Macroeconomic data:
- UK average earnings rose 3.7 percent. The average three-month change in employment rose from 67 thousand to 102 thousand (about 20 thousand expected).
- Germany’s ZEW index rose to minus 35.9 versus expectations of 45.0.
- US building permits came in at 1.4 billion in September (1.39 billion expected).
- US housing starts fell more than 5 percent month over month to 1.22 billion, disappointing versus expectations of about a 1.9 percent increase.

US Natural gas extends declines 🔥📉

SpaceX must show that Starlink can fund the Group’s growing ambitions

Netflix Preview. It needs to prove it can still surprise


Chart of the Day: US100 (Nasdaq 100). Rebound in AI trade vs. weakening technical picture
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.