


Friday’s opening on Wall Street brings moderate relief after two days of selling. Indices begin the session slightly above the opening print, helping to limit losses heading into the end of the week. In the first hours of trading, the Dow Jones stands out positively, with futures up about 0.2%.
The key catalyst for improved sentiment was a statement from President Donald Trump, who said the US would take no military action against Tehran ahead of the upcoming election following “productive talks.” Lower geopolitical tension supports markets and may reduce inflation expectations, although the oil market remains skeptical about the durability of the de-escalation. Brent remains above roughly $103, which is reflected in valuations of, among others, airlines.
The technology sector is reacting optimistically to OpenAI-related news. According to a Bloomberg report, OpenAI’s annual revenue as of the end of September was about $50 billion, and further development is expected to lift that figure to $70 billion by the end of December. Risk appetite in tech and AI is additionally fueled by Lumentum, which says demand significantly exceeds the company’s capacity.
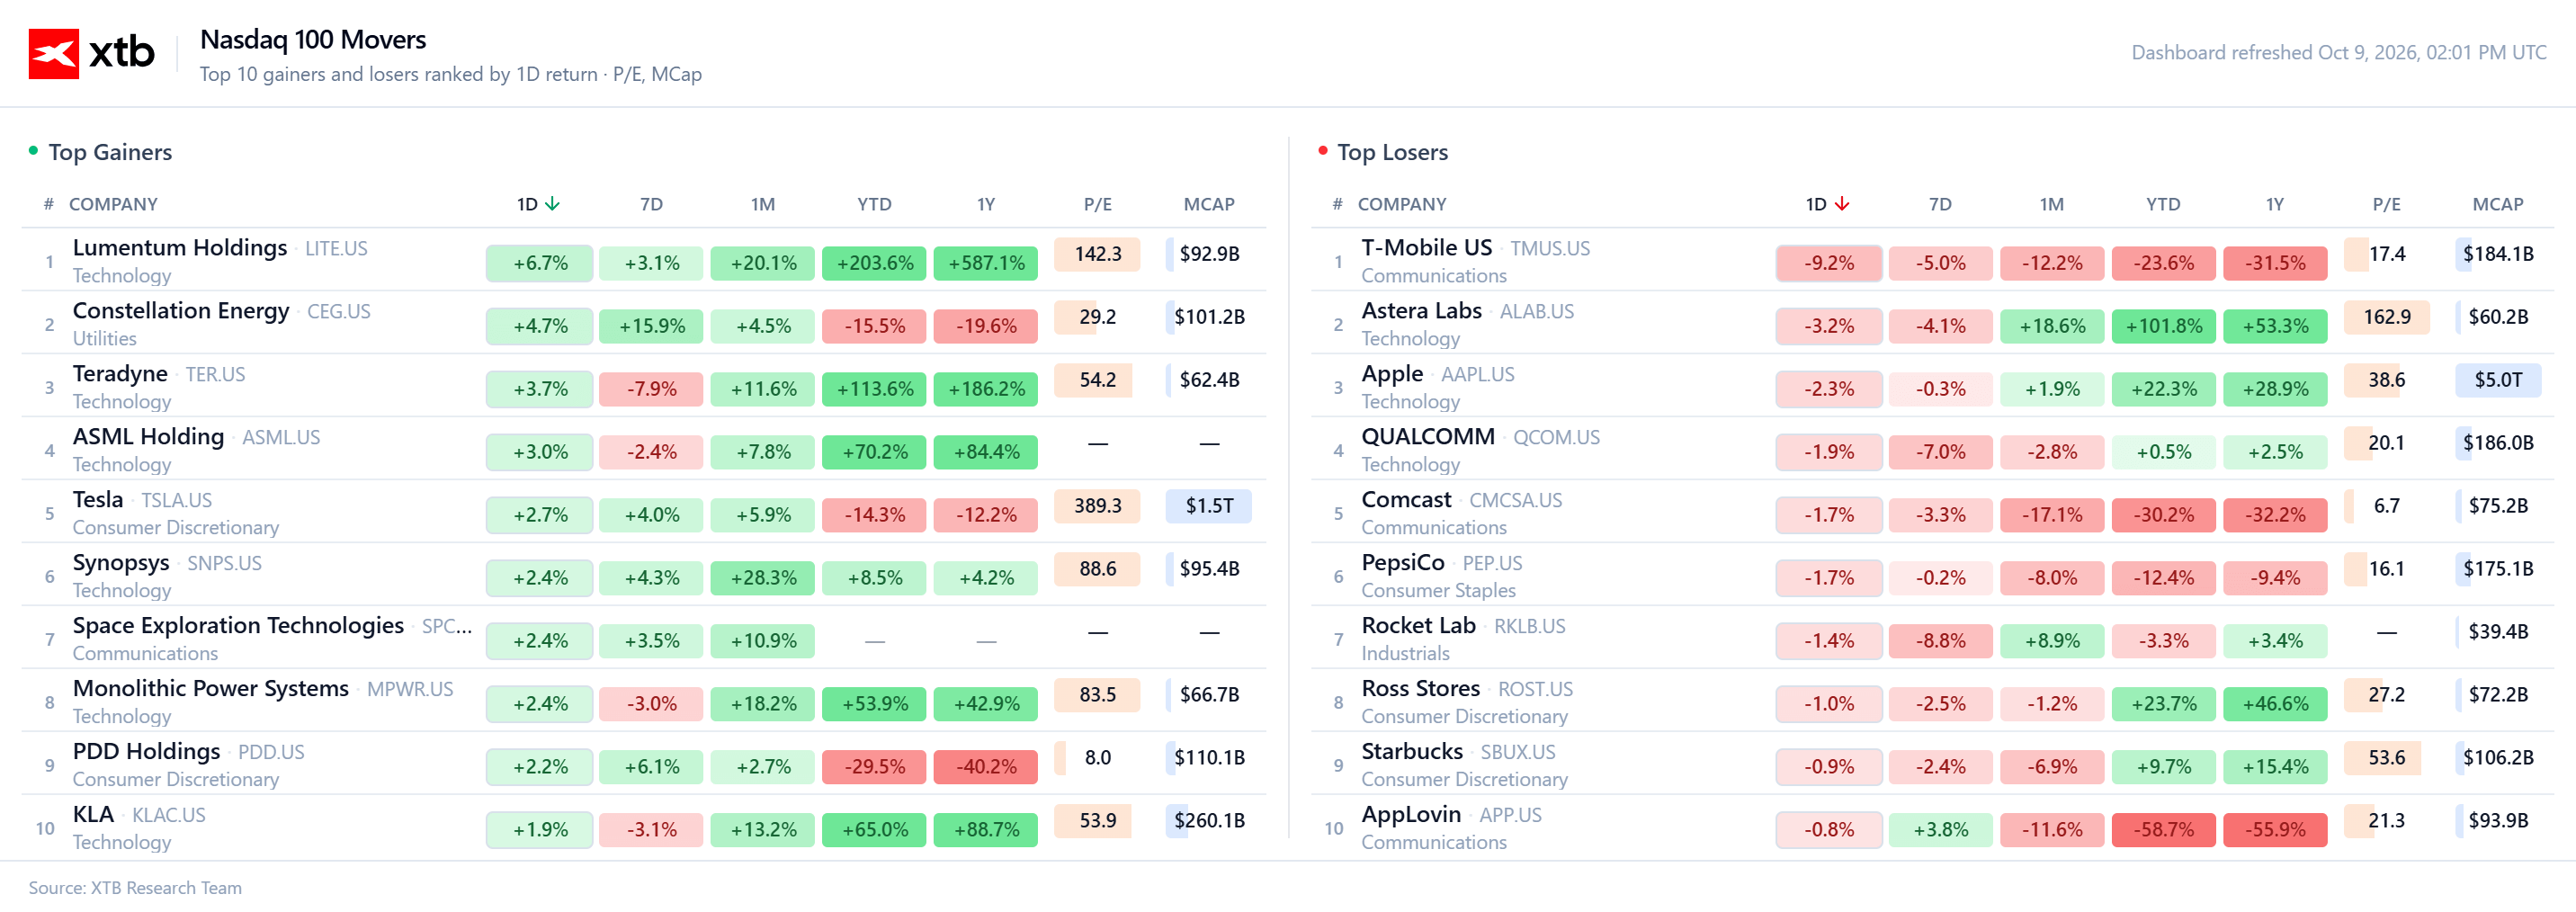
- Capital is returning to beaten-down technology names and selected parts of industry, though the flow is not even or symmetrical. Telecommunications companies and airlines are under pressure.
- The yield on the US 10-year Treasury stabilizes around 5.254%, while on the short end of the curve the 2-year Treasury yield hovers near 4.78%.
- The US dollar index remains relatively stable, although on a weekly basis it is heading toward a fourth consecutive week of gains.
Technical analysis US100 (D1)
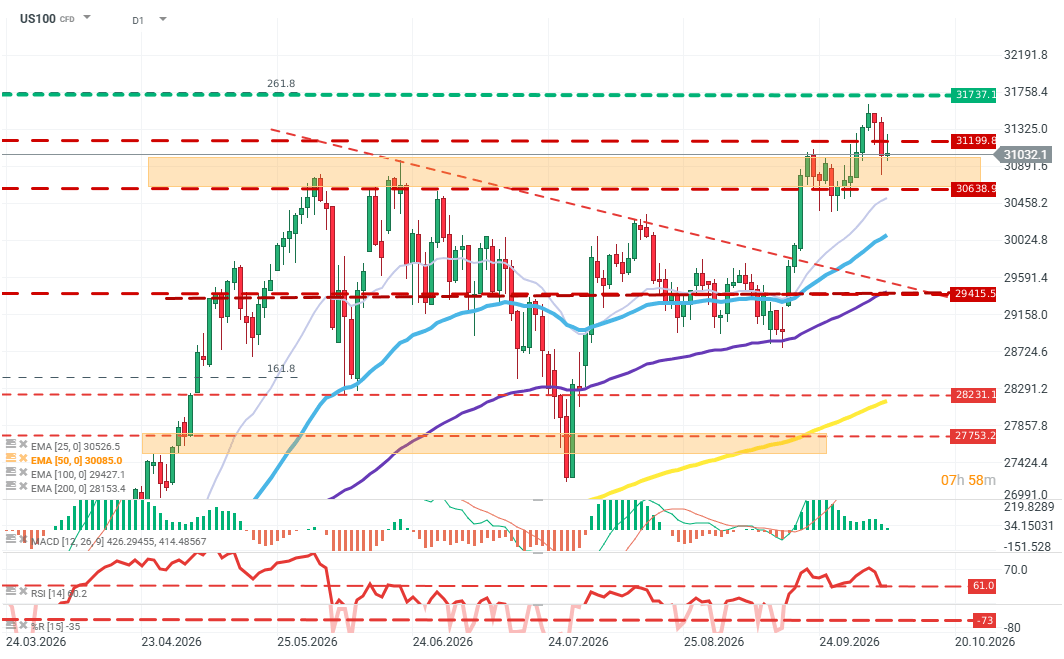
Prices are pulling back from the latest peak, stalling in a broad resistance zone marked by prior highs between roughly 31,000 and 30,600. The initiative remains with buyers, as indicated by the momentum of the EMA averages and RSI (14) at 60 points. The key level for bulls to defend is around 30,600, additionally supported by the 25-day EMA. If the consolidation breaks to the downside, the sellers’ target could be to push the price close to the downtrend line from the June to September period. Source: xStation5
Company news
- Humana (HUM.US): Shares jumped about 13% after the insurer significantly improved its ratings in the key Medicare Advantage quality program, which will directly translate into higher premiums and future revenue. The company confirmed adjusted EPS above $9.00 for 2026.
- Telecommunications: Shares of AT&T (T.US), T-Mobile (TMUS.US), and Verizon (VZ.US) are down about 7.0%. The sell-off in traditional telecoms is a direct reaction to Elon Musk’s SpaceX announcing the purchase of low-frequency spectrum. This move enables the use of the Starlink satellite constellation to enter the role of a direct nationwide mobile operator in the US.
- Lumentum Holdings (LITE.US): Shares of the photonics company are up about 6% after it said optical components for AI data centers are completely sold out through early 2029 due to massive demand from technology giants.
- Apple (AAPL.US): The tech giant’s shares are down about 2%. Selling pressure was triggered by industry reports about reduced orders for components for iPhone 18 Pro and Pro Max models due to weaker-than-expected consumer demand.
- American Express (AXP.US): Shares are down about 2% after US regulators imposed a $350 million fine for shortcomings in anti-money-laundering (AML) procedures and failure to report suspicious transactions.
- Delta Air Lines (DAL.US): The carrier’s shares fall 2% after it lowered full-year guidance for adjusted earnings per share. The revision is driven by persistently high jet fuel prices.
Macroeconomic data:
- The University of Michigan published its consumer sentiment and inflation expectations data.
- Sentiment in August came in at 46.3 versus 47.7 expected (previously 48.1).
- One-year inflation expectations rose to 4.7, while long-term (5-year) expectations increased to 3.5.

🔼 Gold gains 1.2%

Nasdaq tries to recover losses 📈 Was the OpenAI revenue scare overdone?

Chart of the Day: EURUSD Stages a Rebound, but France and the Fed Could Cap the Upside


Economic Calendar: Canada’s Jobs Report in Focus
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.