

- US equity indices decline as rising oil prices intensify inflation concerns.
- The 10-year Treasury yield reaches 5.28 percent, hitting its highest level since 2007.
- Gold and silver drop sharply as rising real yields and a stronger US dollar weigh on precious metals.
- Nvidia shares rise over 2 percent following a 150 billion USD share buyback announcement.
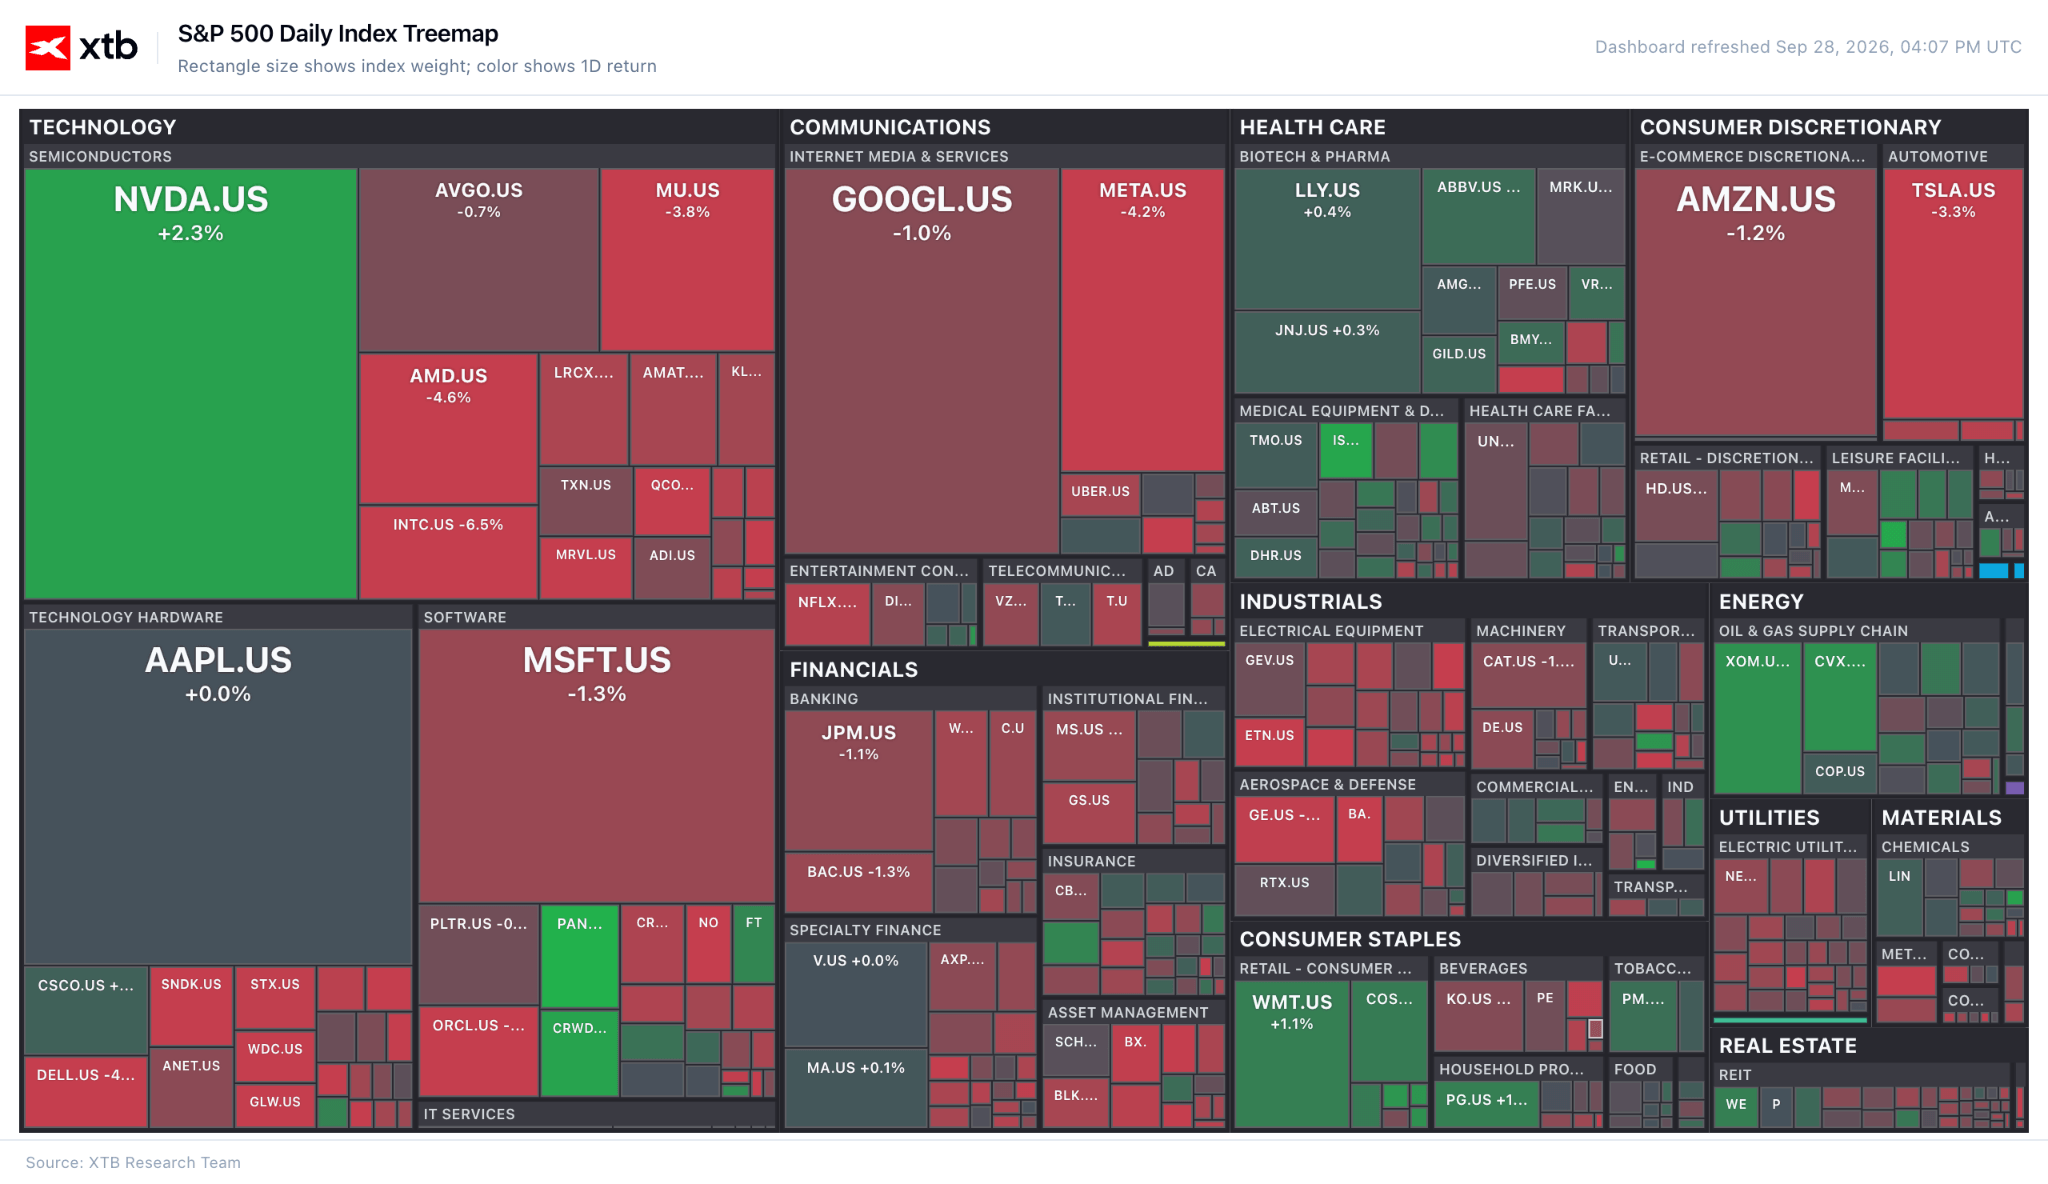
US equity indices are posting declines today. The Nasdaq 100 is down 1.3%, while both the S&P 500 and the Dow Jones are falling by roughly 0.8%. The sell-off is largely driven by a familiar mechanism: a lack of positive developments in US-Iran talks is pushing crude oil prices higher, intensifying inflation concerns, driving up market expectations for Fed rate hikes, and lifting Treasury yields.
Figure 1: Treemap for S&P 500 (28.09.2026)
 Source: XTB Research, 28.09.2026
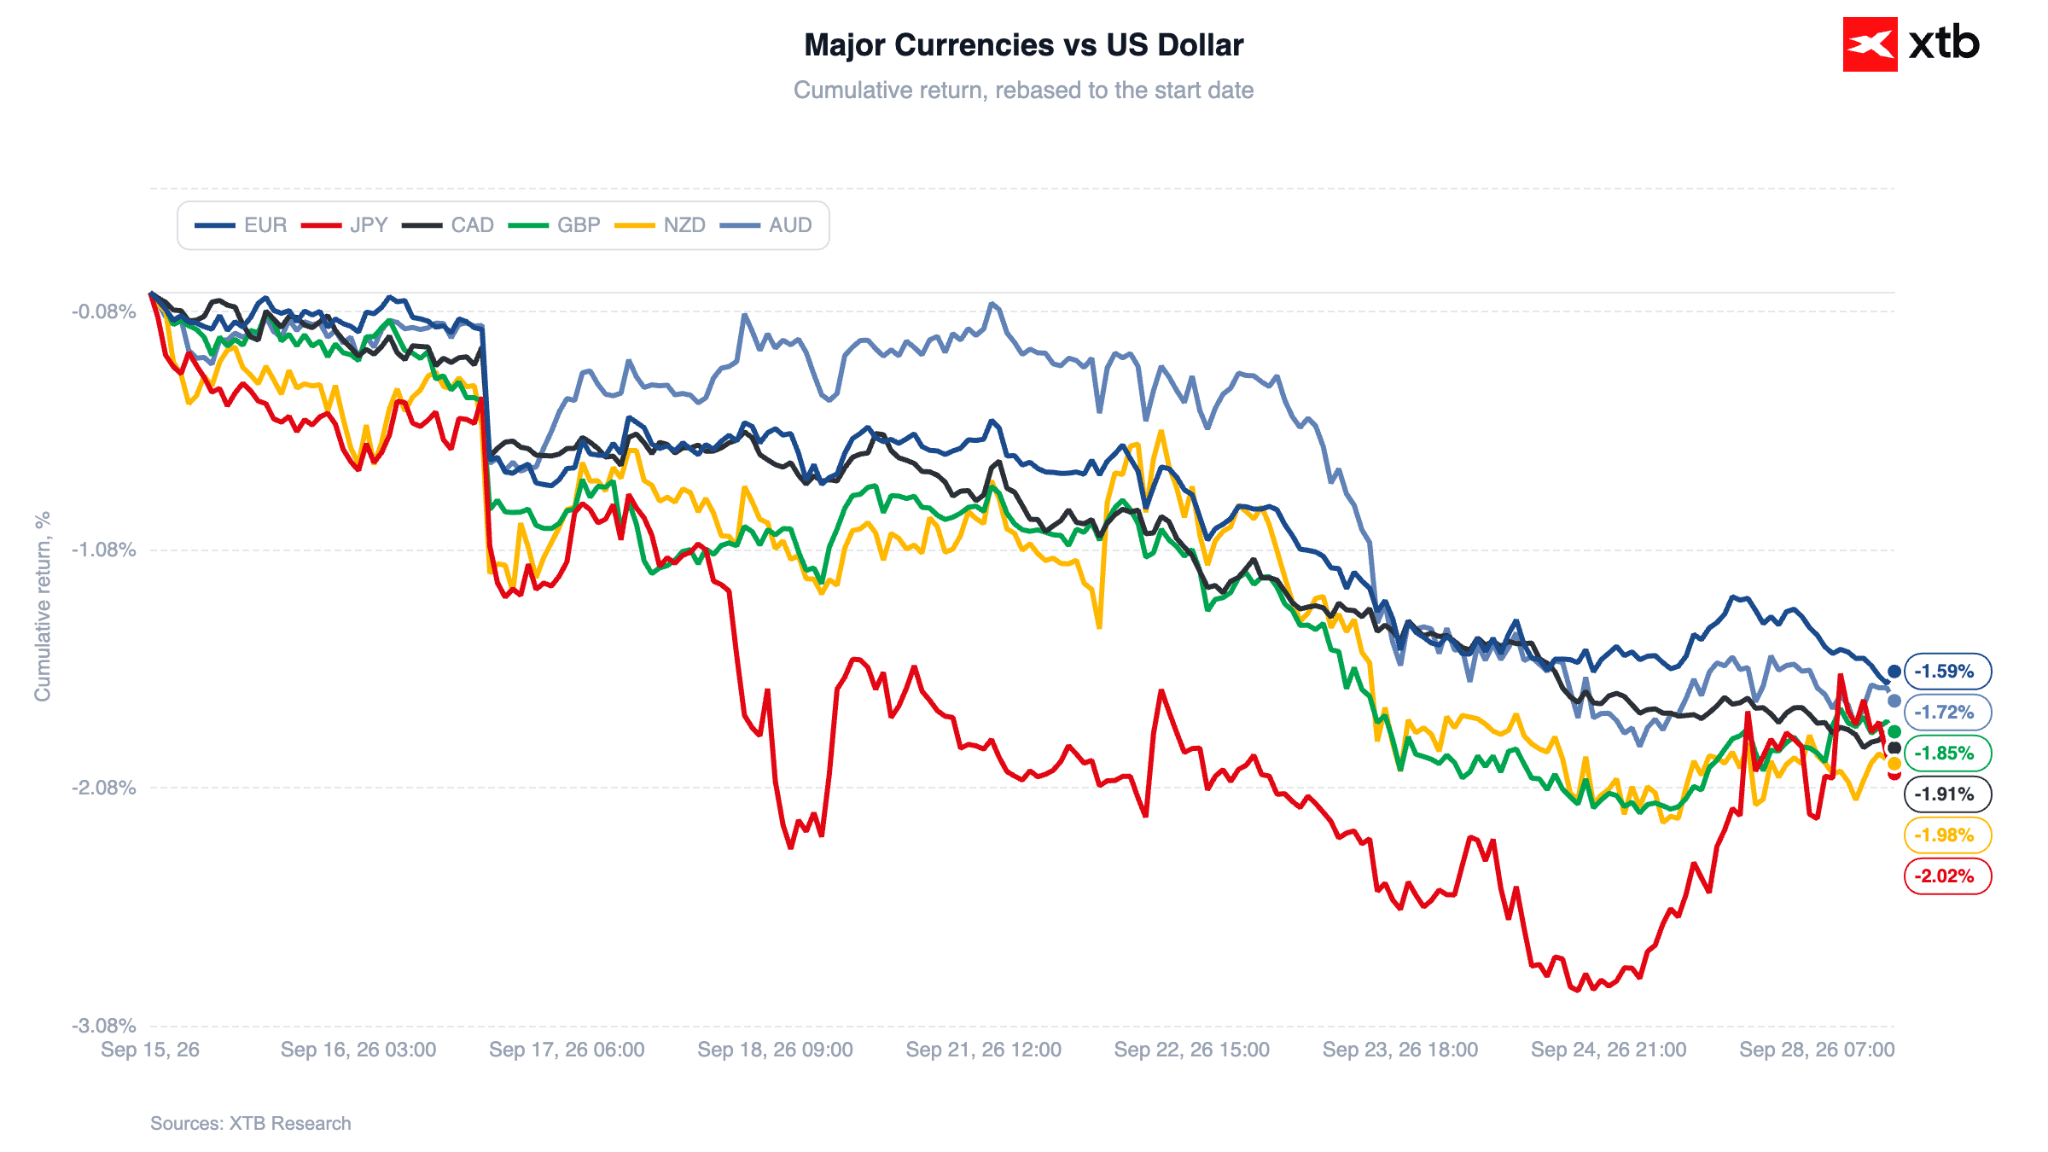
10-year Treasury yields reached a new 19-year peak today (5.28%), underpinning the US dollar, which fully erased Friday's losses. The EURUSD pair is currently hovering around 1.137. The greenback is strengthening against nearly all G10 peers.
Figure 2: Performance of Major Currencies Against the US Dollar (15.09.2026 - 28.09.2026)
 Source: XTB Research, 28.09.2026
Impasse Continues
Hopes for a swift agreement, which boosted markets last week, have faded noticeably today. Tehran maintains that its proposal regarding the opening of the Strait of Hormuz, rejected last week by Donald Trump, remains on the table. Both sides appear far from a compromise on either a ceasefire or the reopening of the shipping lane. Iranian Foreign Minister Abbas Araghchi is scheduled to meet mediators in New York today (without US participation).
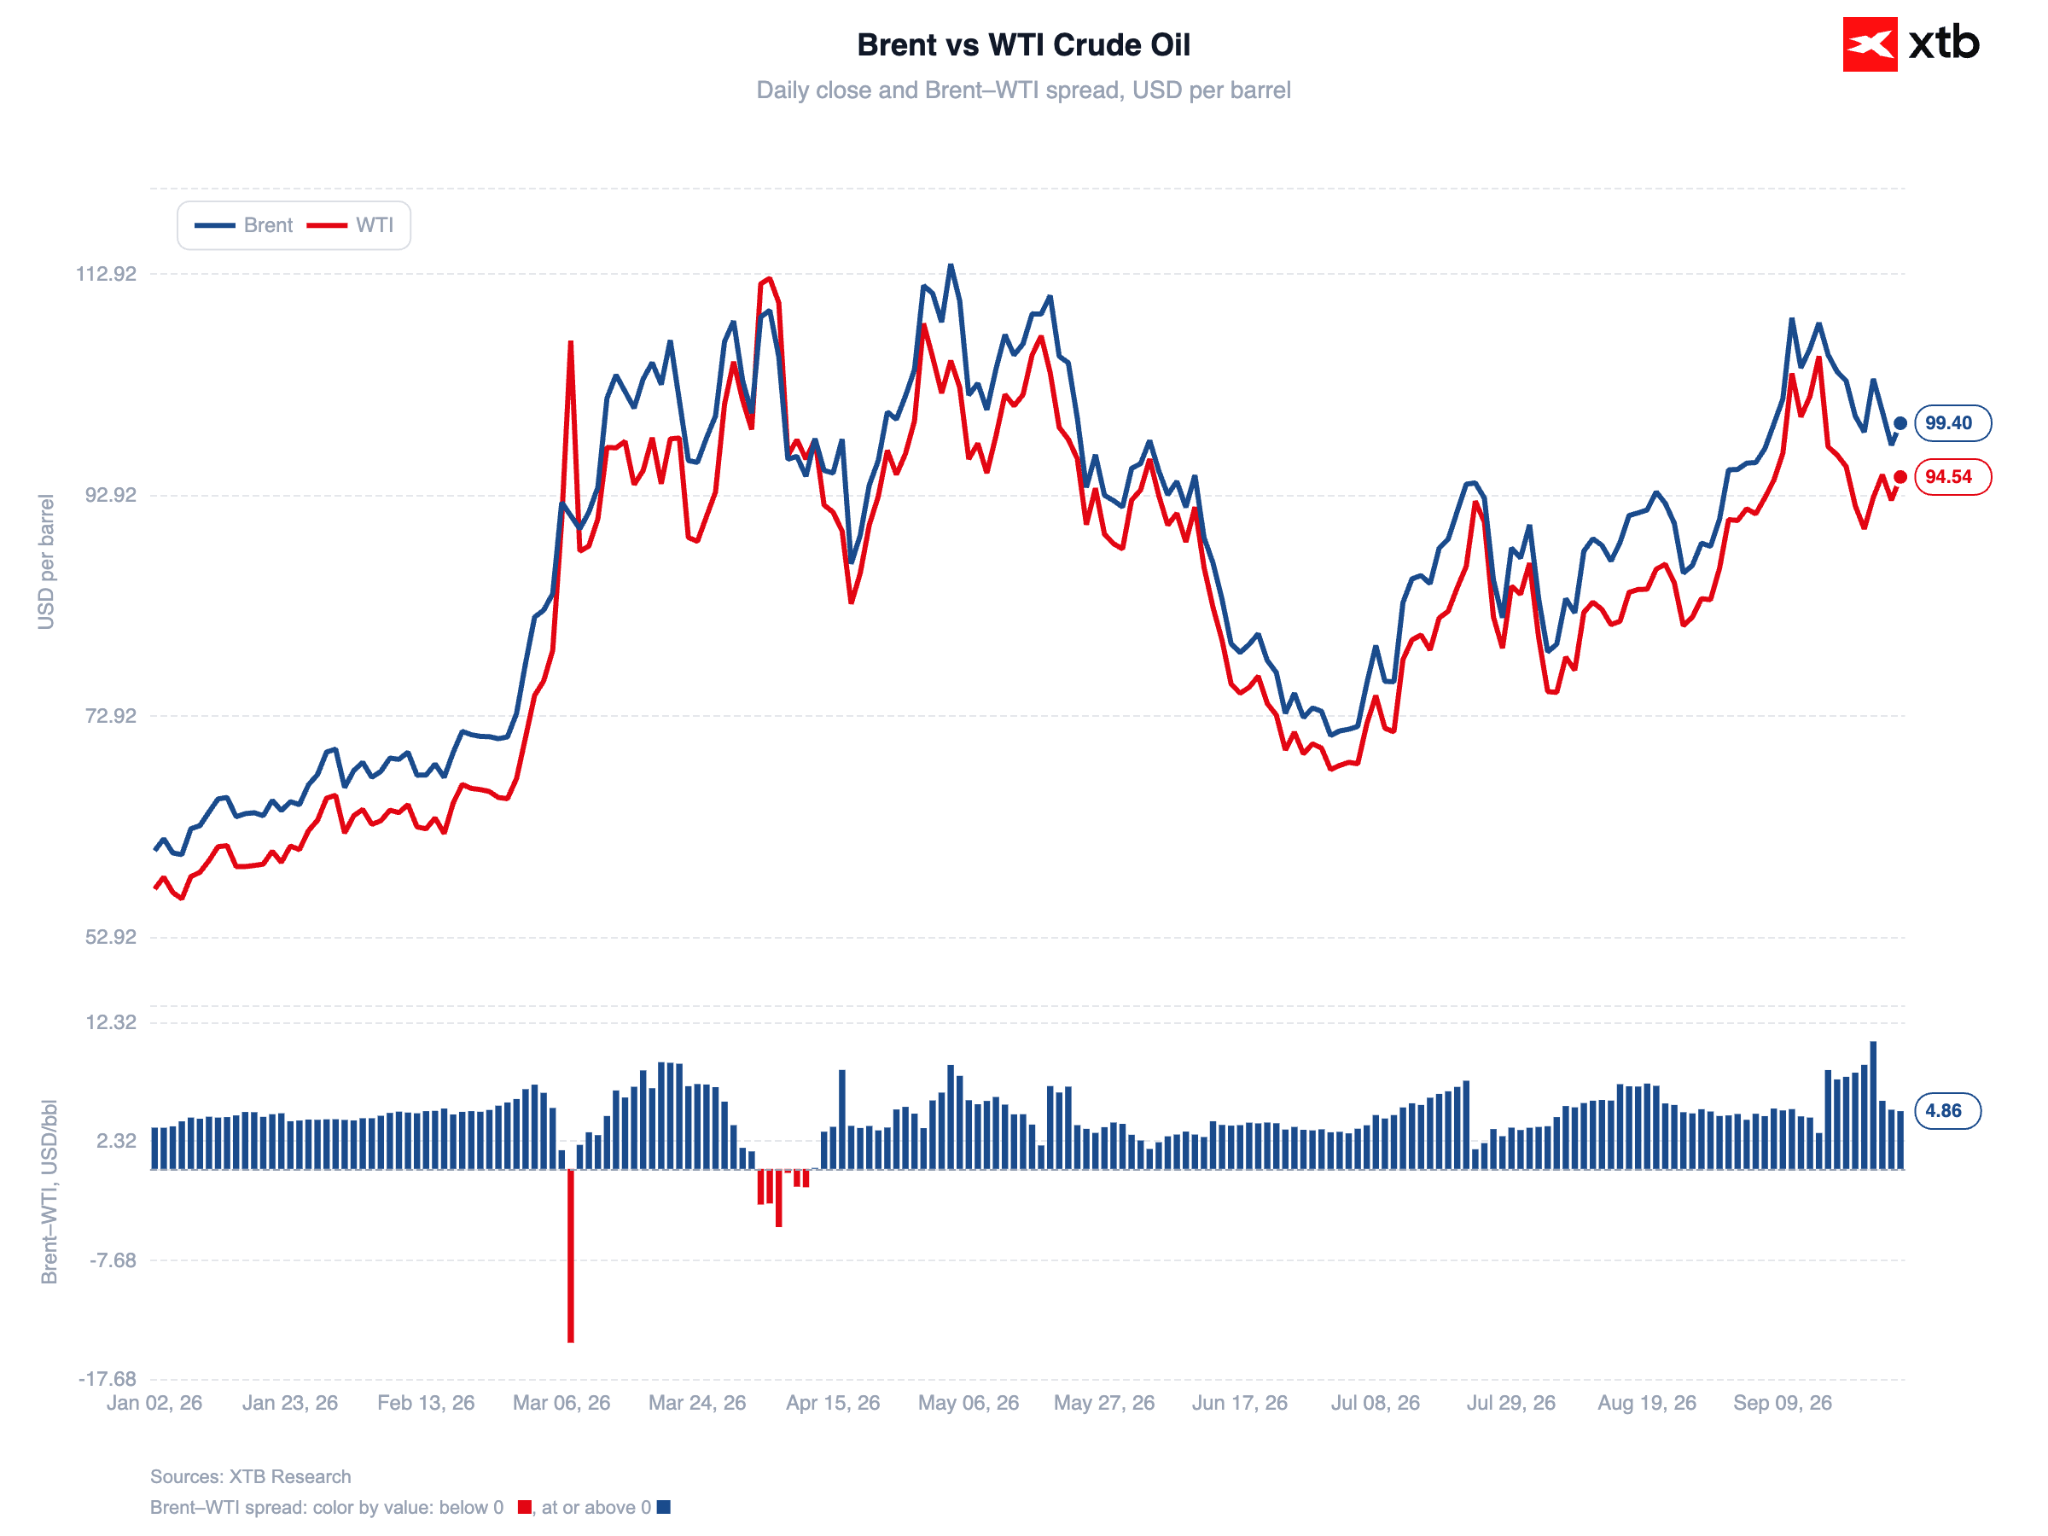
Brent crude is up nearly 3% today, trading near $100 per barrel, matched by WTI, which is hovering around $95.5. European TTF natural gas prices are rising by 4.5%, reaching just over €73 per MWh.
Figure 3: Brent and WTI Crude Oil (2026)
 Source: XTB Research, 28.09.2026
It is worth noting that markets are largely overlooking positive supply developments. Saudi Arabia resumed crude exports via the East-West pipeline following repairs to damage sustained during drone attacks on 10 September. Current flows stand at approximately 3.5 million barrels per day against a total throughput capacity of around 7 million bpd (with roughly 5 million bpd typically designated for export). Full capacity restoration is expected to take another six weeks.
However, Saudi Arabia's western coast remains vulnerable to attacks by Houthi forces, who have intensified strikes on energy infrastructure this month, including targeting the port of Yanbu, where the pipeline terminates.
Yields Reach New Highs
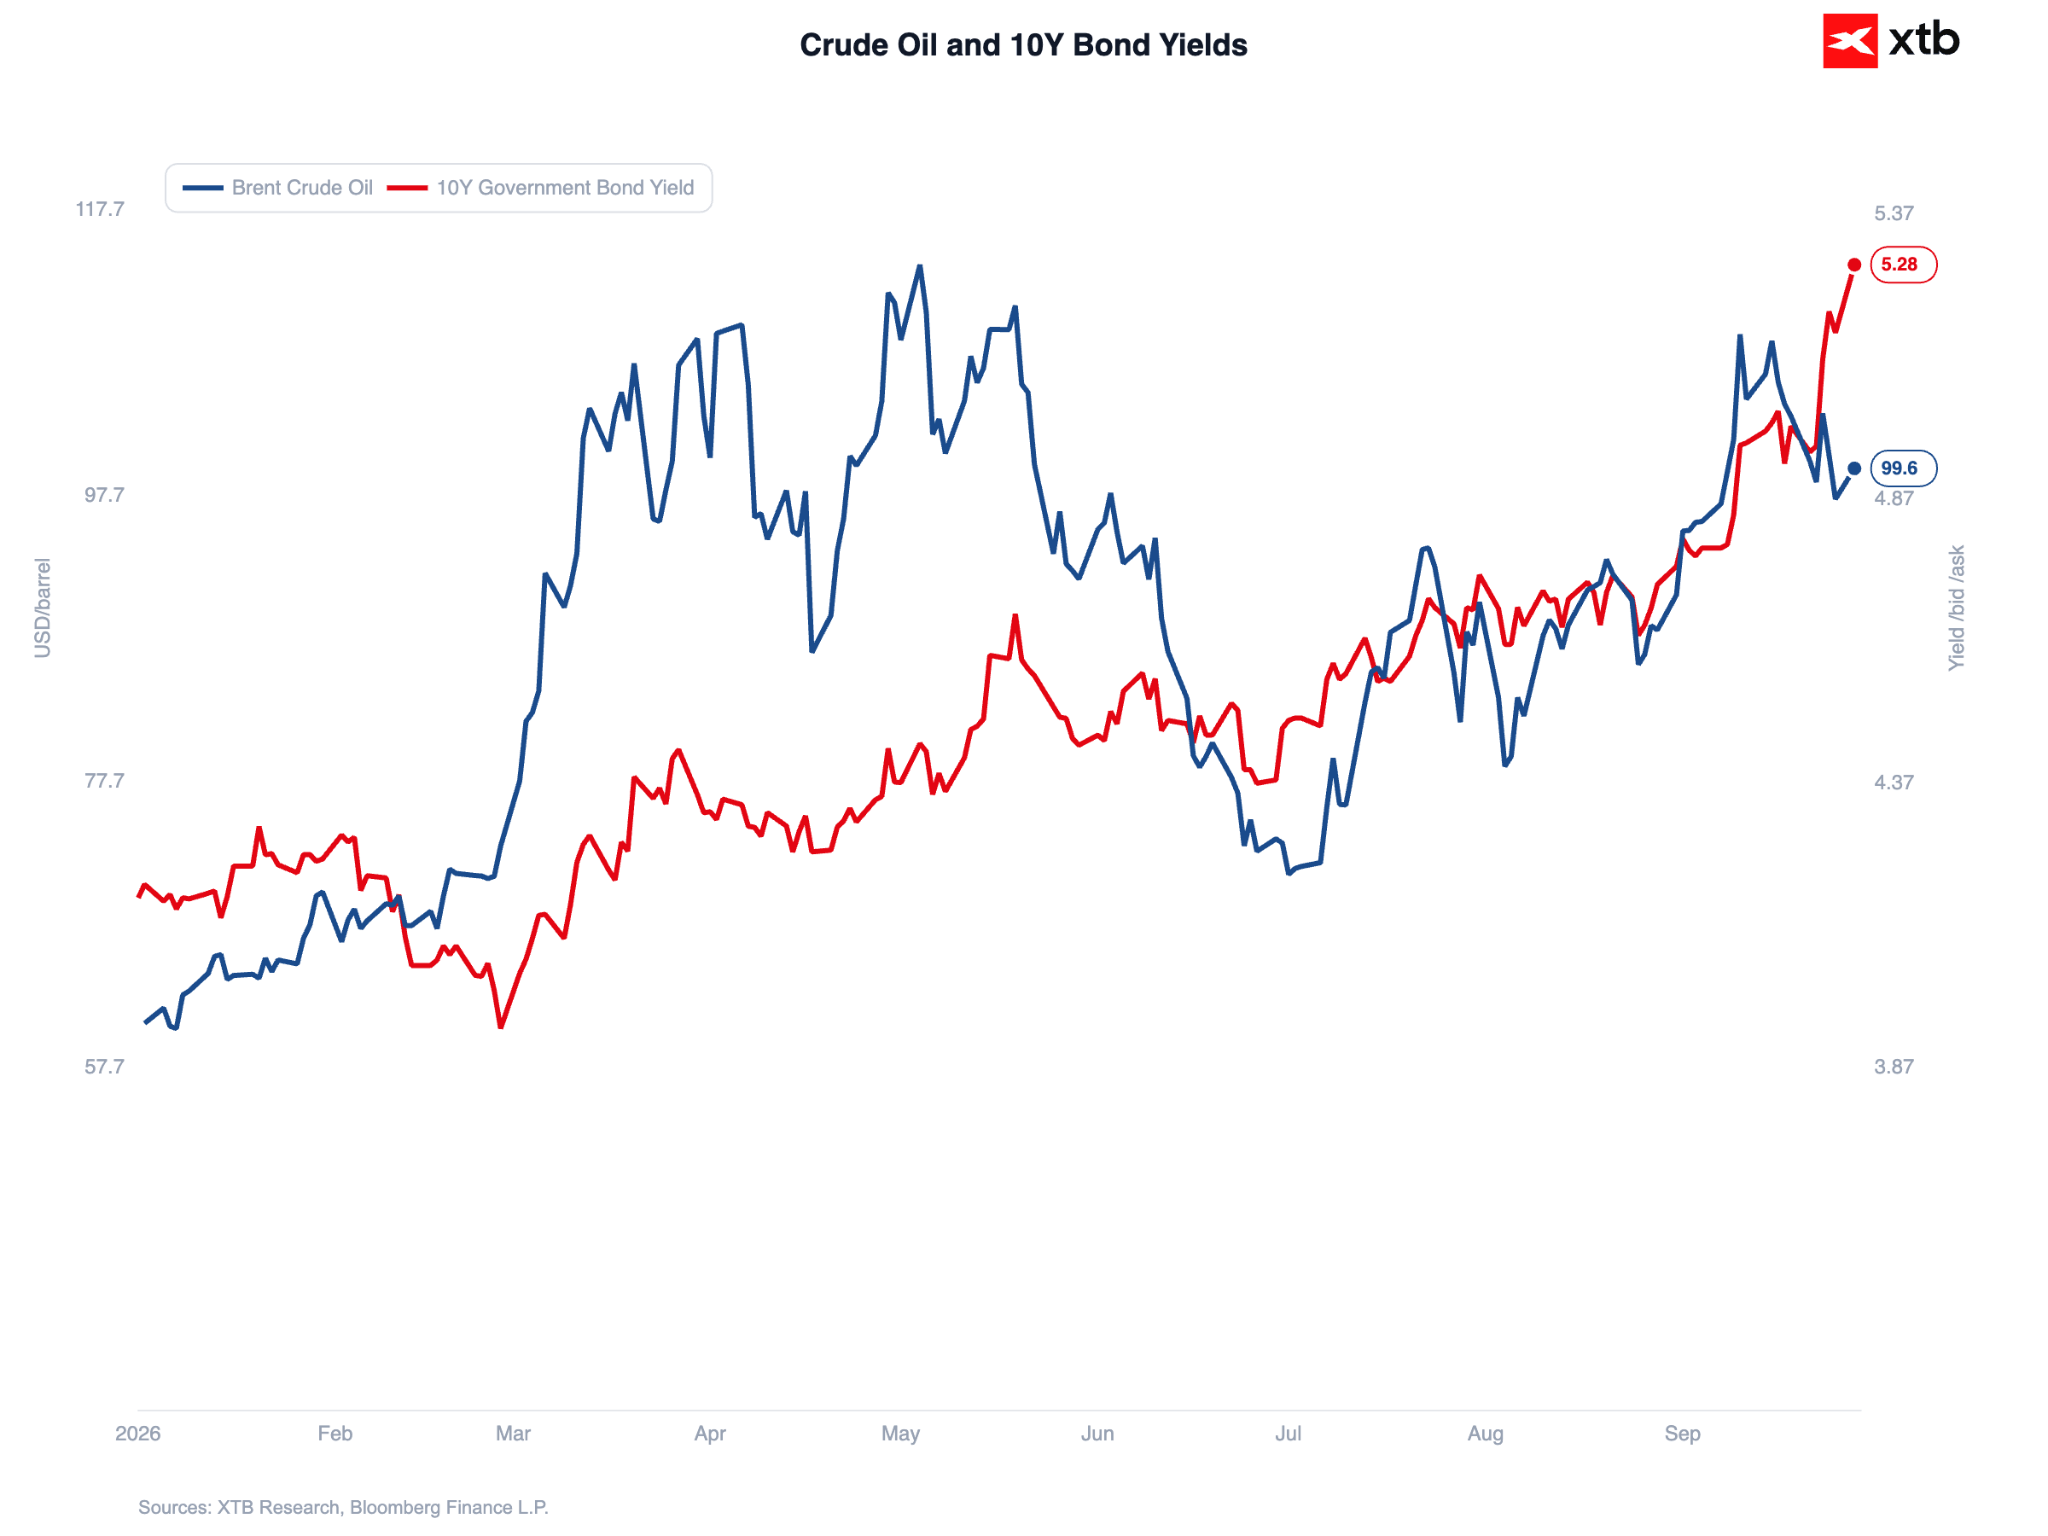
The US 10-year Treasury yield is up by around 7 bps today, reaching 5.28%, its highest level since 2007. In this context, a broader trend in real yields (adjusted for inflation expectations) is noteworthy: 10-year real yields have climbed nearly 100 bps since the start of the year, with half of that movement occurring in September alone.
Figure 4: Brent Crude Oil and US 10-Year Government Bond Yields (2026)
 Source: XTB Research, 28.09.2026
Expectations for FOMC interest rate hikes have risen sharply recently, driven both by hawkish official commentary and macroeconomic data pointing to robust economic growth, a resilient labour market, and inflation gradually spreading across broader sectors. Key macroeconomic releases lie ahead this week, ranging from PCE inflation data on Wednesday to the NFP report on Friday.
Gold and Silver Decline Despite Conflict
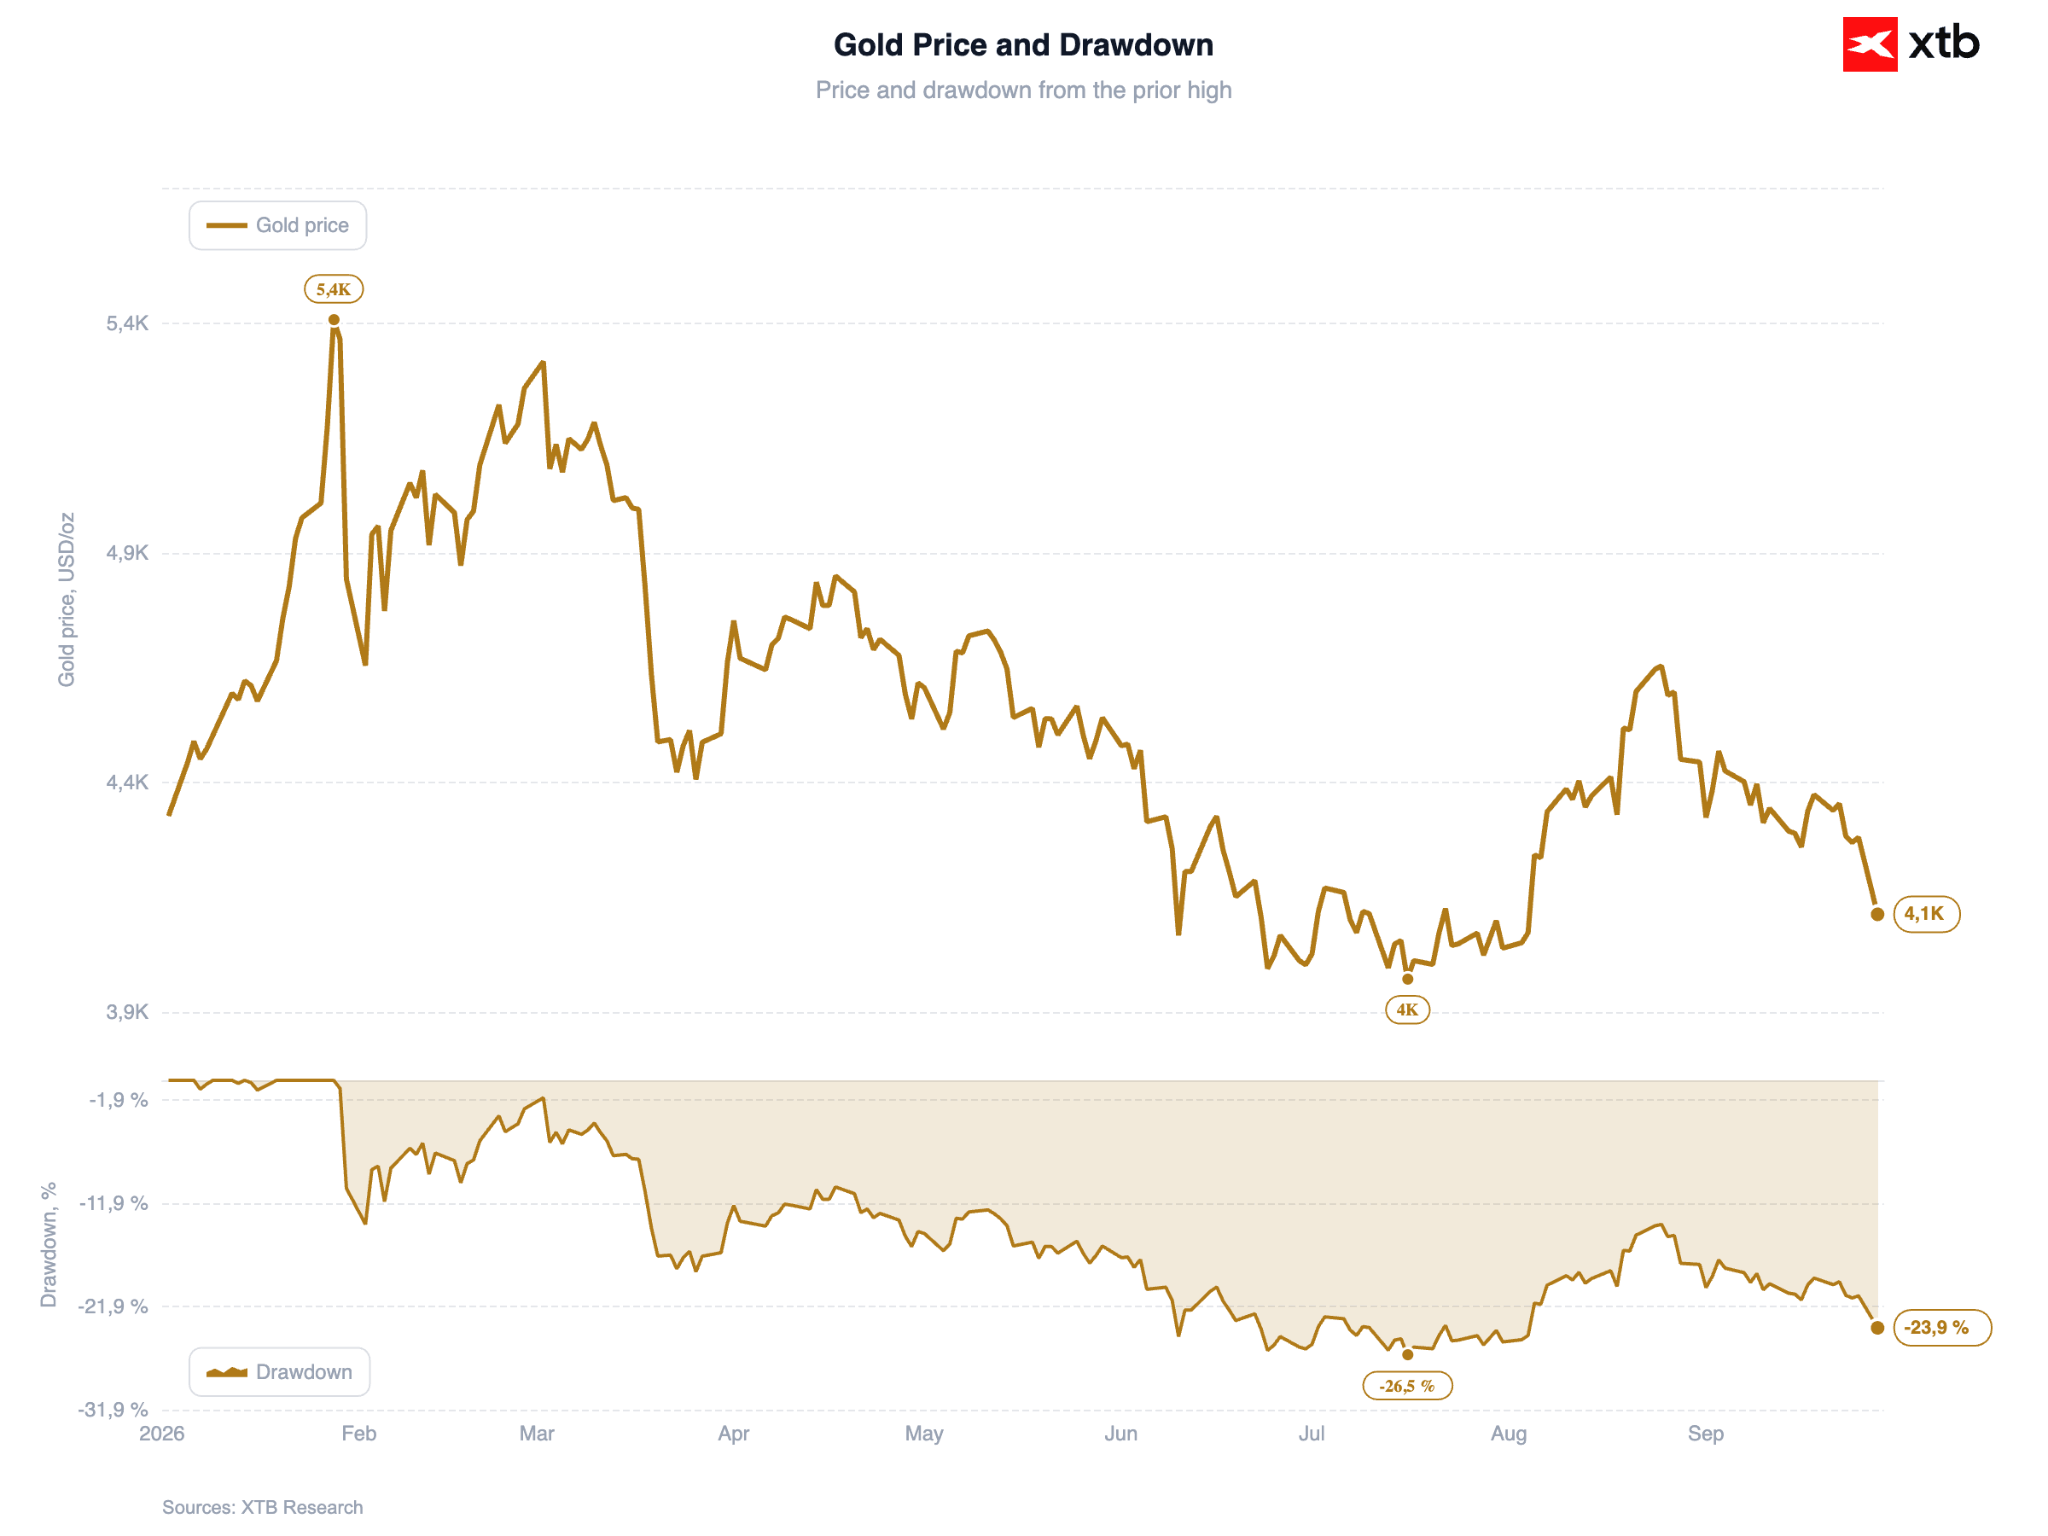
Rising real yields increase the opportunity cost of holding non-yielding assets, while USD appreciation presents an additional headwind. Gold is trading down approximately 4% today, falling to $4,120 per troy ounce. Silver is suffering an even steeper decline of 5%, currently trading around $61 per ounce. The sell-off is weighing heavily on mining equities. Cryptocurrencies are also under pressure, with Bitcoin weakening by nearly 2% to around $83,000.
Figure 5: Gold (2026)
 Source: XTB Research, 28.09.2026
Corporate News
Nvidia ($NVDA.US)
Shares are up over 2% to around $230 following the announcement of a record $150 billion increase to its share buyback programme. The company also introduced an open-source security system designed to monitor AI agent access in real time, aiming to prevent security breaches similar to OpenAI's recent incident with Hugging Face.
Snowflake ($SNOW.US)
The company announced a $3.5 billion convertible senior notes offering. Proceeds will be used in part to repurchase a portion of its convertible notes maturing in 2027.
Amprius Technologies ($AMPX.US)
Shares of the battery manufacturer surged around 10% in early trading before returning to Friday's closing level. The company was awarded a $75 million grant from the US Department of War to adapt its domestic production line (currently focused on EV batteries) for unmanned aerial system battery cells.
—
Michal Jozwiak, Financial Markets Analyst at XTB


📊Market Wrap: Oil drives yields higher and gold lower (28.09.2026)

Chart of the Day: Trump’s remarks strengthen the yen (25.09.2026)

Economic Calendar: Trump-Xi summit yields no breakthrough (25.09.2026)


Morning Wrap: Oil pulls back following reports of Washington-Tehran talks (25.09.2026)
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.