


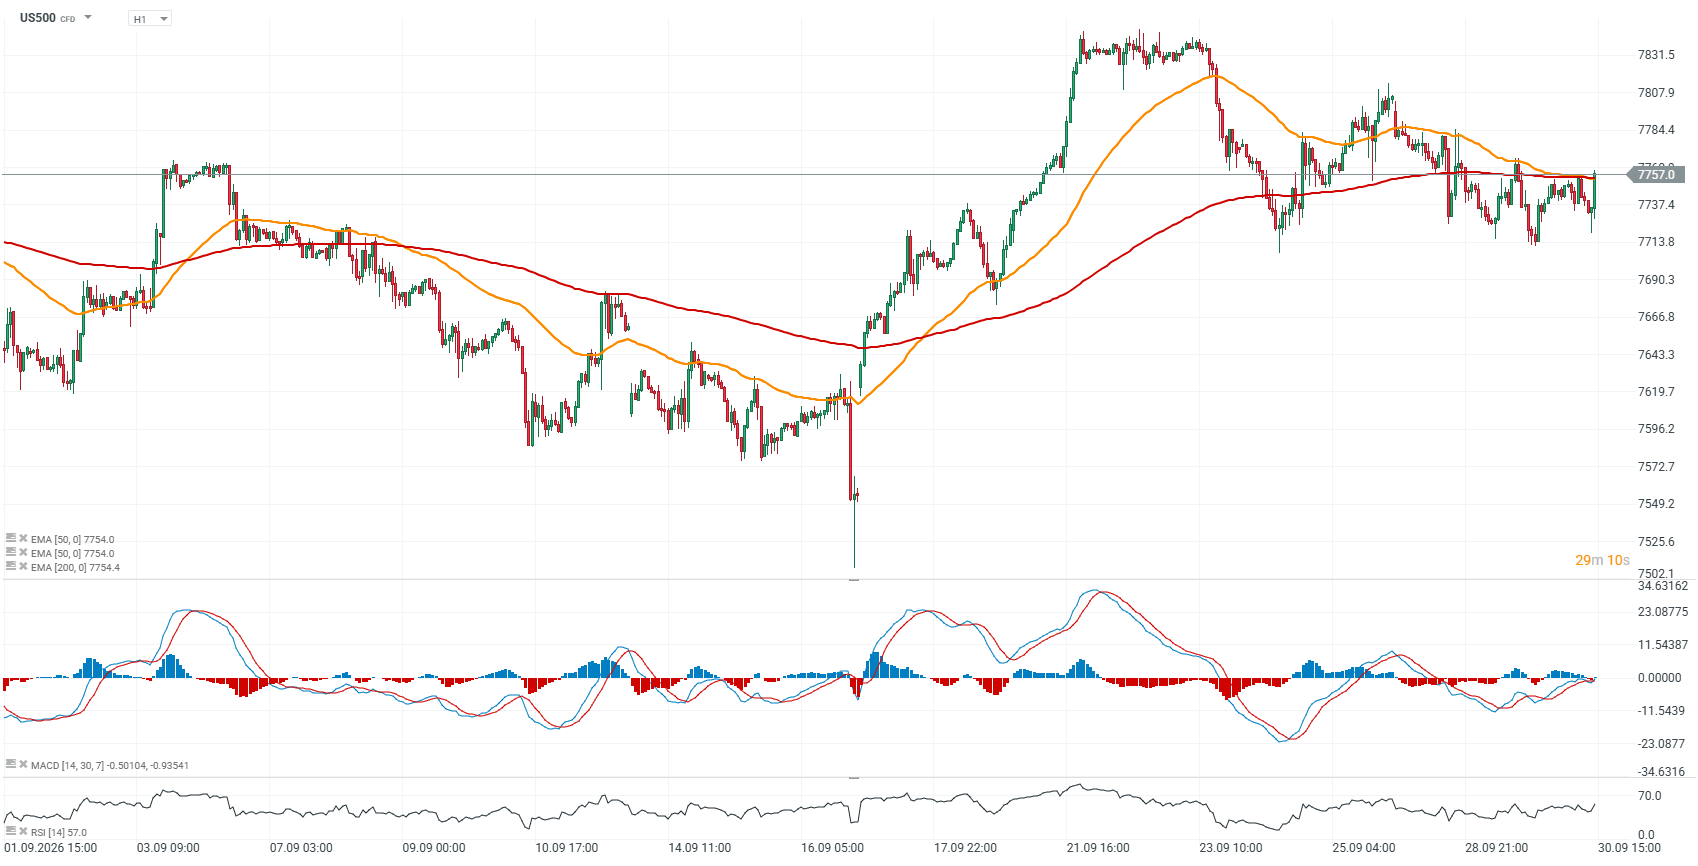
US data showed stronger-than-expected economic growth and consumption, while core PCE inflation came in below forecasts. The US dollar is weakening, while US equity indices are gaining following the release.
PCE inflation and ADP
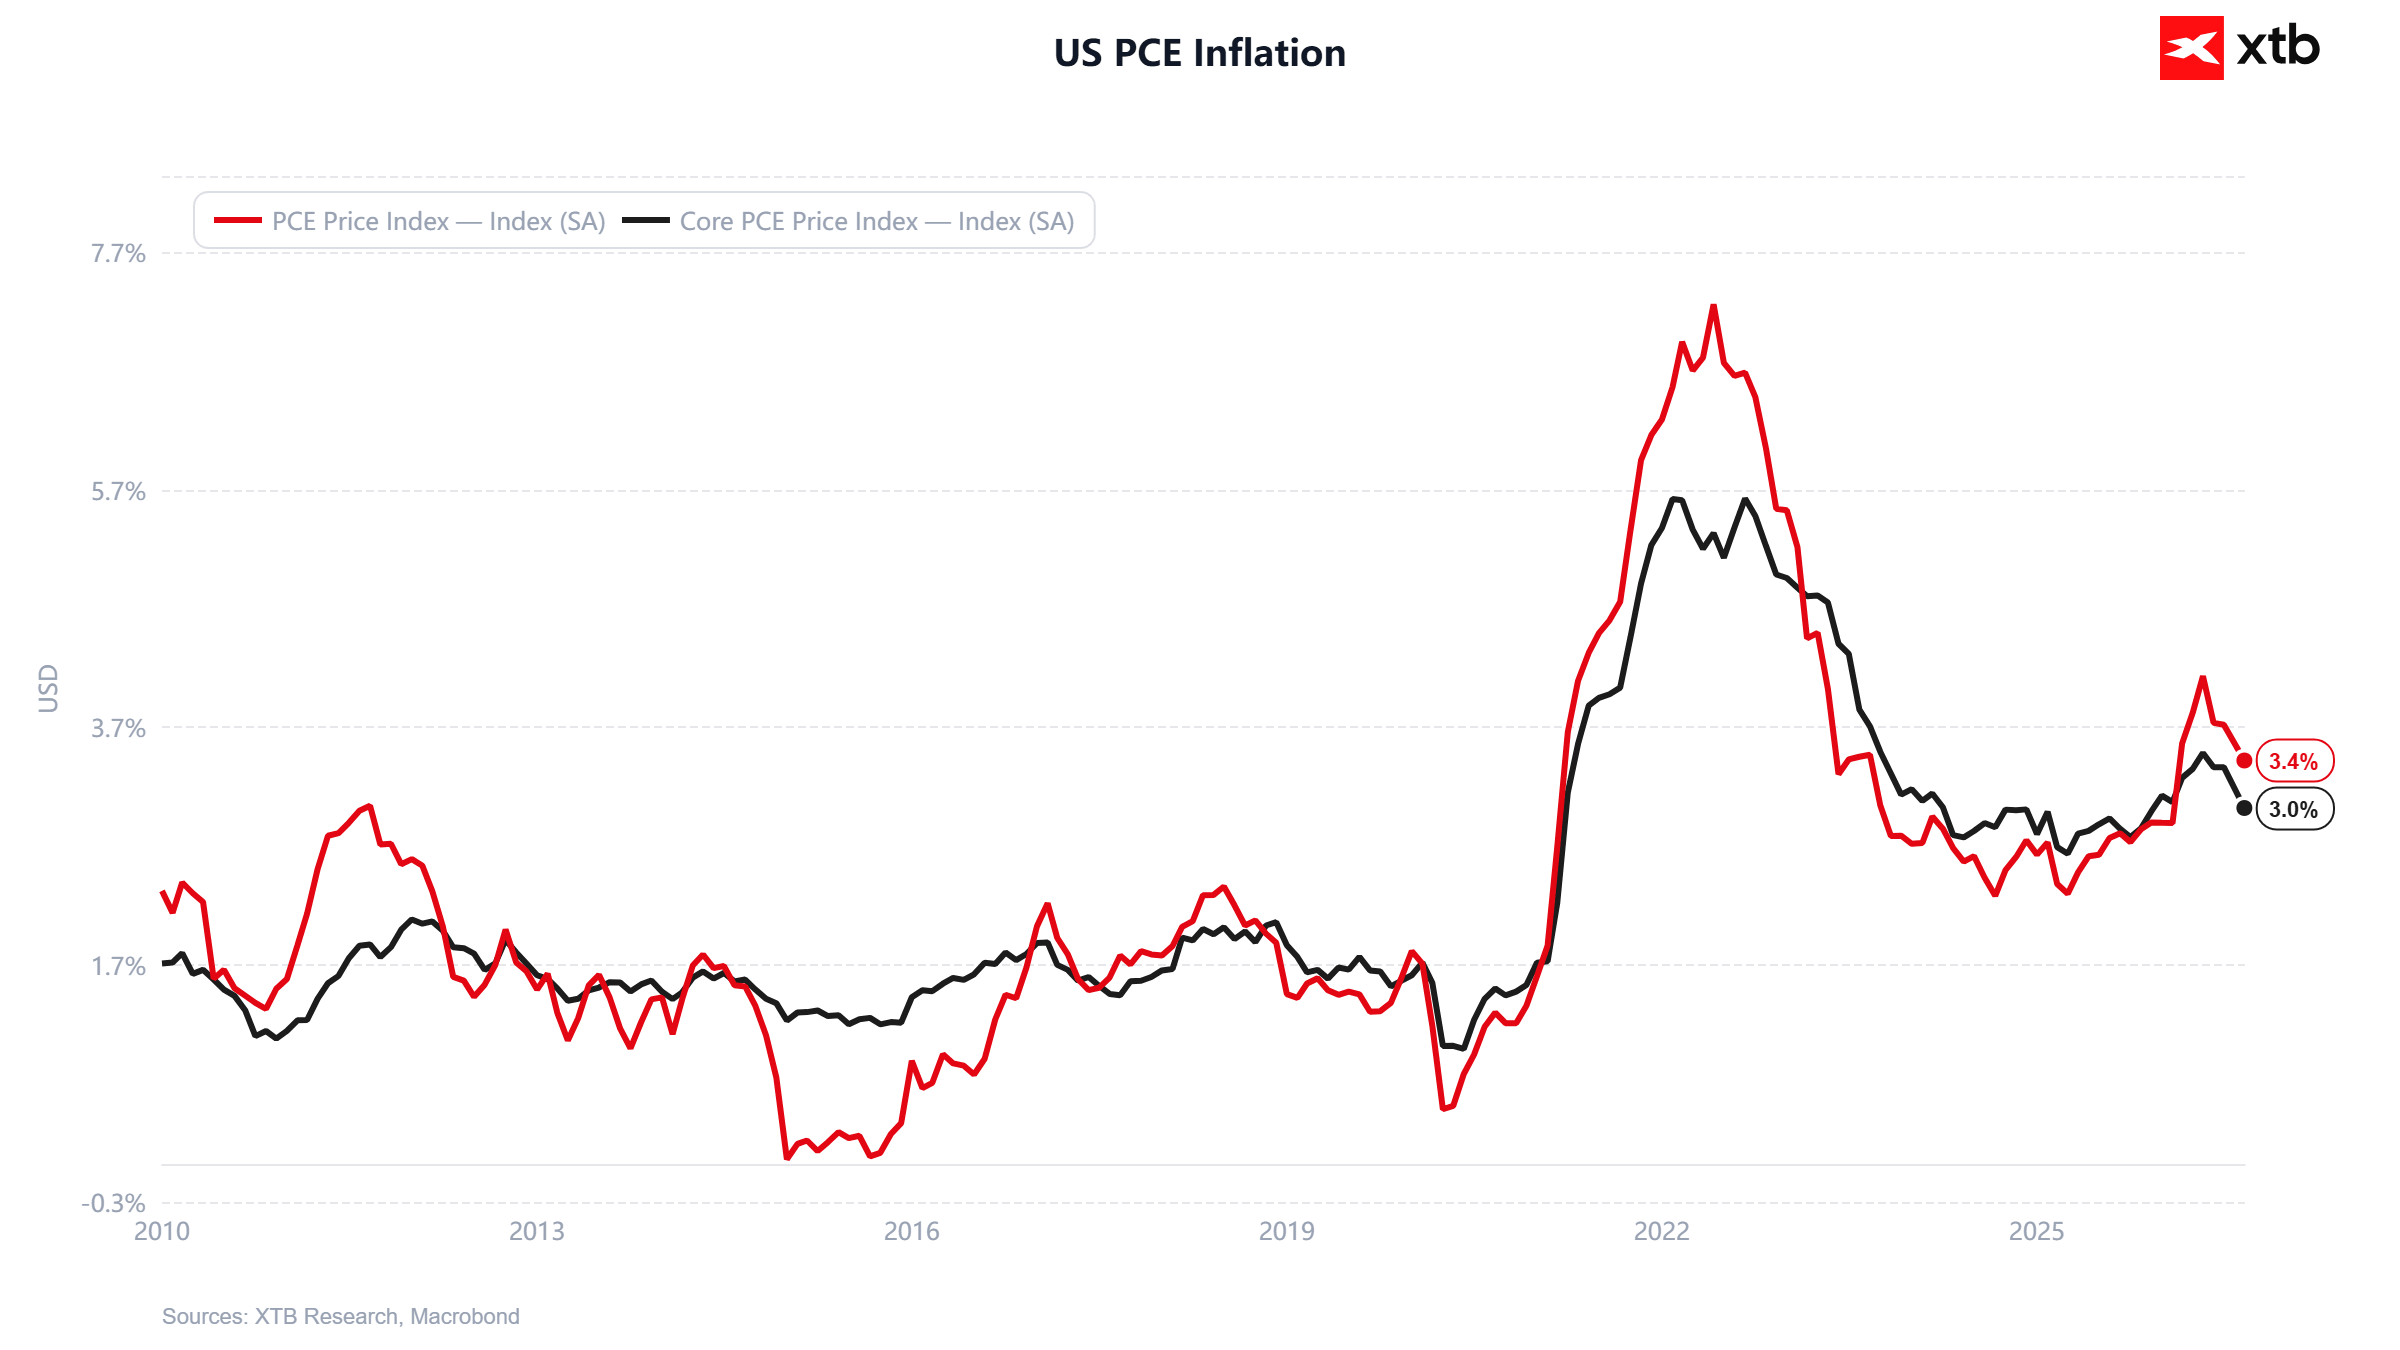
- Headline PCE inflation rose by 3.4% y/y, below the 3.7% forecast and 3.7% previously.
- Headline PCE inflation increased by 0.3% m/m, in line with expectations and up from 0.2% previously.
- Core PCE inflation rose by 3.01% y/y, below the 3.3% forecast and 3.3% previously.
- Core PCE inflation increased by 0.2% m/m, compared with the 0.3% forecast and 0.2% previously.
- The final core PCE price measure came in at 3.3%, below the 3.6% forecast and 3.6% previously.
- The final PCE price measure came in at 5.0%, compared with 5.3% previously.
- US ADP employment increased by 90,000, versus 74,500 expected and 38,000 previously, with the prior reading revised to 36,000.
GDP and deflator
- Final US GDP growth came in at 2.2% q/q, above the 1.5% forecast and the previous estimate of 1.5%.
- The final GDP deflator came in at 6.1%, compared with 6.4% previously.
Income, spending and inventories
- Personal income increased by 0.2% m/m, below the 0.5% forecast and 0.4% previously.
- Consumer spending rose by 0.9% m/m, in line with expectations and up from 0.2% previously.
- Real personal consumption increased by 0.6% m/m, above the 0.5% forecast and following no growth in the previous month.
- Preliminary wholesale inventories rose by 0.7% m/m, compared with 0.5% expected and 1.3% previously.
What did the latest US data show us?
Real consumer spending, adjusted for changes in prices, rose by 0.6% m/m in August, marking the strongest monthly increase since March 2025. Consumers increased spending primarily on goods such as motor vehicles, home furnishings and clothing, despite high gasoline prices and rising costs across large parts of the economy. Demand is also being supported by a relatively stable labour market and rising stock prices, helping households maintain a strong propensity to spend.
At the same time, price pressures remain clearly visible. The Fed’s preferred PCE price index rose by 0.3% m/m, while core PCE, which excludes food and energy, increased by 0.2% m/m. This means the economy continues to expand despite elevated inflation, complicating the monetary policy outlook. The Fed is closely monitoring both spending and inflation data after raising interest rates in September for the first time in three years.
Attention will now turn to the September jobs report, due on Friday. In the coming weeks, investors will also receive further data on inflation and consumer conditions, providing a more complete picture of the economy ahead of the Fed’s 28 October policy decision. The current data therefore point to an economy that remains resilient despite higher interest rates and inflation, while leaving the Fed with limited room to ease policy quickly unless price pressures continue to moderate.
 Source: xStation5
Source: XTB Research, Macrobond



Economic Calendar: Wall Street Awaits PCE Data and Micron Earnings (30.08.2026)



Morning Wrap: AI drives Nikkei 225 gains, oil prices decline (30.09.2026)


Daily summary: Wall Street sentiment weakens amid hawkish Fed remarks 🚩 USDIDX at its highest level since July 24


US Open: Nasdaq tries to recover loses 🗽 Fair Isaac shares in panic
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.