

- Lisa Cook surprised observers by joining the camp advocating for a rate hike.
- The US dollar weakened slightly and 2-year Treasury yields fell by 8 bps to 4.70% following the meeting.
- The Fed plans to reduce interest rate decisions to seven per year in 2027 and six per year in 2028.
- Markets price an 85% probability of a rate hike at the December meeting.
The first four meetings under Warsh's leadership brought substantial volatility to the markets. However, with the picture becoming increasingly clear, it is hardly surprising that investors are reacting with growing calm.
The October decision appeared relatively obvious – for two key reasons.
First, the midterm elections are fast approaching and will determine the direction of US economic policy and, to a lesser extent, foreign policy (formally, voting is already underway via early voting). During the press conference, Warsh distanced himself from any political influence on today's decision, though he noted that the next six weeks will significantly clarify the situation facing the US.
Second, the central bank did not wish to signal to the market that it was falling behind the curve on inflation and forced into rapid monetary tightening – which is precisely how rate hikes at two consecutive meetings would likely have been interpreted.
The vote breakdown
The 10–2 vote split comes as no major surprise. Many analysts expected dissent from the consensus by the likes of Beth Hammack, Lorie Logan, or Neel Kashkari. What did come as a surprise, however, was Lisa Cook joining the camp advocating for a rate hike.
Yes, the very same Lisa Cook who was "dismissed" from her post by Donald Trump in 2025. The quotation marks are deliberate here, as the decision was later deemed unlawful by the Supreme Court. However, this was not the final resolution of the matter: Cook is scheduled to attend a hearing at the White House on 5 November.
Warsh's press conference and market reaction
As has become custom, Warsh's statements were rather vague and offered little substance for assessing the current environment. However, two remarks stand out, providing a valuable counterweight to the uninformative formula regarding the rigid inflation target the Committee must deliver:
- "There is broad agreement that monetary medicine is taking effect."
- "The economy is strong and moving in the right direction. Most of my colleagues do not view it as being 'overheated'."
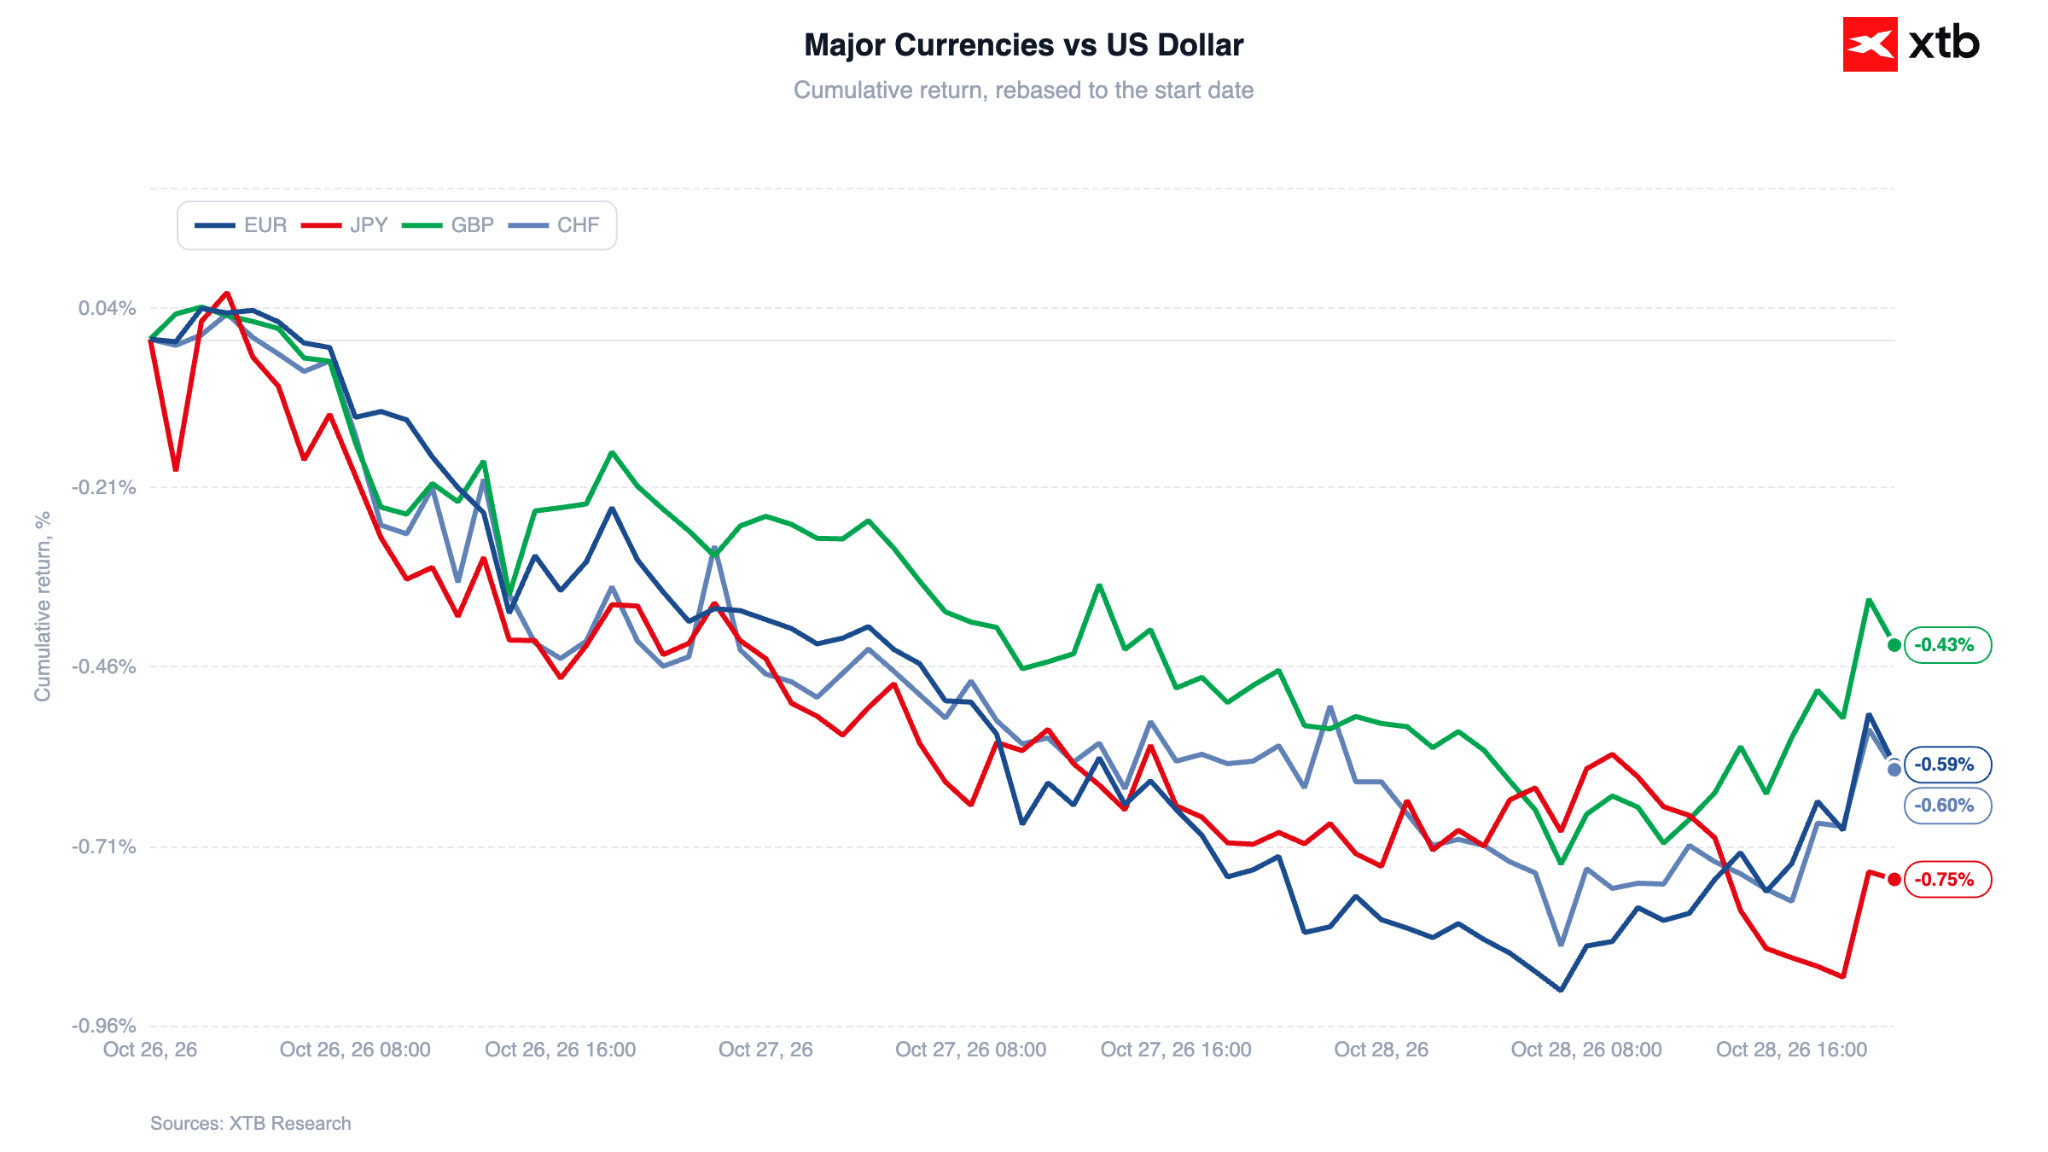
These comments can be interpreted as slightly less hawkish than what the market had priced in prior to the meeting. This is reflected in the modest weakness in the US dollar, which slipped both against a trade-weighted basket of currencies (-0.2%) and the euro (-0.3%). It is further evidenced by a decline in 2-year US Treasury yields, falling by around 8 bps to 4.70%.
Figure 1: Major Currencies vs US Dollar (26.10.2026 - 28.10.2026)
 Source: XTB Research, 28.10.2026
A new schedule
Perhaps the most groundbreaking announcement was the change to the FOMC meeting schedule starting next year. While there will still be eight meetings annually, not all will be decision-making meetings. In 2027, one meeting will be dedicated to strategic deliberations on monetary policy, and in 2028, two meetings will be set aside for this purpose (ultimately reducing the number of interest rate decisions to six per year).
What lies ahead?
Today's decision does not settle the debate regarding the Fed's next move at the December meeting. Markets still lean towards a rate hike, albeit with somewhat less conviction than earlier in the day (pricing in an 85% probability down from 95%). A slight dip in rate expectations was also observed for subsequent months; while three further rate increases remain the baseline scenario, they are no longer fully priced in.
Much will depend not only on oil prices, but also on capital demand from hyperscalers, which shows no signs of abating. Despite high Treasury yields acting as a key benchmark for borrowing costs, commercial and industrial loan growth remains in double digits, while non-financial sector trade liabilities as a proportion of GDP stand at their highest level since the dot-com bubble.
Based on currently available data, and regardless of the outcome of the midterm elections, we expect an interest rate hike in December to alleviate market concerns over inflation. Subsequent actions will, in our view, depend largely on the election results and broader sentiment surrounding the AI revolution.
—
Michał Jóźwiak, Financial Markets Analyst at XTB



Daily Summary: Oracle drives the market higher, dollar weakens following Fed meeting (28.10.2026)
Time for a pause – what will determine the strength of the dollar? [Pre-FOMC Report]

BREAKING: Bank of Canada hikes for the first time in 3 years but signals caution on further moves



Market Wrap: Renewed confidence in AI drives stock market recovery (27.10.2026)
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.