


TAfter nearly a year and two months of waiting, the wait is finally over. Today’s release of Grand Theft Auto VI is an event you simply can’t escape—neon billboards have flooded the streets of Warsaw and Poland’s largest cities, in offices, the topic of the return to Vice City has dominated coffee-break conversations, and the demand for gaming hardware—combined with global component shortages—has sent console prices soaring, forcing latecomers to spend several thousand zlotys more than they would have just five months ago. Around the world, companies are giving employees a day off so they can “complete missions,” and insurance industry analysts are treating today’s launch as a global stress test for cloud and payment infrastructure.
From the perspective of pop culture and critics, GTA VI has already won. An average score of 99/100 on Metacritic (based on 150 reviews) places the Rockstar Games title on par with the legendary *The Legend of Zelda: Ocarina of Time*. However, for investors on Wall Street, today marks the moment when the euphoria begins to give way to cold, hard numbers. And it is precisely these numbers that pose the main threat to the stock price of the game’s publisher, Take-Two Interactive (TTWO).
Is Success Already Priced In? The Stock Market Paradox of a Market Debut
Although Take-Two’s stock jumped more than 6% on Wednesday in response to enthusiastic reviews, the company’s share price remains well below its all-time highs of around $264.79, which were reached during periods of peak market optimism.
This is a classic example of stock market mechanics: the market has been pricing in the success of GTA VI for months. Once the initial excitement over the graphics and the scale of the open world has died down, investors will stop asking whether the game is a masterpiece and will begin to ruthlessly assess just how much of that success has already been priced into the stock price.
The Hidden Margin Engine: The Ultimate Edition Phenomenon and the Online Mystery
However, the first hard data provide strong arguments for the optimists. According to estimates by the research firm Sensor Tower, even before the servers officially went live, the game had sold 17.07 million copies, generating $1.65 billion in revenue (of which 75%—or 12.73 million copies and $1.23 billion—came from PlayStation consoles, and 25% to Xbox). This means that with an estimated budget exceeding $1 billion, the production more than paid for itself even before launch day.
However, what is key to TTWO’s valuation is not the headlines about record sales themselves, but two details buried deep within the company’s financial model:
- Pricing Structure for the Ultimate Edition: The base edition of the game costs $79.99, but during pre-orders, the vast majority of players opted for the most expensive Ultimate Edition at $99.99. From an accounting perspective, the $20 surplus from each such purchase goes directly into the Recurrent Consumer Spending (RCS) category, which immediately boosts profitability and improves the revenue structure. The question is whether this extremely high share of premium versions will also hold true among the mass market of customers buying the game during the holiday season.
- The Potential of the New GTA Online: The previous installment, GTA V, sold a staggering 230 million copies, primarily thanks to the longevity of its online mode. Today, the market must assess to what extent TTWO’s valuation assumes rapid monetization of the new online ecosystem—including the GTA+ subscription and the official integration of role-play servers (FiveM / nopixel V).
The board's conservatism versus the appetite of investment banks
The most interesting developments will unfold when the results for the current calendar quarter (Q3 of the company’s 2027 fiscal year) are released, as the launch frenzy will coincide with the holiday shopping rush.
During its most recent earnings call, Take-Two’s management team, led by Strauss Zelnick, displayed surprising conservatism. Although the company raised its forecast for net bookings for the holiday quarter to $3.35–3.50 billion, it kept its full-year target unchanged at $8.0–8.2 billion. Mathematically, this would imply an almost complete decline in demand for GTA VI as early as the first quarter of 2027—a scenario that no one in the market believes will happen.
This deliberately low bar (known as “sandbagging”) means that the actual results for the fourth calendar quarter could turn out to be astronomical and easily crush the company’s own official estimates. The real test for Take-Two’s stock price, however, will not be beating management’s conservative forecasts, but rather meeting Wall Street’s sky-high expectations. Since brokerage firms are already factoring sales of 30 million copies and $3 billion in revenue by the end of December into their models, the bar for stock market bulls is set much higher than one might think after reading the company’s press releases alone.
GTA VI is undoubtedly making entertainment history today, but for Take-Two shareholders, the real high-stakes game is just beginning. The coming weeks will show whether this massive box-office success will translate into a sustained rally that pushes the stock price to new highs, or whether investors—in keeping with an old stock market adage—will decide to take profits just when literally everyone is talking about the game.
Take-Two Interactive Stock - Technical Analysis
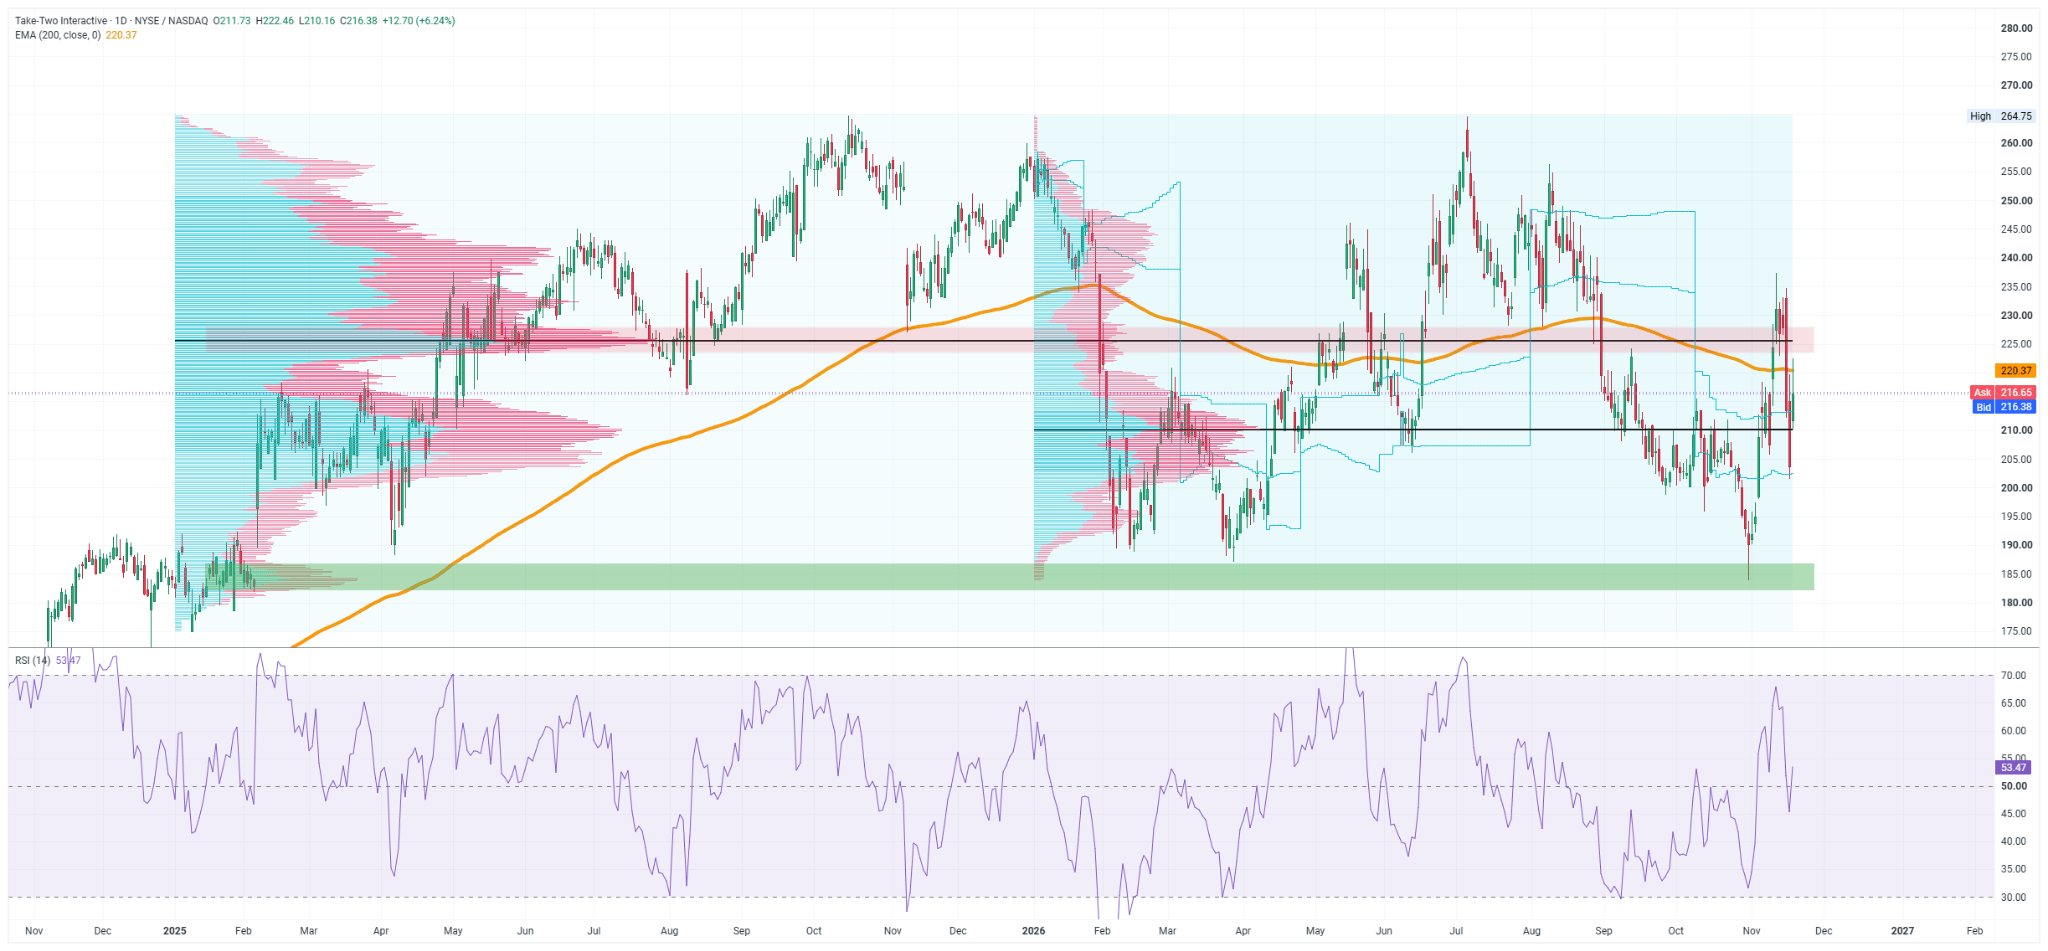
The daily (1D) chart for Take-Two Interactive (TTWO) stock shows a clear clash between post-release euphoria and a strong supply barrier. After a dynamic rebound, the stock closed around $216.38; however, the long upper wick of the candlestick (session high at $222.46) indicates that the market has yet to resolve the key battle to return to the long-term uptrend.
- Key resistance and test of the 200-session EMA (220.37–228.00 USD): The first hurdle for buyers remains the 200-session exponential moving average (EMA 200), which stands at 220.37 USD. Although the bulls managed to breach it during the last session, selling pressure pushed the price back below this line. Immediately above the moving average lies the chart’s most significant resistance zone (the red band at $224.00–$228.00), which includes the primary point of control (POC) from the past two years. It was this barrier that halted the previous breakout attempt in the first half of November.
- Local equilibrium zone (approx. $210.00–$210.50): The local Point of Control (POC) for the 2026 profile, marked by the black line around $210.50, has become an important short-term support level. The most recent candle opened above this level ($211.73), tested it from above (low of $210.16), and rebounded clearly, confirming demand activity in this zone.
- Strategic demand zone (182.00–187.00 USD): In the event of profit-taking following the launch (“sell the news”) and a loss of support at 210 USD, the green demand zone in the 182.00–187.00 USD range remains the key reference point. It marks the lower boundary of a broad consolidation range and the base of the volume profiles, which was successfully defended at the turn of October and November.
- Momentum (RSI) and Breakout Prospects: The daily RSI (14) is currently at a neutral level of 53.47 points, indicating that the market is not overbought and leaving plenty of room for the uptrend to continue. From a technical perspective, only a sustained breakout and a close above the supply cluster at $224.00–$228.00 will open the way for buyers through the area of lower volume toward the all-time highs at $264.79.


Economic Calendar: Trump-Xi Jinping-Putin summit ongoing, time for Walmart results (19.11.2026)


Morning Wrap: Time for the largest stock market debut in history (19.11.2026)



📉Daily Summary: Hawkish Fed and fading optimism around Nvidia hit markets. Gold near 3700


🔴US500 decrease ahead of FOMC minutes
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.