


What to expect from today's decision?
The baseline scenario for today's event is a “dovish pause with a hawkish tone”. The rate is almost certain to remain at 3.75%, a level maintained since December last year. The market assigns only a ~12% probability to a rate hike. The key aspect of today's decision will therefore be the rhetoric and the vote split, rather than the rate itself, as keeping rates unchanged is fully priced in.
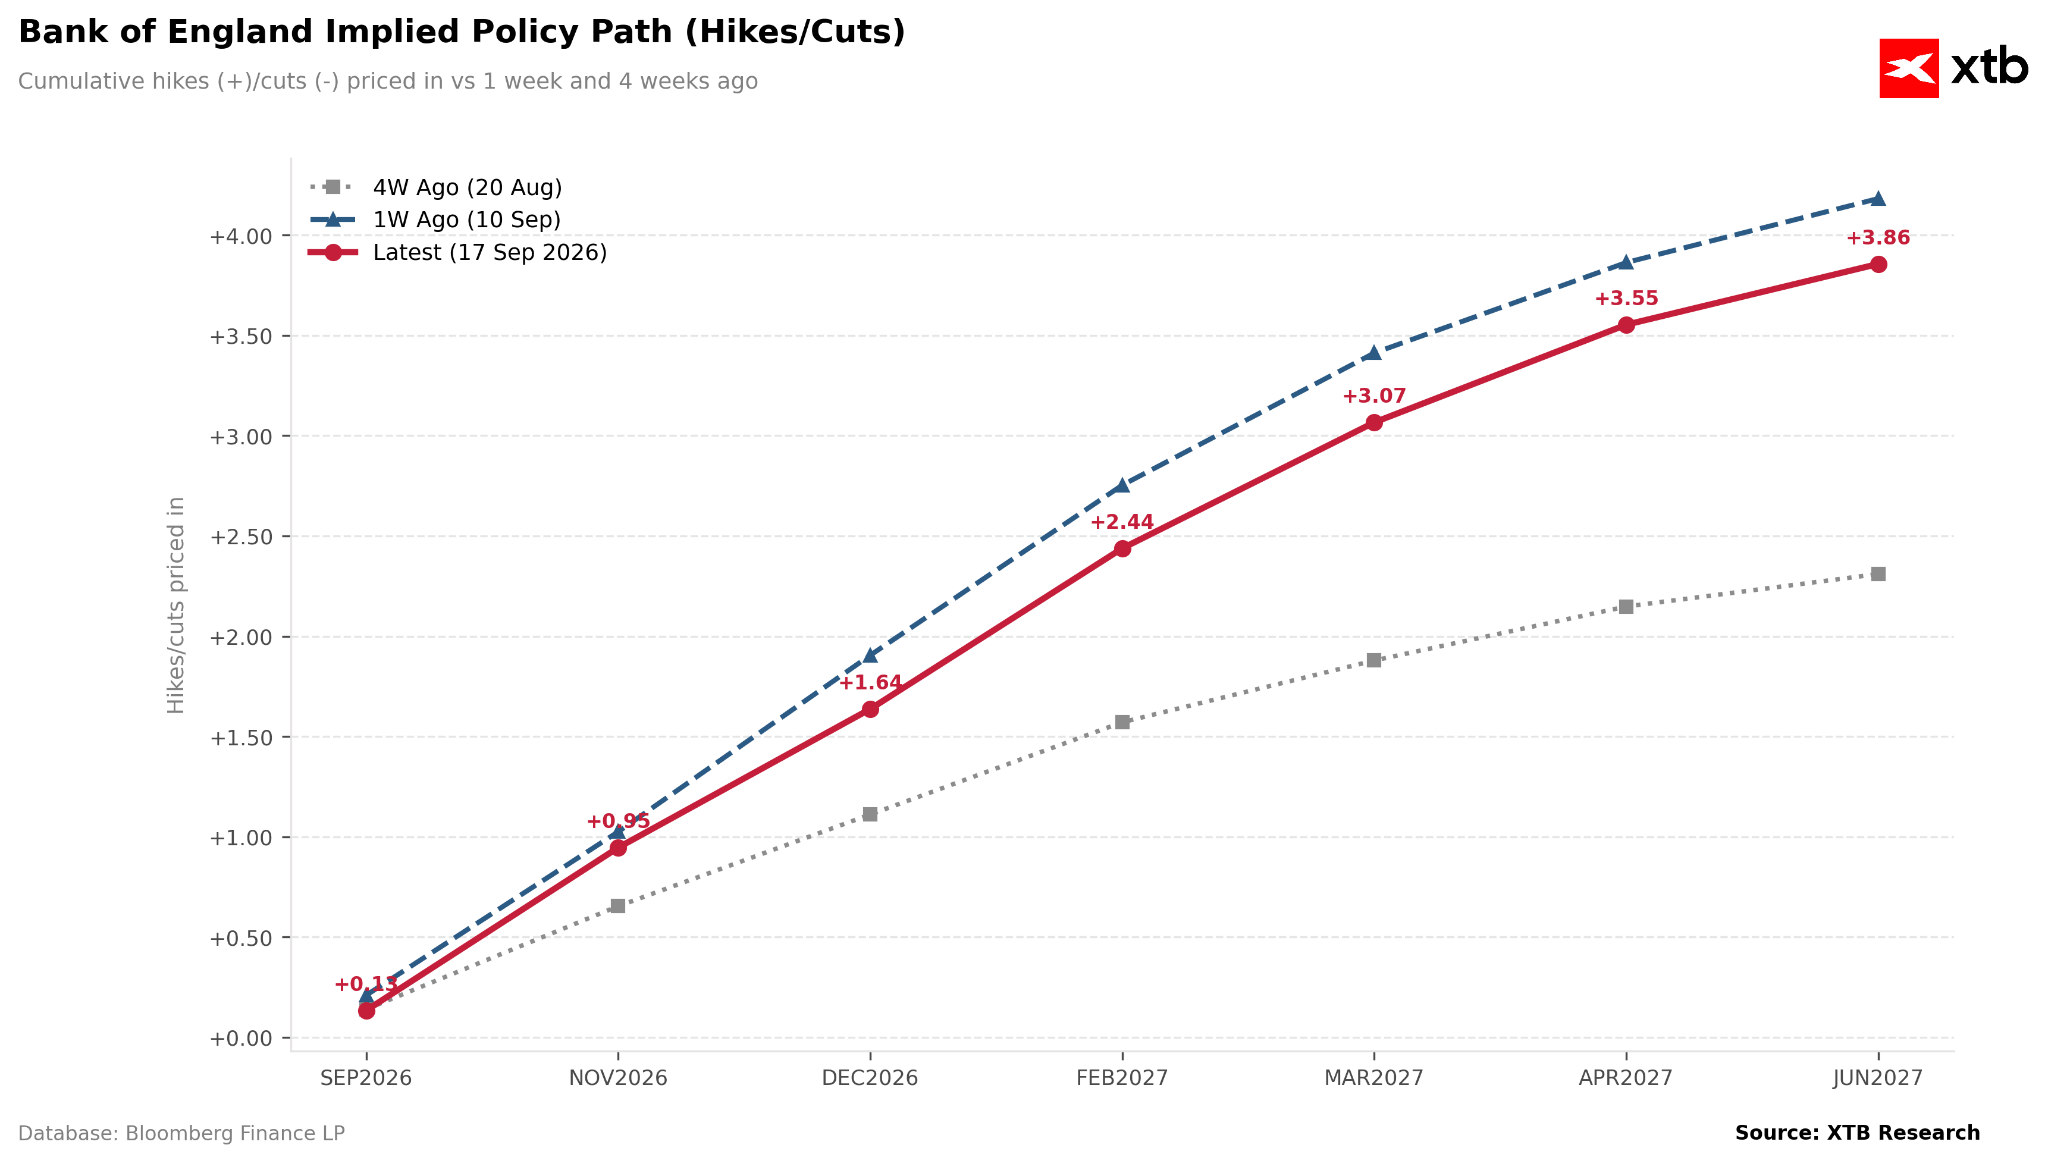 The market points to a nearly full rate hike only in November. Interestingly, the rate hike path was higher a week ago. Source: Bloomberg Finance LP, XTB
Key points to watch
- Vote split (most important): consensus is 6-3 in favor of a hold, identical to July. Three hawks: Chief Economist Huw Pill, alongside Megan Greene and Catherine Mann, favor a "preemptive" rate hike, citing fears of a wage-price spiral. A fourth vote for a hike (some economists point to Clare Lombardelli) would be a clear hawkish signal.
- Statement language: risks are tilted toward a sharp, hawkish message: energy prices are rising, and the market is already pricing in hikes.
- QT: alongside the rate decision, the BoE will announce its bond sales plan for the coming year. The expected slowdown in pace is from £70bn to £50bn. Reports suggest the Bank might pause long-term gilt sales to avoid competing with government issuance: this could be particularly relevant for the long end of the curve and the pound.
Macro background
- Inflation picked up to 3.1% YoY in August (core stable at 2.6%). The BoE warns that CPI could reach ~4% in early 2027, driven partly by a ~25% jump in energy bills in January and the impact of the Middle East conflict, which is boosting oil and fuel prices.
- The counterweight is a weak labor market: unemployment is near a 5-year high. This remains the primary argument for waiting.
- The BoE's July forecasts are already outdated (having assumed 2.8% inflation in August), so upward revisions to inflation and growth projections are expected.
What's next this year?
The market prices in the first rate hike in November as the start of a cycle leading to 4.75% by mid-2027. An important nuance: the implied path has cooled slightly: from +4.17 to +3.86 cumulative hikes by June '27 (a week-over-week decline). Hawkish expectations are already softening somewhat, lowering the bar for a "dovish surprise."
GBPUSD technical analysis (D1)
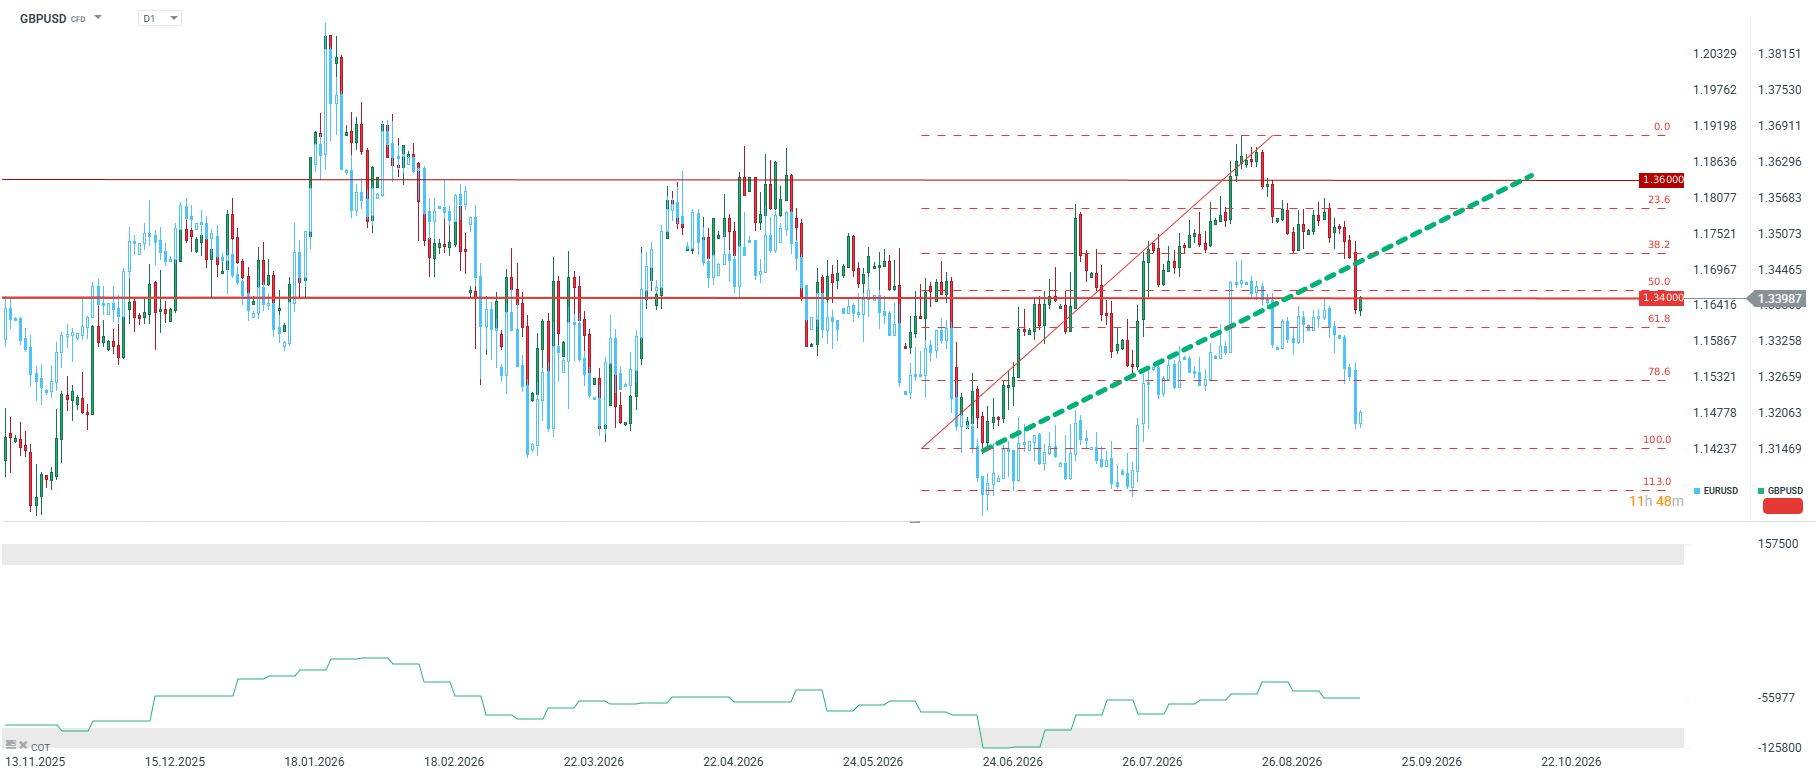
The pound entered the BoE decision on the defensive against the dollar, although profit-taking on the USD has been visible since the morning. After rebounding from June lows, the pair climbed along an ascending trendline, but recent sessions brought a dynamic drop: price broke through the trendline and subsequently fell below the 50% Fibonacci retracement level (1.3447), stopping only at key psychological and historical support at 1.3400. This level has historically defined consolidation bounds and currently serves as the bulls' defense line against further sell-offs.
Holding above 1.3400 keeps the door open for a recovery. The immediate hurdle is the newly lost 50% Fibo (1.3447); clearing it would open room toward the 38.2% Fibo (1.3507) and 23.6% Fibo (1.3568). On the downside, a break below 1.3400 would shift focus to the 61.8% Fibo (1.3326) as the primary target, and lower to the 78.6% Fibo (1.3266). A sustained move below this area would test the structure's base at the 100% Fibo (1.3147).
Ahead of the decision: a hawkish tone (a fourth vote for a hike, firm messaging, scaling back long-term gilt sales) would favor defending 1.3400 and attempting a move back above 1.3447 toward 1.3507–1.3568. A dovish surprise (stronger emphasis on labor market weakness, no additional hawk) would increase the risk of breaking 1.3326 and testing 1.3266. Since the rate hold is fully priced in, the direction will be determined by the statement tone and vote breakdown rather than the rate decision itself, with the pair standing right at a technical inflection point, setting up potential sharp volatility in either direction.



📊Daily Summary - Hawkish Fed raises rates and signals more. Dollar gains while gold falls


Hawkish move from the Fed! Warsh takes no prisoners in the fight against inflation. US500 at its lowest since August 3, and gold already below $4,300.

⬇️EURUSD below 1.15 following hawkish Fed
BREAKING: Fed’s Hawkish Hike Triggers Market Reversal: USD Soars as Gold and US500 Retreat
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.