


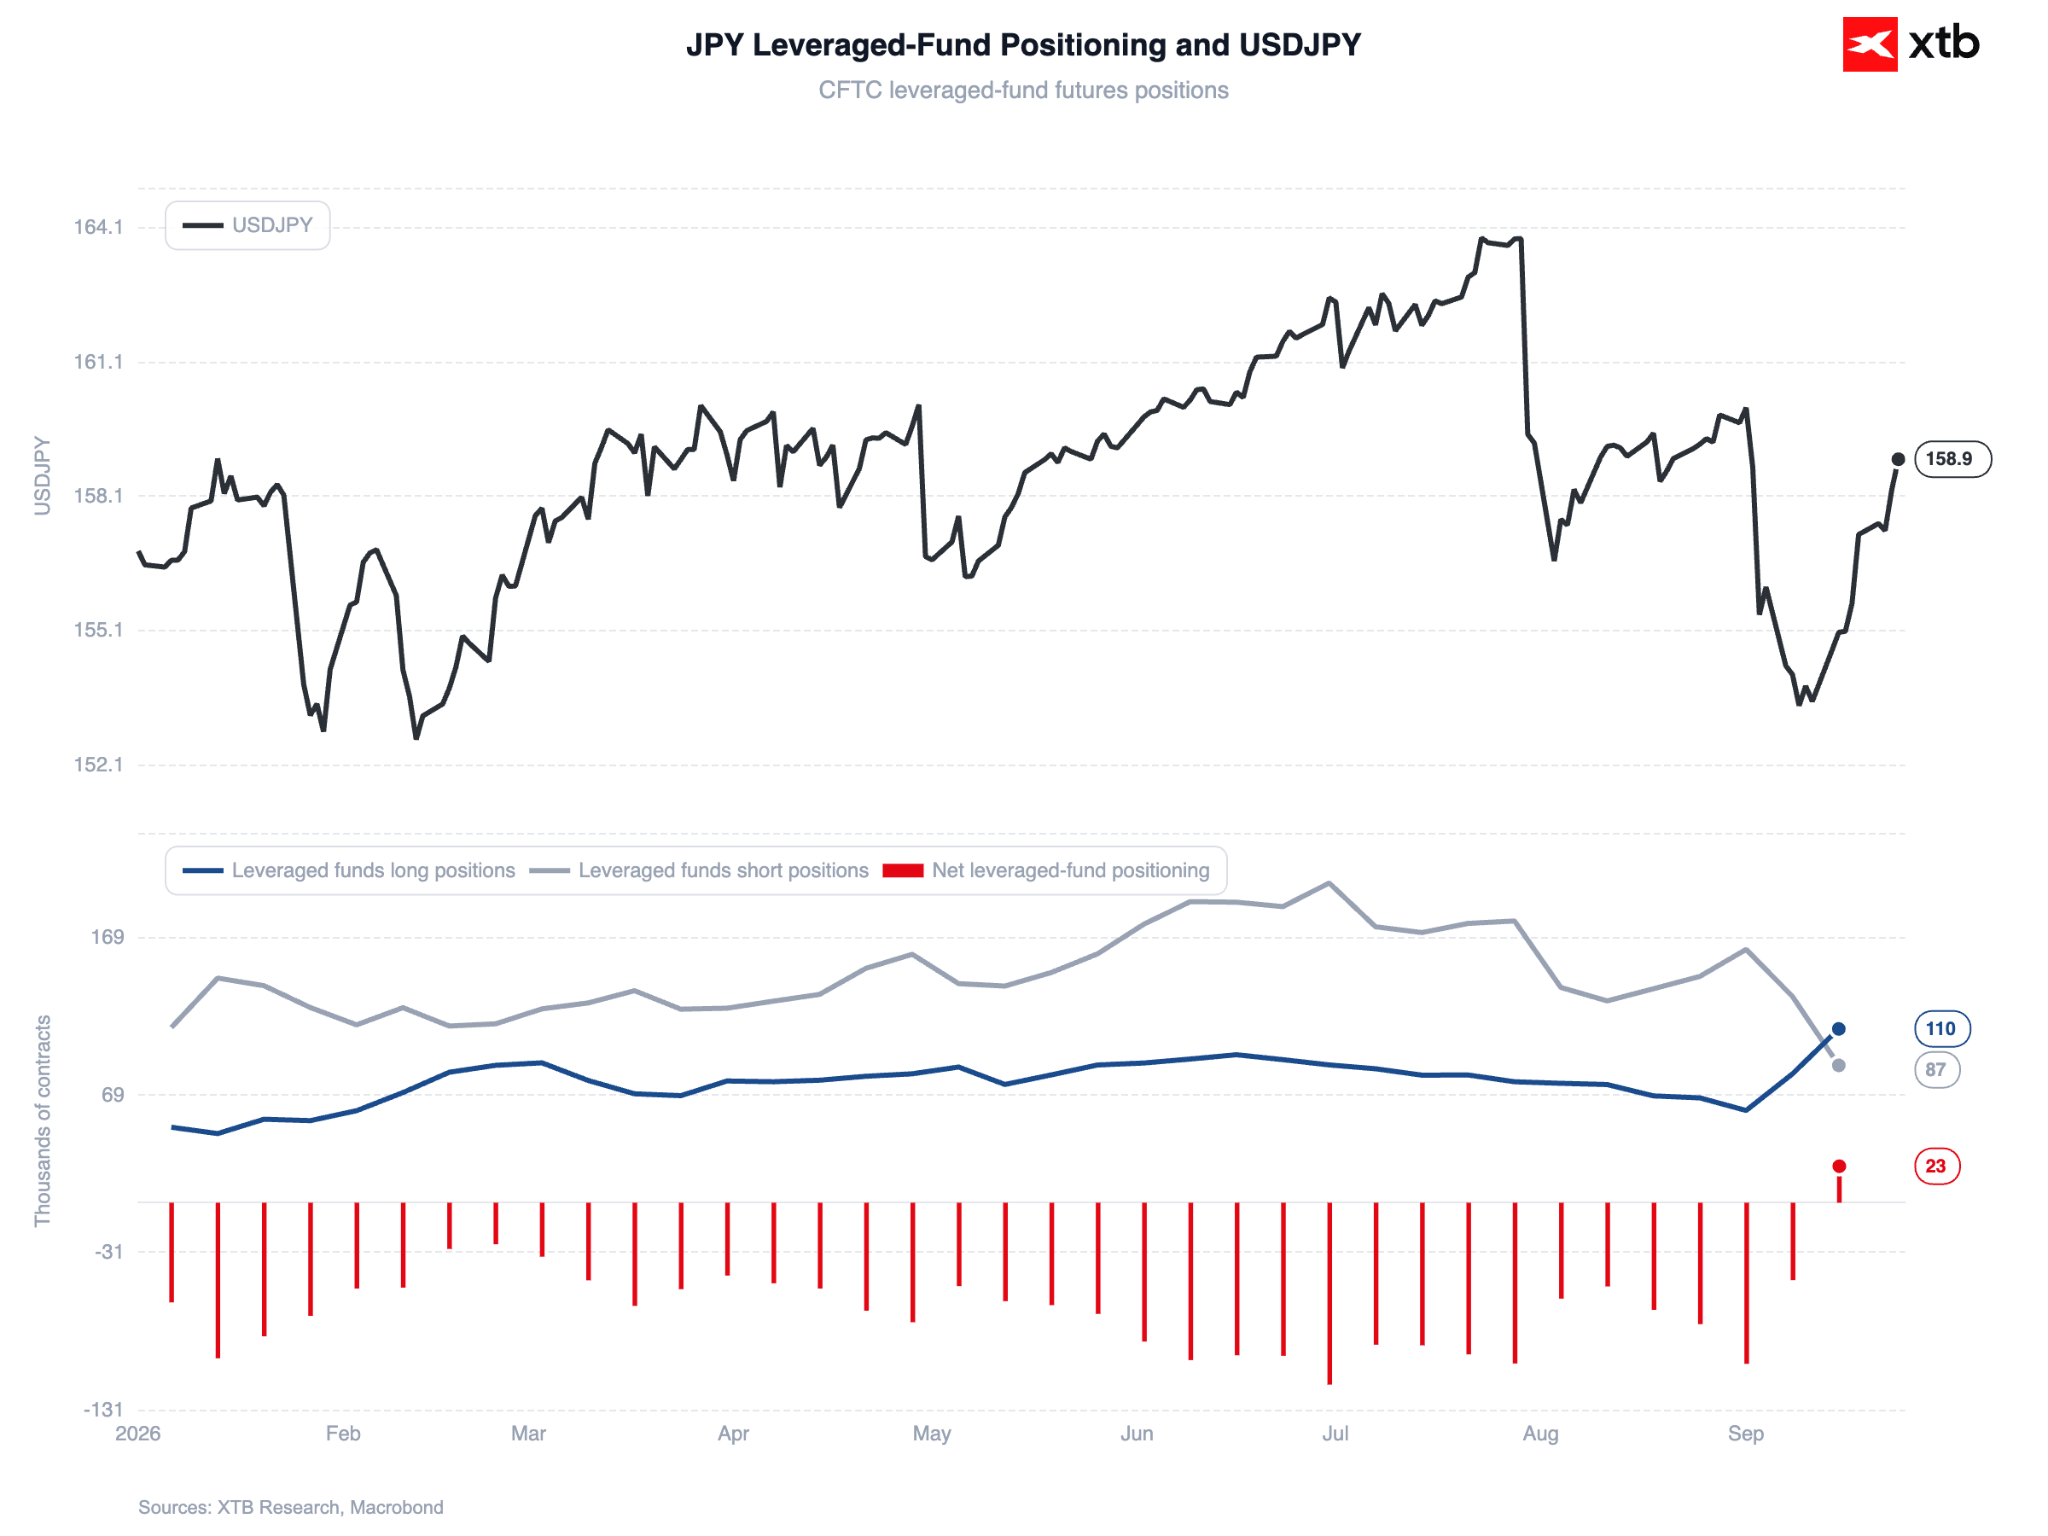
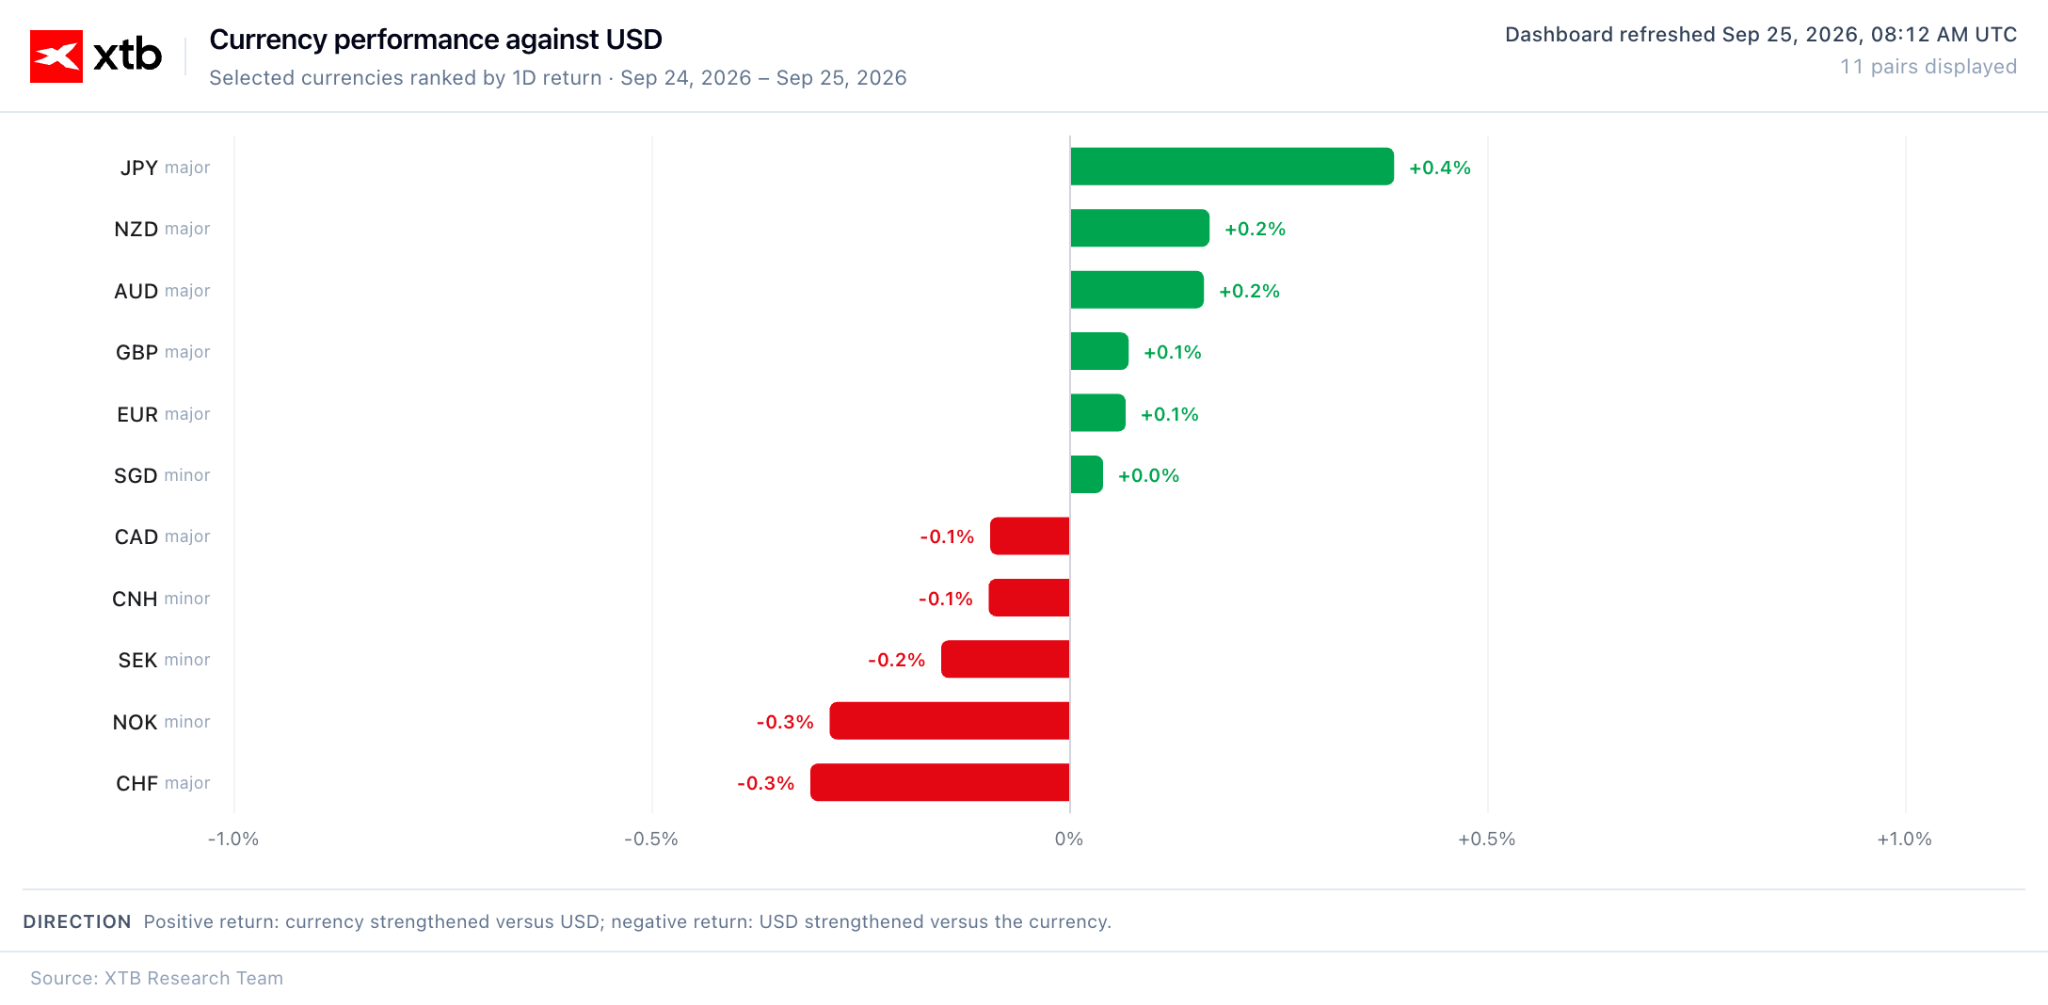
At present, the Japanese yen is recording its best session in over two weeks, appreciating against all other G10 currencies. The USDJPY pair is down 0.4%, approaching the 158 level.
Figure 1: USDJPY and CFTC Positioning (2026)
 Source: XTB Research, 25.09.2026
The reason?
Japanese Finance Minister Satsuki Katayama revealed that Donald Trump personally expressed concern regarding the weakness of the Japanese currency during a meeting with Prime Minister Sanae Takaichi in New York. She added that she will continue to coordinate actions with her American counterpart, Scott Bessent, "including in the area of foreign exchange rates".
Figure 2: Performance of G10 Currencies (25.09.2026)
 Source: XTB Research, 25.09.2026
Katayama's remarks coincided with equally significant statements from the Minister for Economic Growth Strategy, Minoru Kiuchi. He announced the end of the reflationary regime that relied on loose fiscal policy, a weak yen to support exports, and active economic stimulus through state expenditure (often referred to as Abenomics). As he highlighted, Japan has entered a phase of gradually rising prices and interest rates. The entire development can be viewed as a coordinated attempt to rebuild the credibility of the yen.
Fundamentals
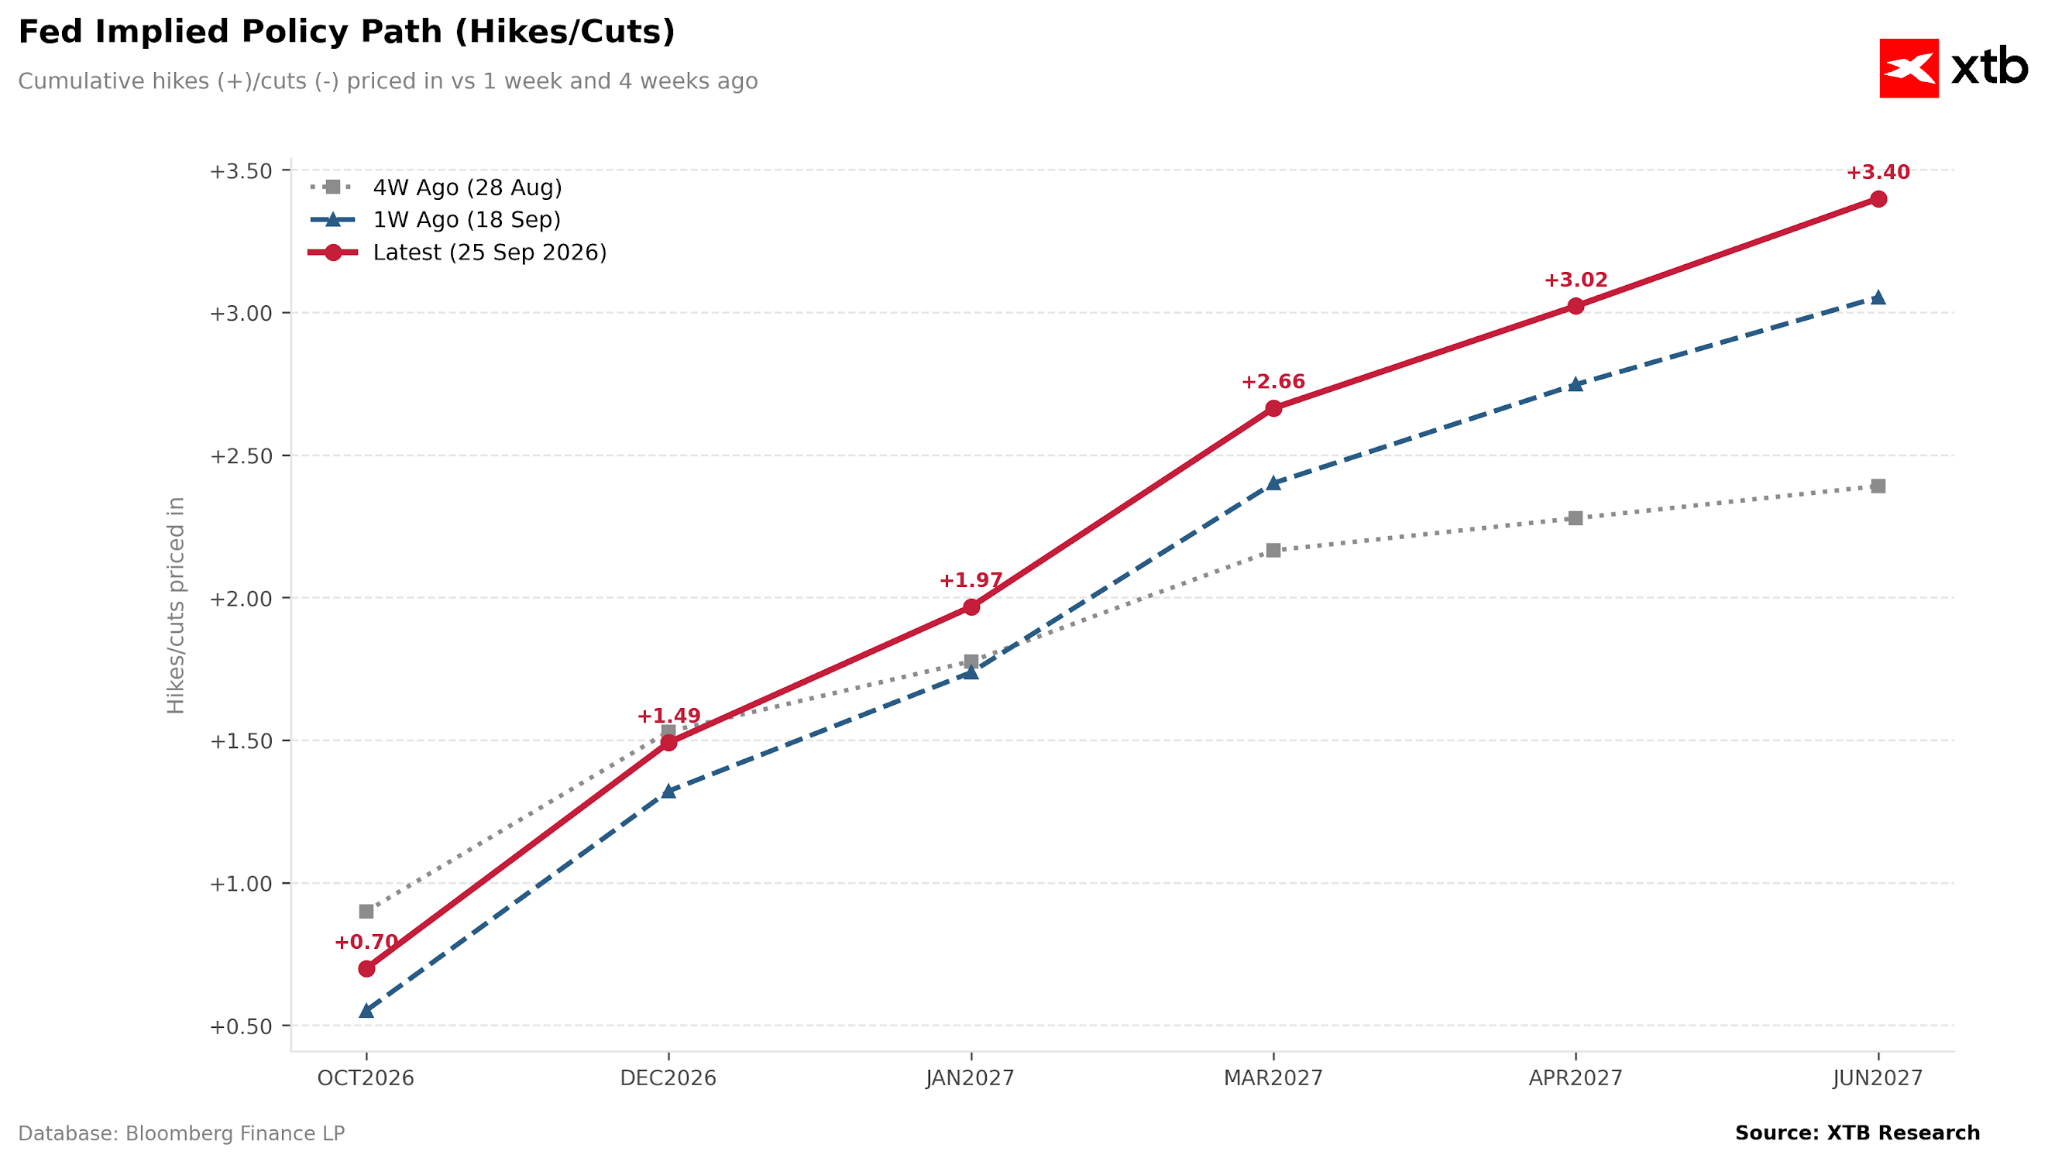
From a fundamental perspective, pressure on the Japanese currency was exerted by the recent upward revision in pricing regarding the Fed's interest rate hike path following the publication of exceptionally strong US PMI data. Overall, these represent the strongest figures in five years, consistent with GDP growth of around 5%. The market is increasingly pricing in a continuation of the rate-hiking cycle as early as the October meeting.
Figure 3: Market-Implied Path for Fed Interest Rates (2026-2027)
 Source: XTB Research, 25.09.2026
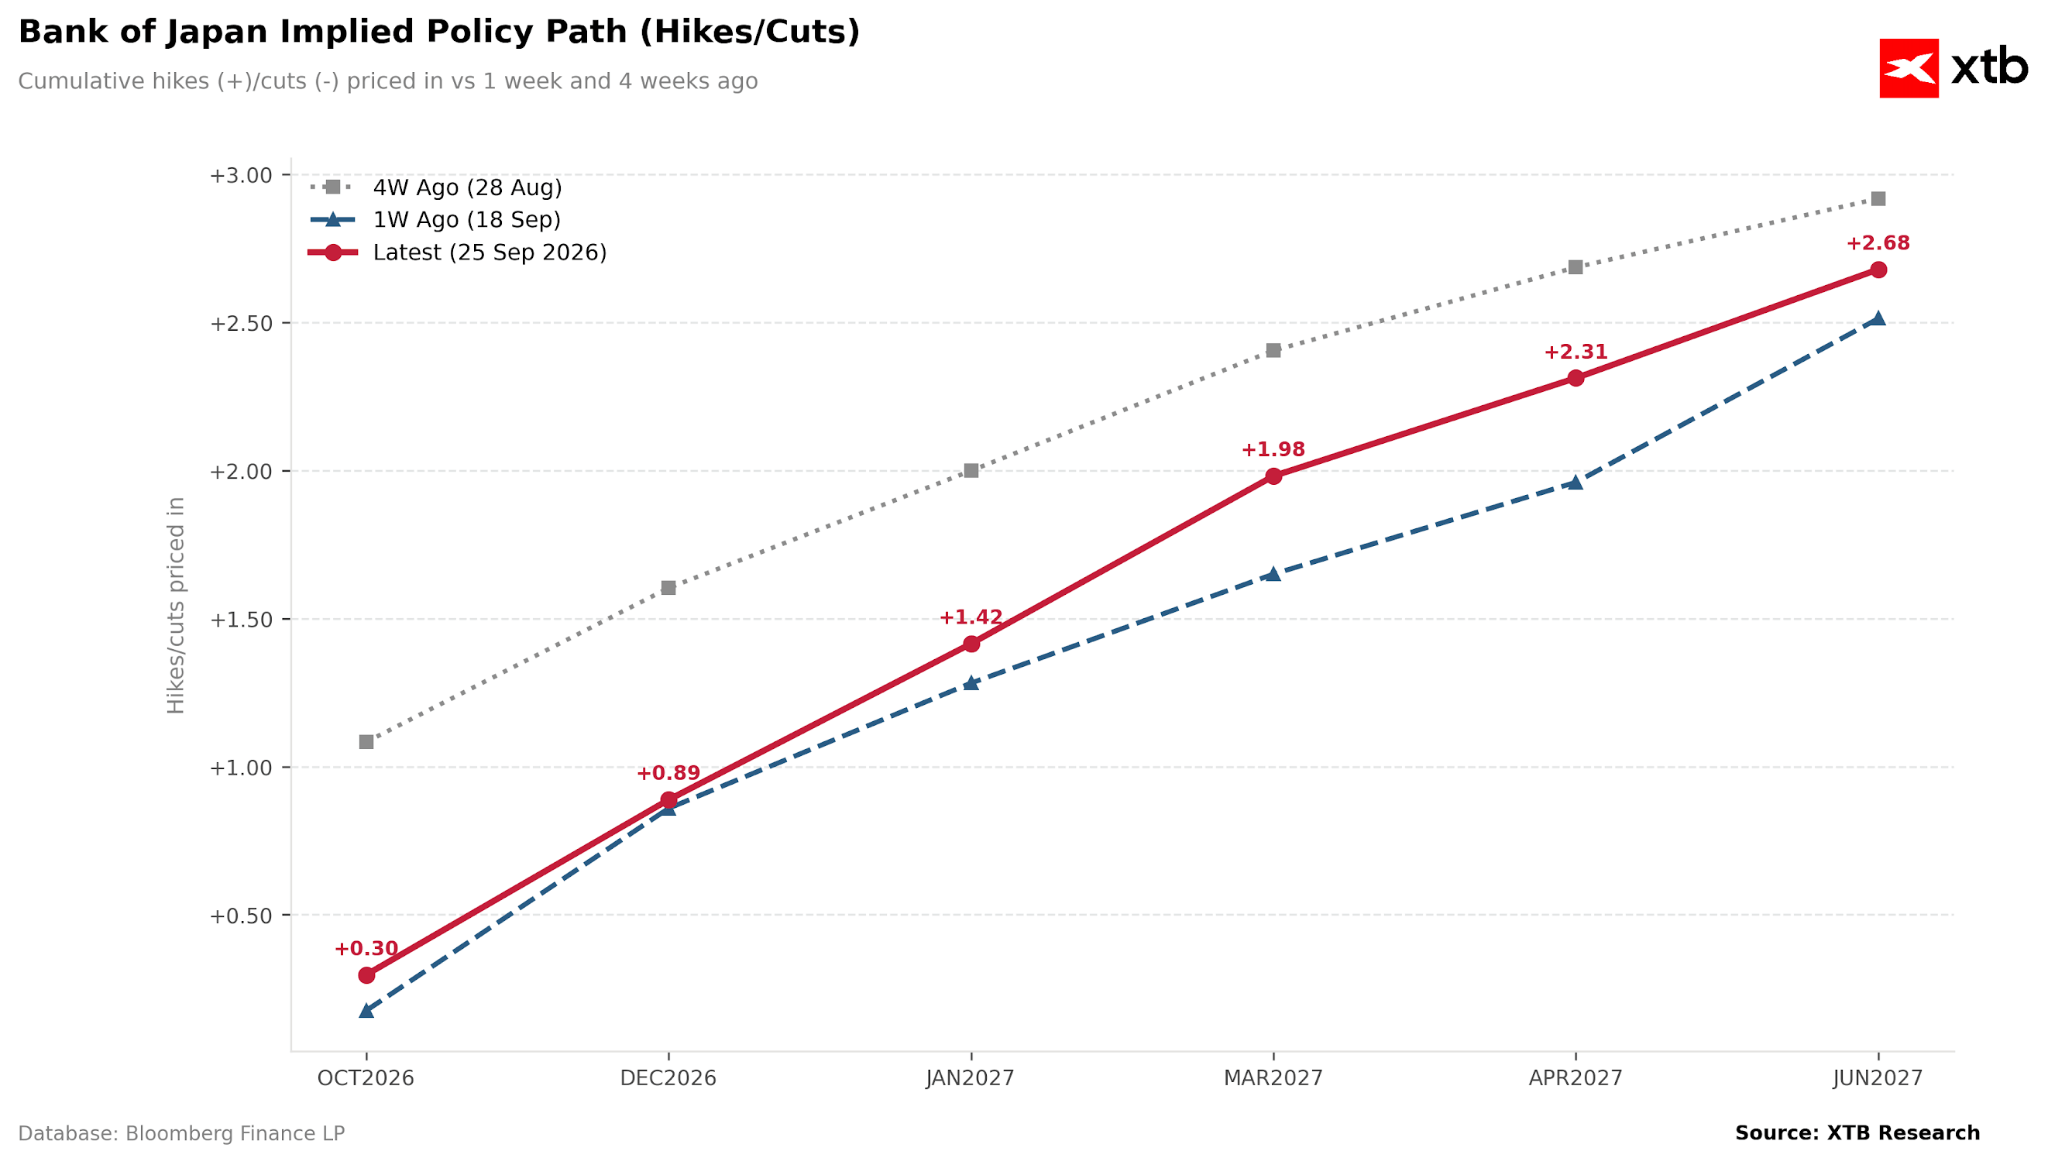
Investors are therefore eagerly anticipating data or comments from BoJ officials that could lead to a similar repricing regarding interest rate expectations in Japan.
Figure 4: Market-Implied Path for BoJ Interest Rates (2026-2027)
 Source: XTB Research, 25.09.2026
It is also worth noting that as one of the most closely watched currency pairs rises further, the risk of intervention increases. Officials have ceased announcing these in advance for some time now.
Technical Analysis
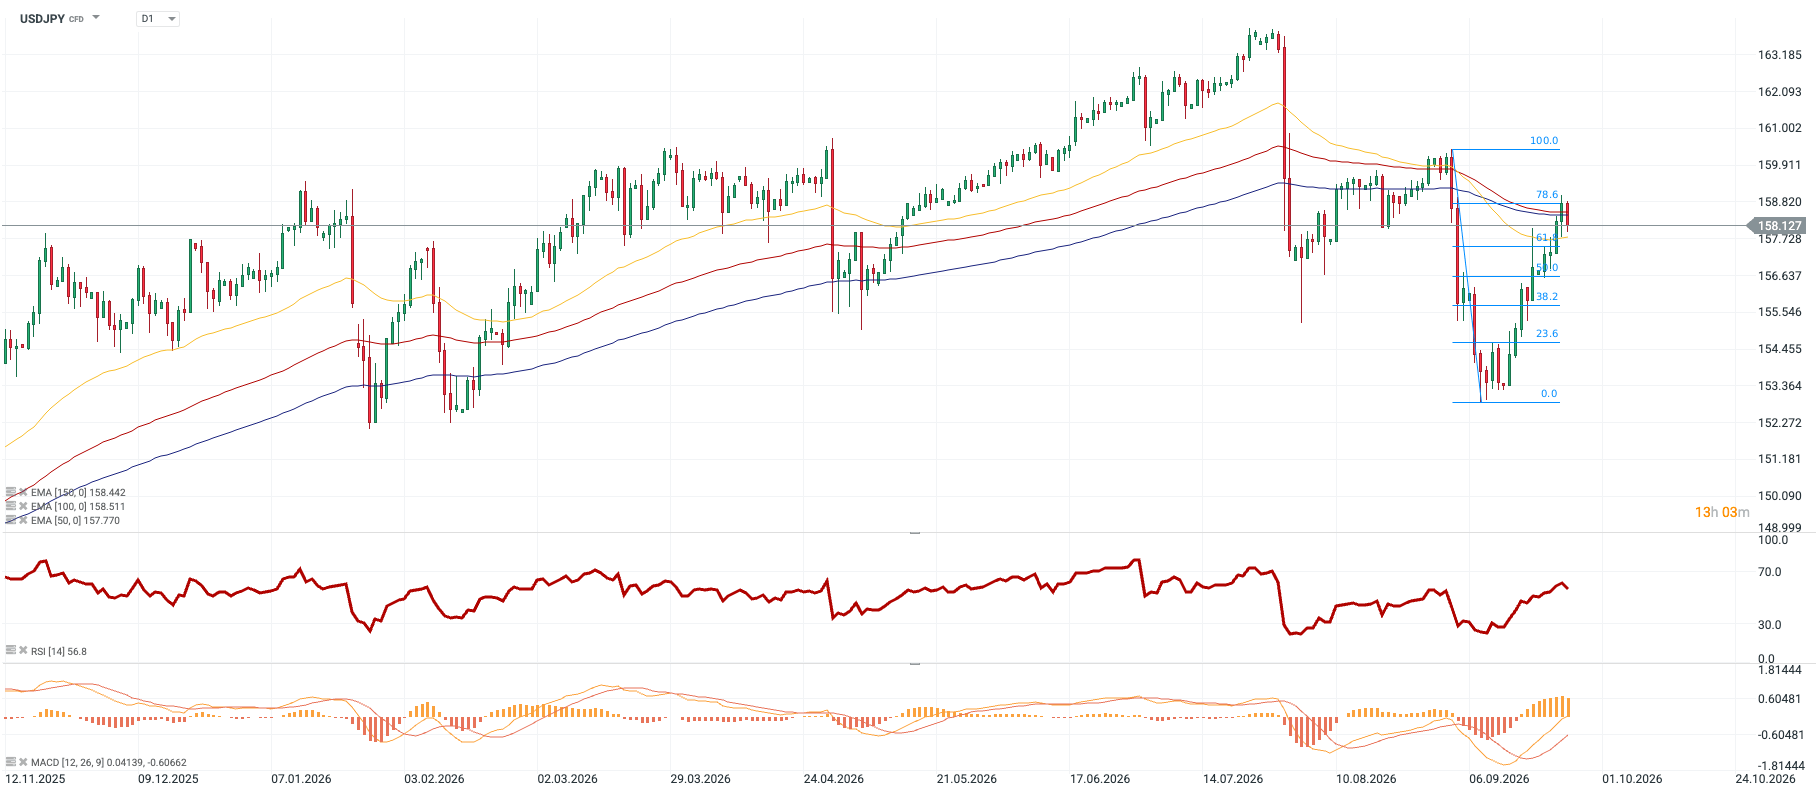
Figure 5: USDJPY [D1] (12.11.2025-25.09.2026)
 Source: XTB, 25.09.2026
The pair has managed to recover most of the losses from the sharp September sell-off. Currently, the rate is hovering around a tight cluster of moving averages, specifically the 50, 100, and 150 EMAs. A breakout and sustained hold above this zone would open the path towards the 78.6% Fibonacci retracement level and the psychological 160 level, the area where coordinated intervention took place during the summer.
The RSI at 56.8 confirms renewed bullish momentum, having moved out of deep oversold territory (below 30 at the turn of August and September) and now trading in the upper half of the neutral range.
—
Michał Jóźwiak, Financial Markets Analyst at XTB


Economic Calendar: Trump-Xi summit yields no breakthrough (25.09.2026)



Morning Wrap: Oil pulls back following reports of Washington-Tehran talks (25.09.2026)


Market Wrap: Further rise in oil prices weighs on European stocks (24.09.2026)

Bond yields highest since 2007
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.