

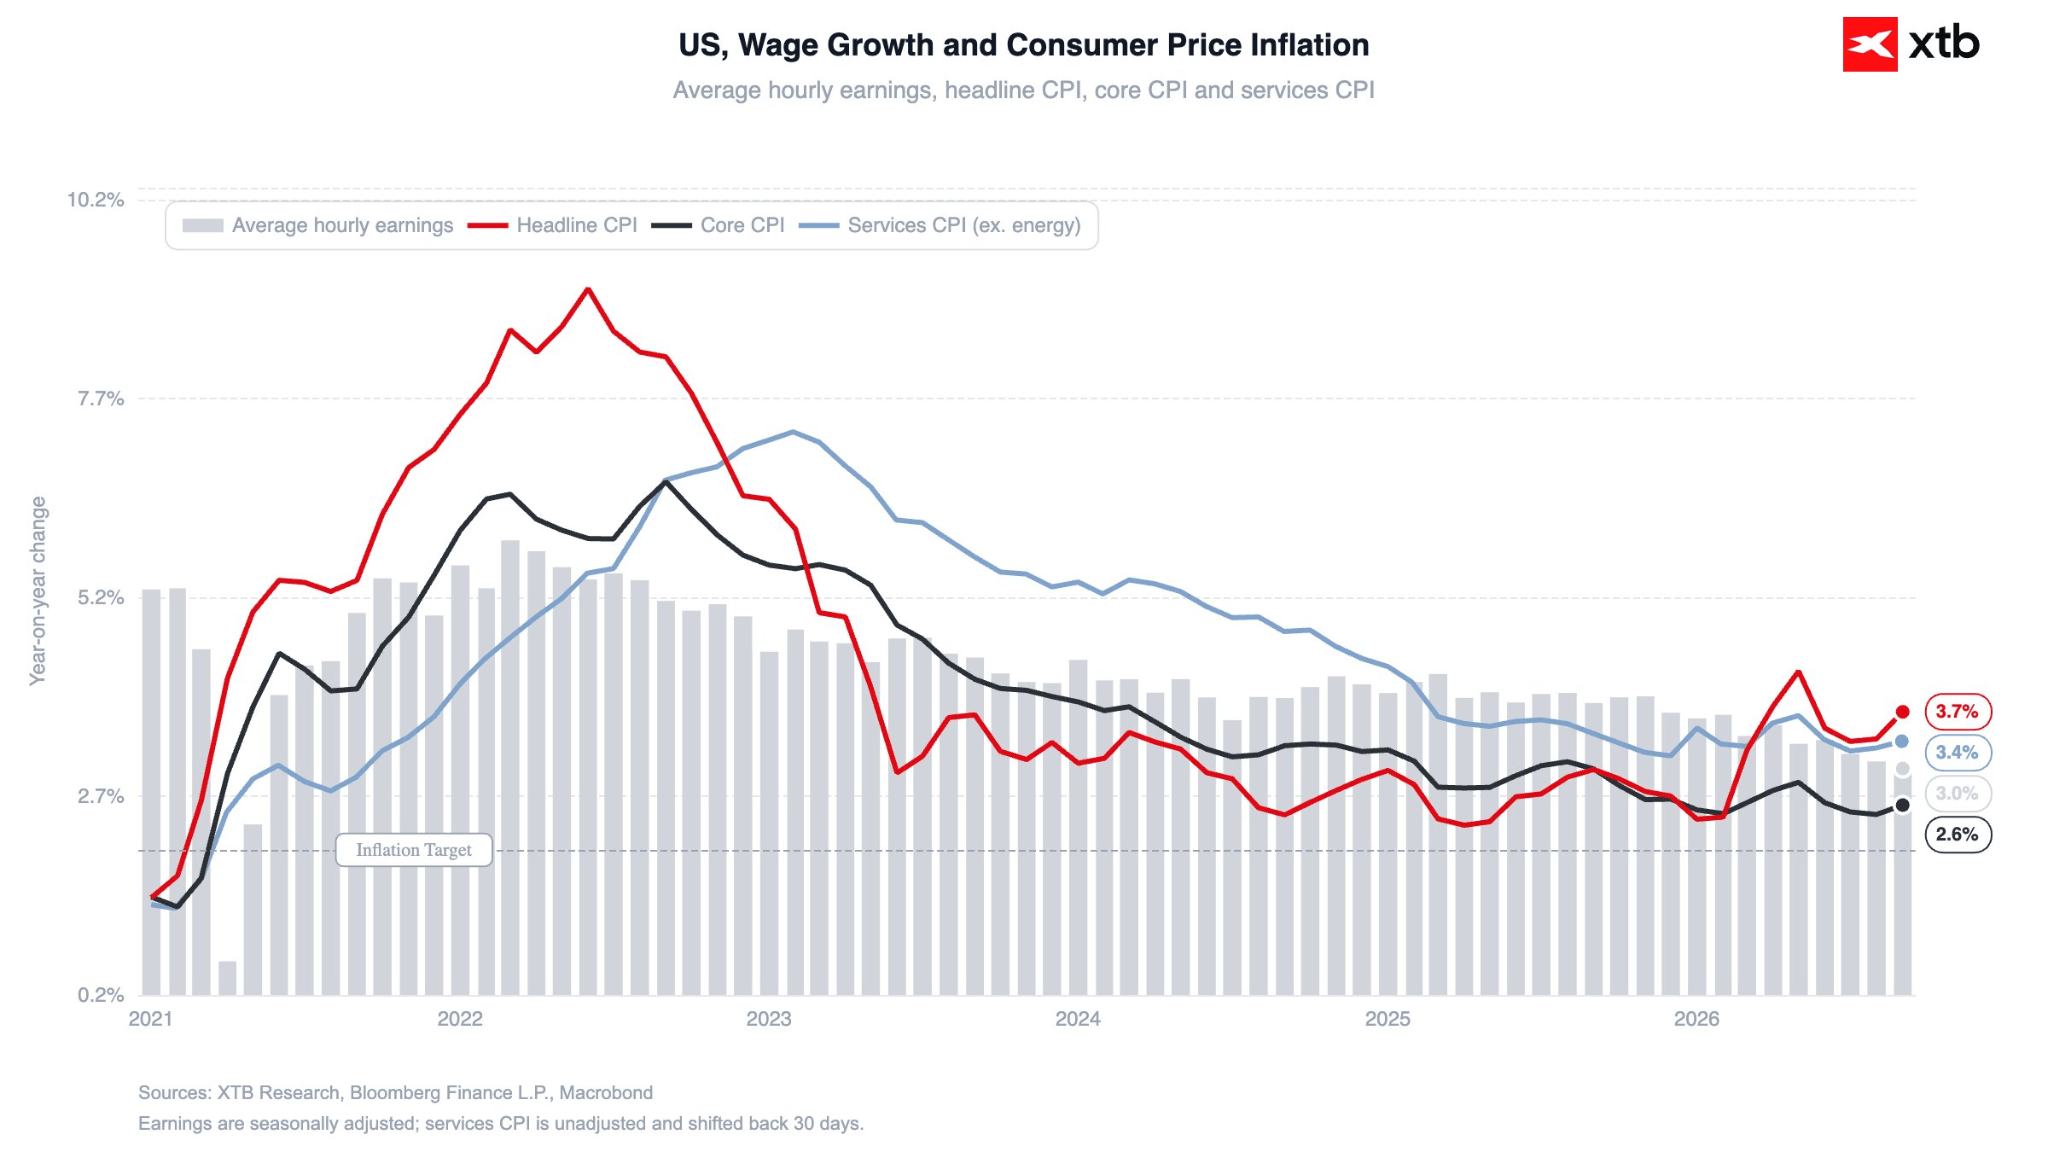
- US headline CPI inflation rose to 3.7% and core inflation reached 2.6% in September.
- Markets raised the probability of an October Fed rate hike to 50%.
- Benchmark 10-year US treasury yields touched 5.33% following the inflation release.
- The S&P 500 fell 0.8% and the Nasdaq 100 dropped 1.1% amid rising yields.
- The EURUSD currency pair weakened by nearly 0.8% toward the 1.11 level.
The most eagerly anticipated macroeconomic release of the week is behind us: the September CPI inflation figures from the United States.
Both the headline (3.7%) and core (2.6%) measures surprised to the upside, driving a sharp increase in market bets that the Fed will continue its monetary tightening cycle as early as October. The market-implied probability of such a move currently stands at around 50% (up from just 20% priced into futures contracts yesterday).
Figure 1: US CPI Inflation and Wage Growth (2021 - 2026)
 Source: XTB Research, 14.10.2026
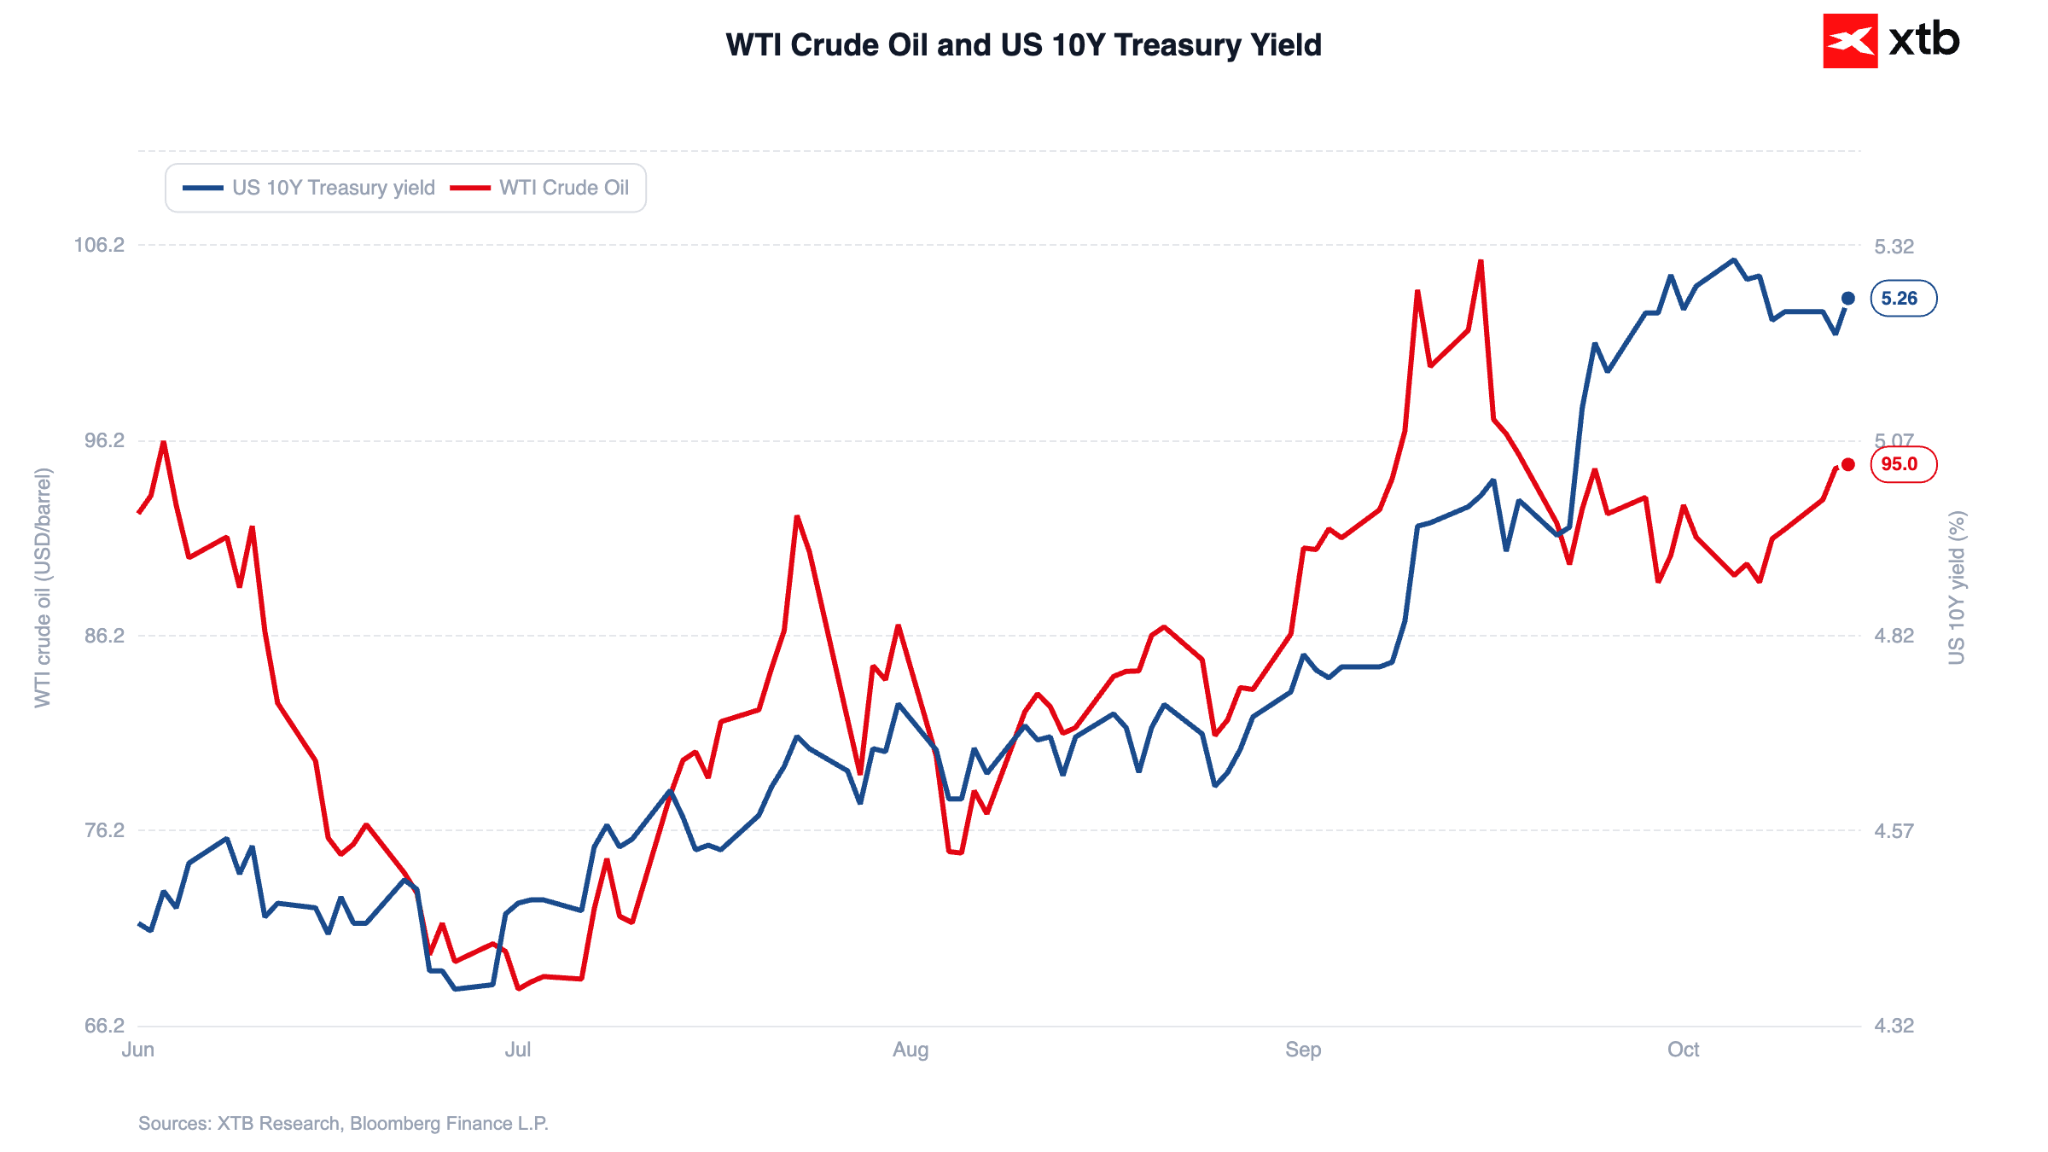
Naturally, this triggered an advance in US treasury yields. Benchmark 10-year yields briefly touched 5.33% before settling around 5.27%.
Figure 2: US 10-Year Treasury Yield and WTI Crude Oil (06.2026 - 10.2026)
 Source: XTB Research, 14.10.2026
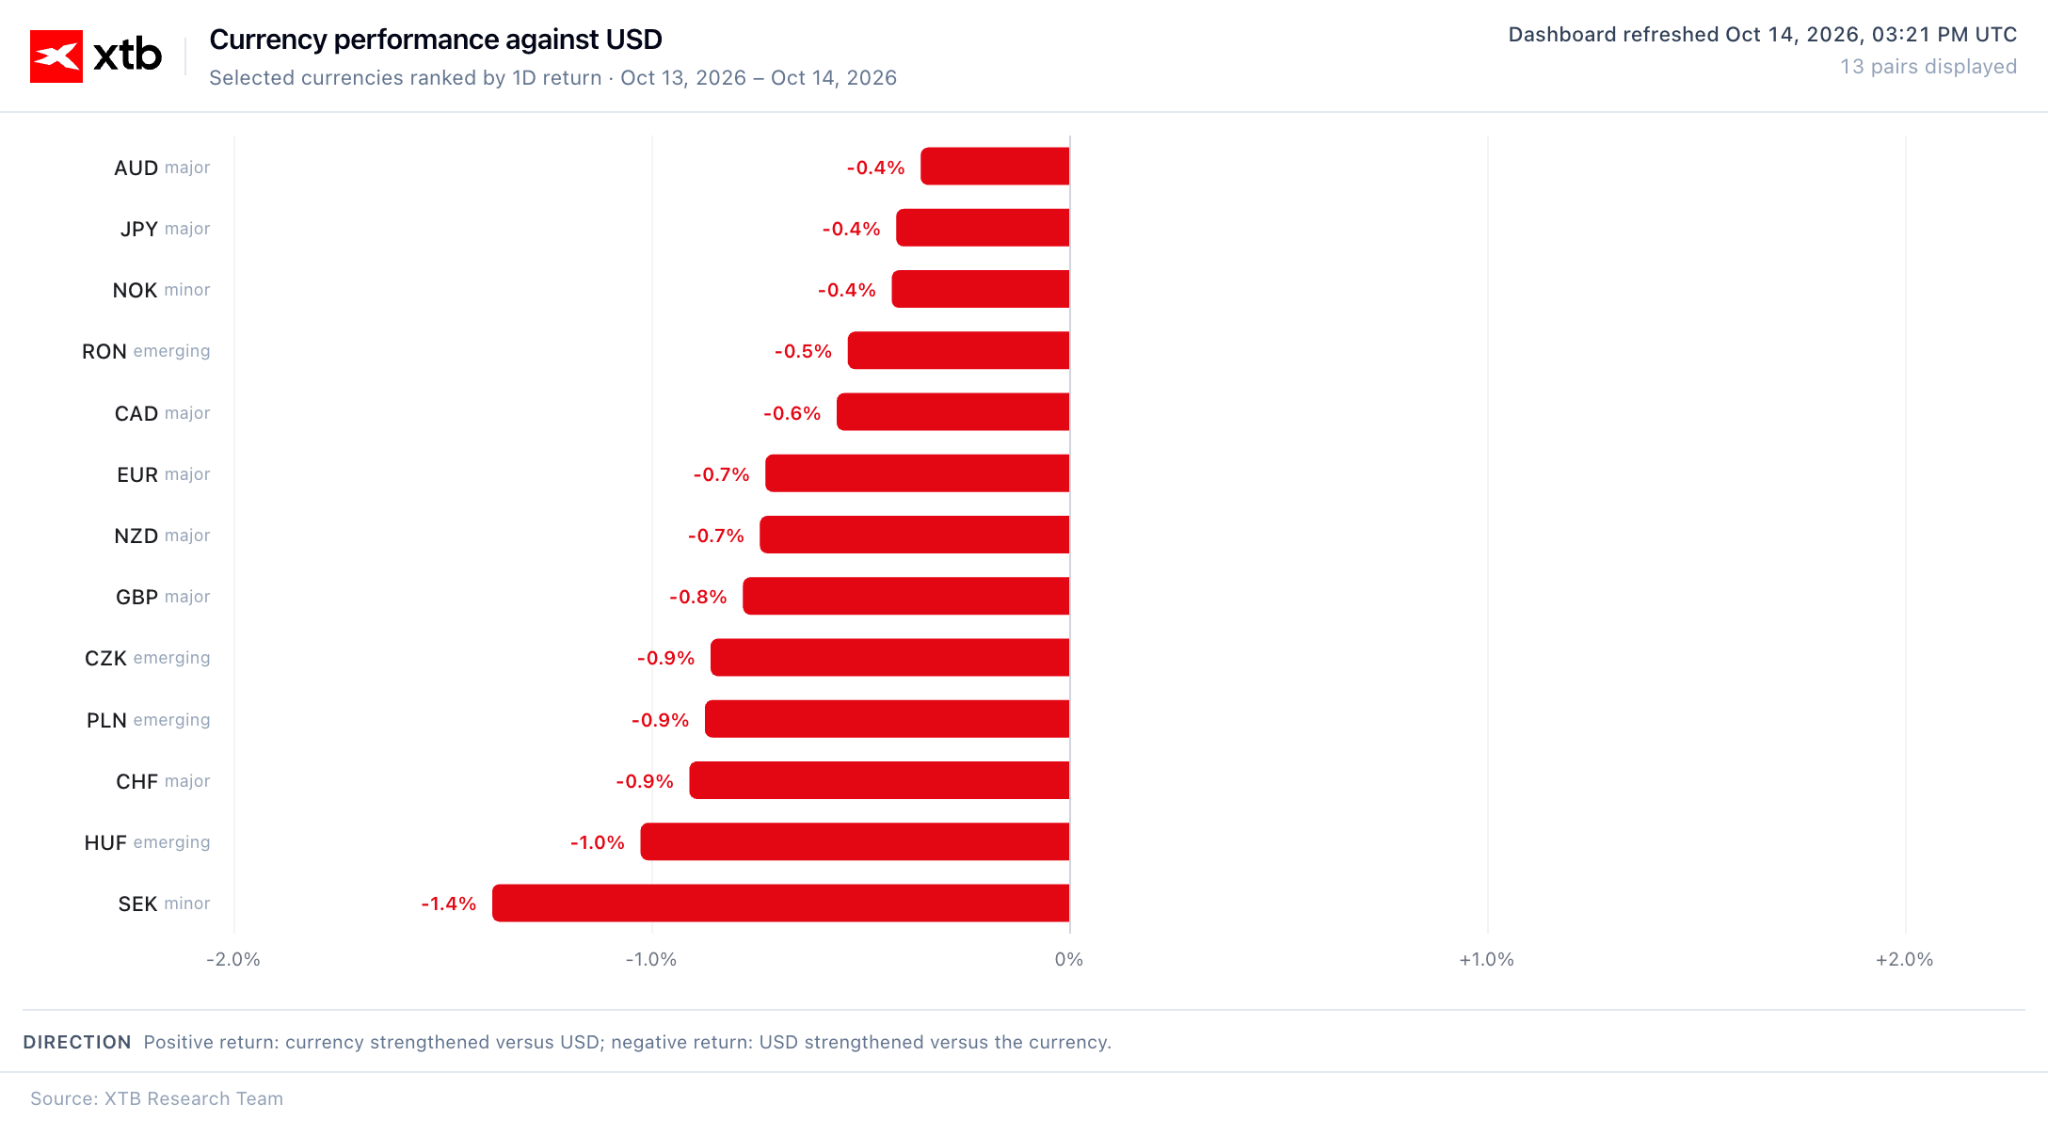
This proved unhelpful for stock market indices. The S&P 500 fell (-0.8%) alongside the Nasdaq 100 (-1.1%). The move measured in euros was notably smaller due to the simultaneous weakening of the currency against the dollar. The EURUSD pair approached the 1.11 level, weakening by nearly 0.8% relative to the start of the session.
Figure 3: G10 and CEE Currency Performance vs. USD (14.10.2026)
 Source: XTB Research, 14.10.2026
A few words on the data
Although markets are focused on the stronger-than-expected increase in both the headline and core measures, Fed policymakers are paying attention elsewhere.
September brought a return of the 3-month core momentum above the Fed's inflation target.
Figure 4: US Core CPI Inflation Momentum (14.10.2026)
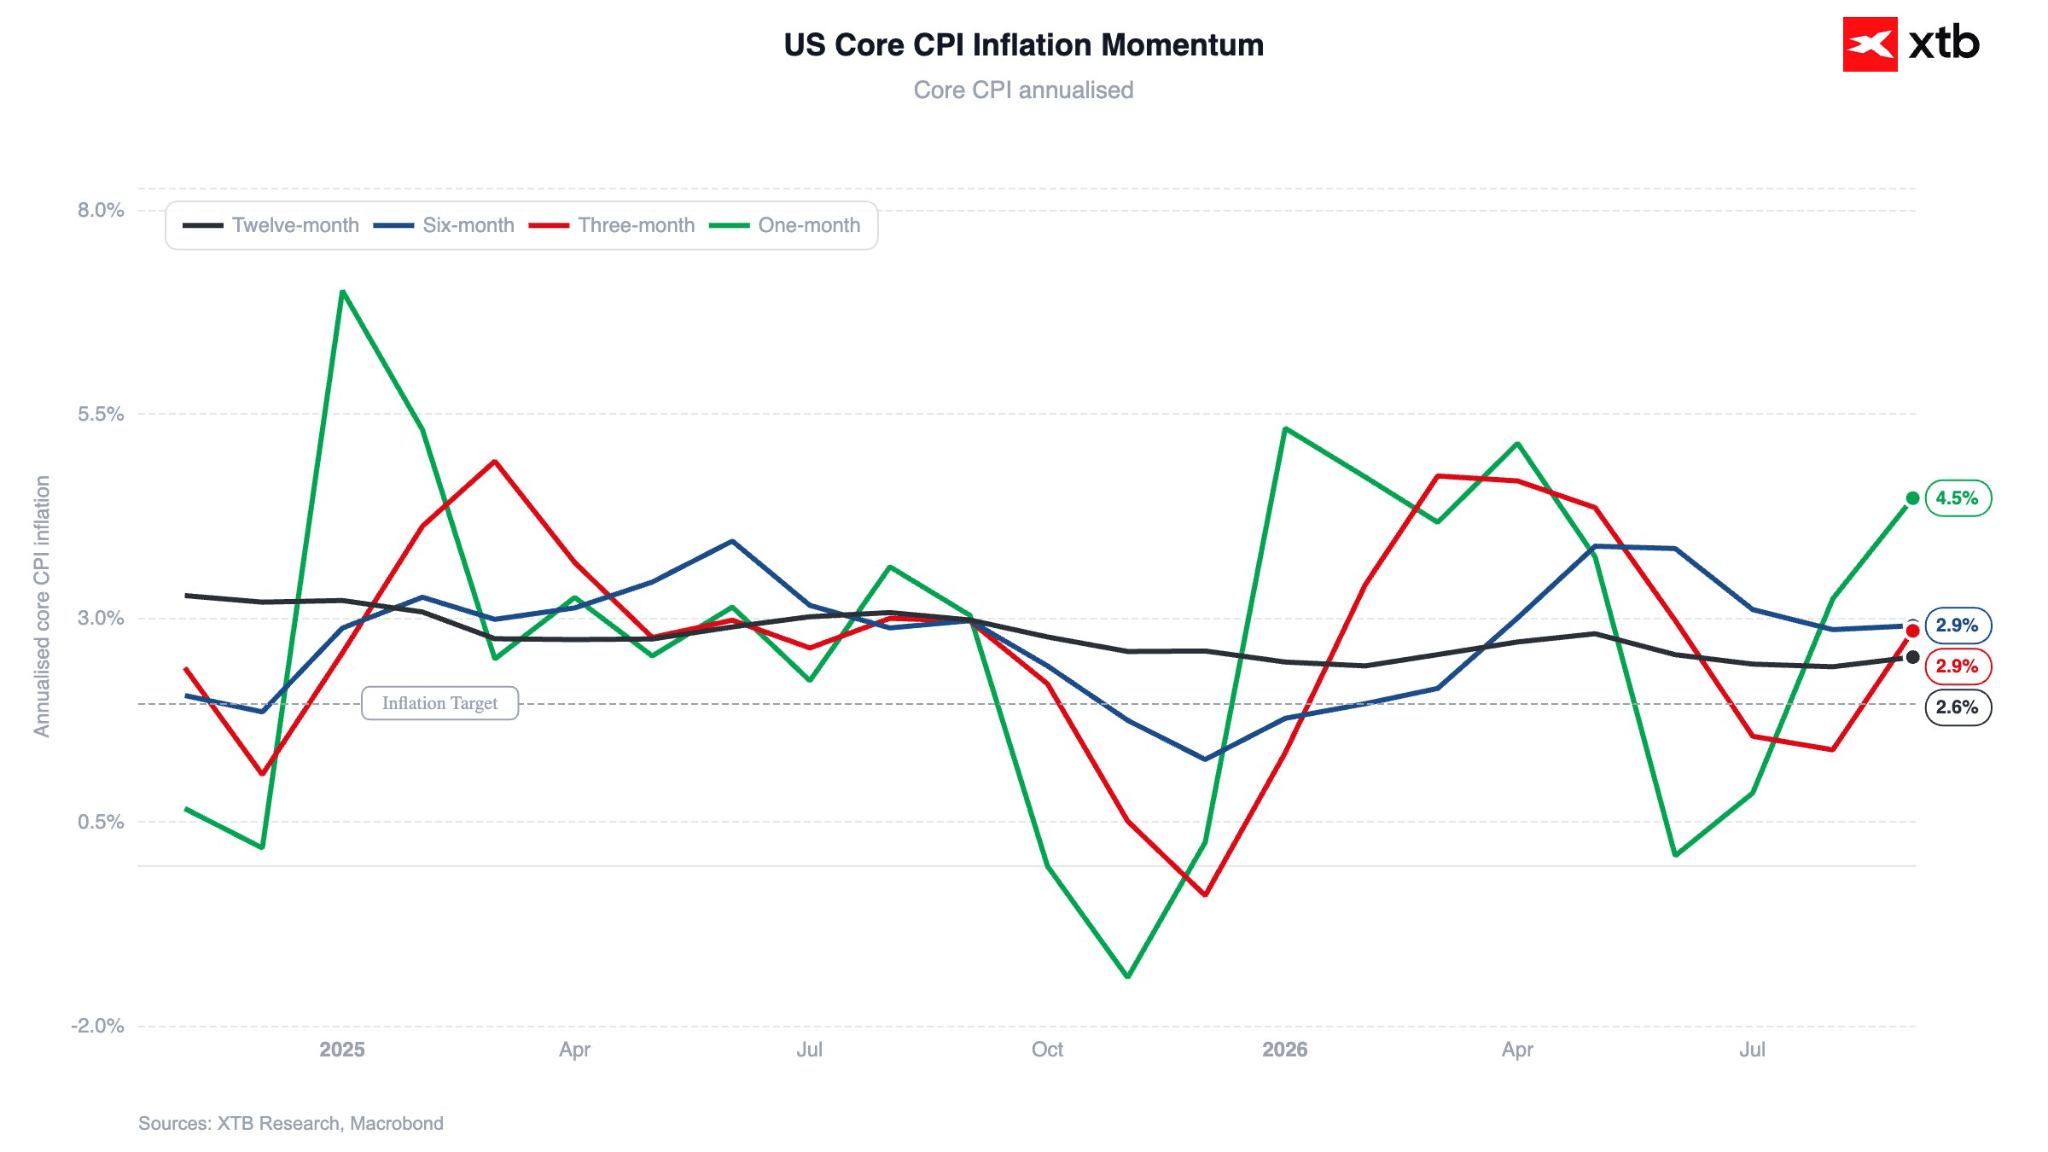 Source: XTB Research, 14.10.2026
Furthermore, prices for over 52% of products rose at a pace exceeding 3%, with 35% rising above 4%. Such broad-based price pressure has not been observed since May.
It is worth noting that both of these metrics were cited by Kevin Warsh as key considerations in monetary policy decision-making.
Will October Bring a Rate Hike?
One might remain somewhat skeptical regarding the prospect of continued monetary tightening in October, primarily because the meeting will take place just ahead of the midterm elections. These will set the political trajectory for the US over the next two years.
In the event that Republicans lose both houses, Donald Trump will retain significant leeway in foreign policy; however, he will face constraints on funding his initiatives, as the power of the purse lies with Congress.
Consumption data will be valuable to the Fed in the coming days. The next key release is due tomorrow, namely the September retail sales report.
Any signs of weakness in the US consumer will dampen the appetite for rate hikes. At present, however, such signals are visible only in soft survey indicators, and not across all of them.
Figure 5: US Retail Sales and Consumer Sentiment (2021 - 2026)
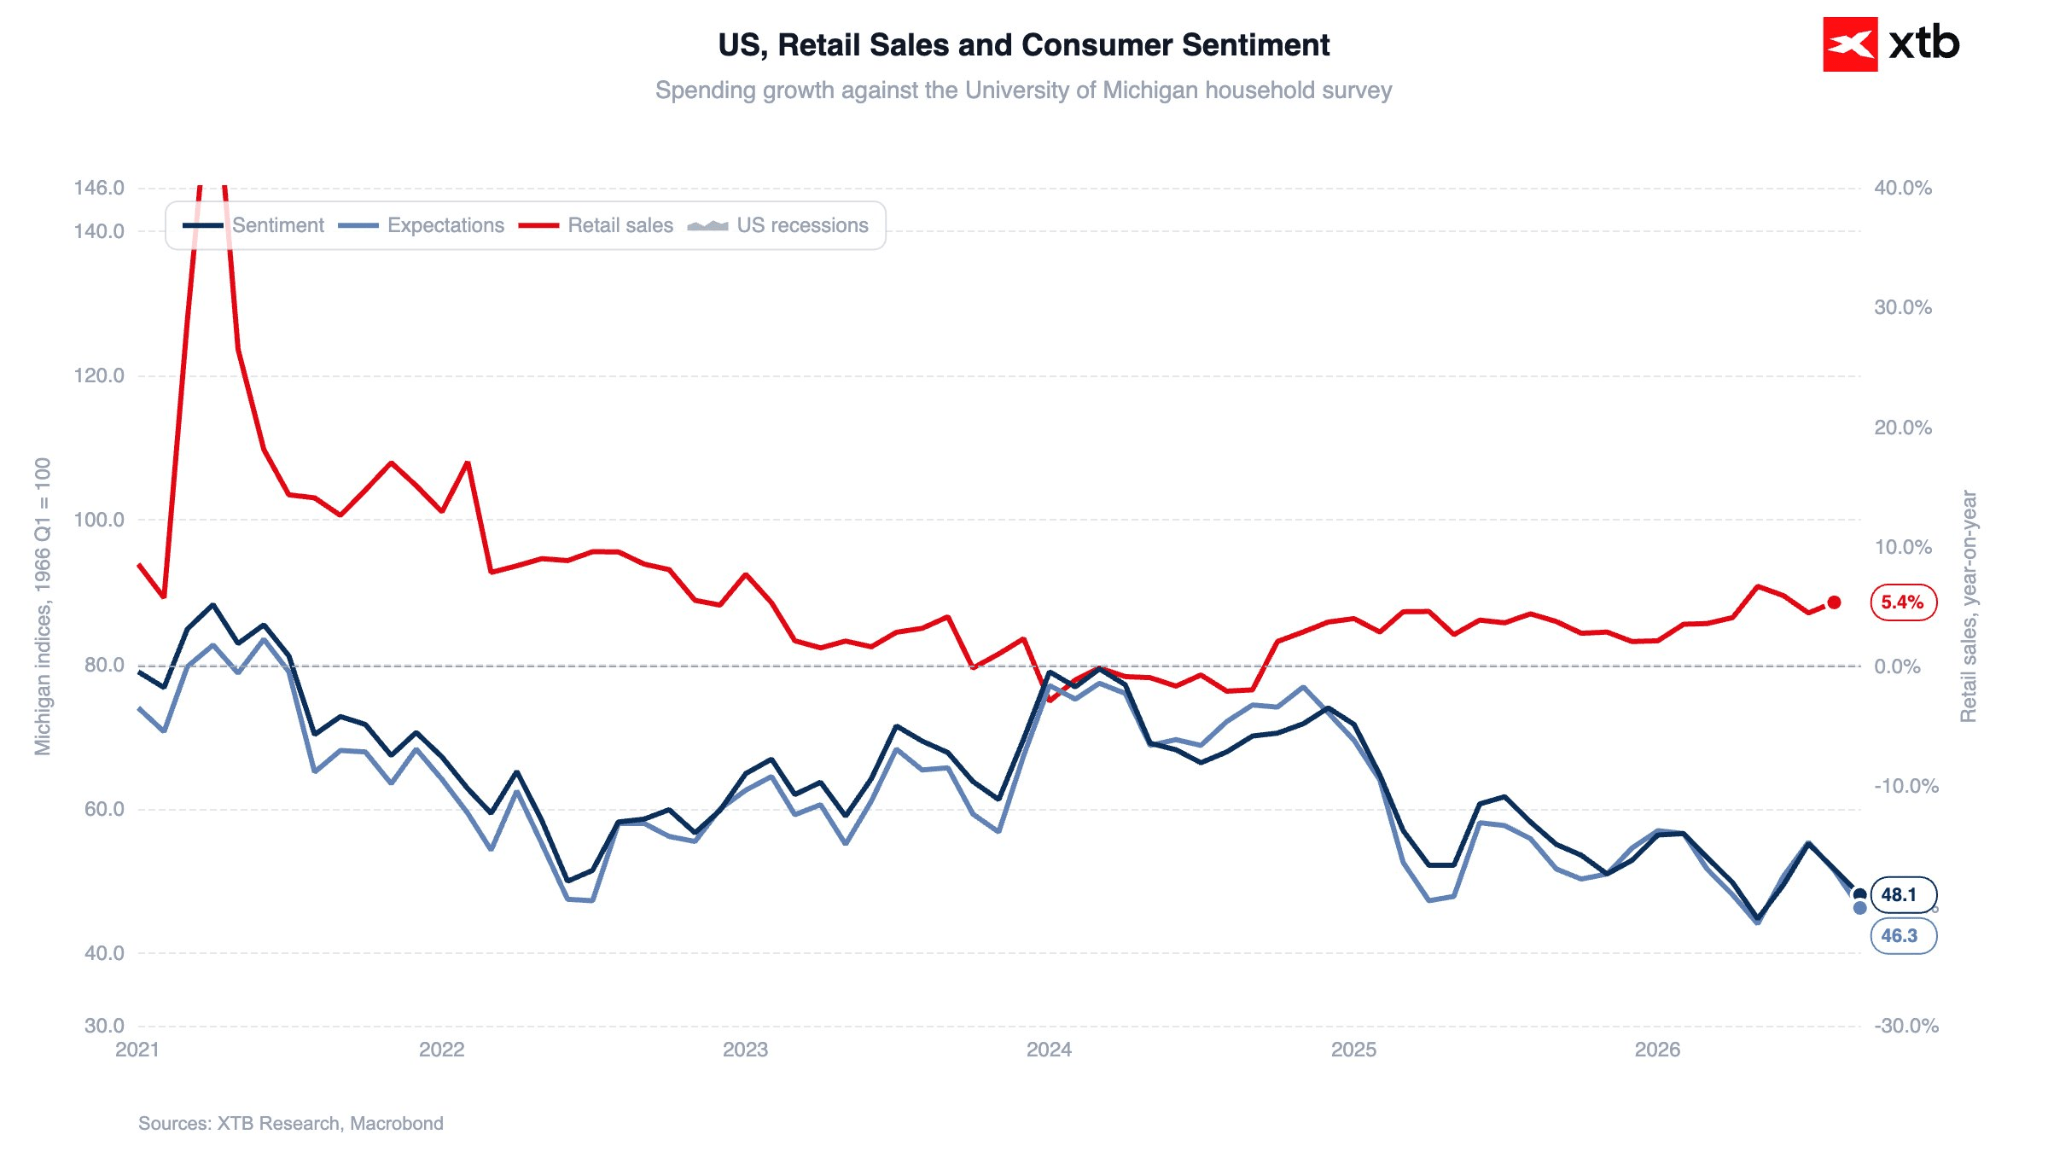 Source: XTB Research, 14.10.2026
—
Michał Jóźwiak, Financial Markets Analyst at XTB



Economic Calendar - Start of Wall Street Earnings Season, Hawkish RBA, and Middle East Tensions (13.10.2026)



Morning Wrap: Tech Crash in Asia and Hawkish Central Banks in the Shadow of an Oil Shock (13.10.2026)



📊Market Wrap: Europe Rebouns Despite Higher Oil and Dollar (12.10.2026)


Chart of the Day: Will the RBI's bold regulatory package rescue the rupee? (12.10.2026)
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.