


Today's session is marked by numerous speeches from central bank representatives (RBA, ECB, Fed, and Bundesbank), which may trigger elevated volatility in foreign exchange markets.
In the spotlight were comments from RBA Governor Bullock, who highlighted inflation risks stemming from the Middle East and demand pressure driven in part by the artificial intelligence sector. In addition, markets are tracking geopolitical and energy news.
In Japan, markets remain closed due to a national holiday.
In the fundamental data calendar, key releases will include UK public sector net borrowing and consumer confidence indicators for the Eurozone.
Key Releases from the Asian Session
- Speech by RBA Governor Bullock: The head of the Australian central bank noted that inflation risks stem from the situation in the Middle East and strong domestic demand. She emphasized that policy must address second-round effects, and unemployment at 4.5%–5.0% should help reduce price pressures.
- Speech by RBNZ Governor Breman: The Reserve Bank of New Zealand indicates that the economy continues an uneven recovery; however, persistently higher crude oil prices could push short-term inflation above previous forecasts.
Macroeconomic Calendar (Note: All times are in CET - Central European Time)
- 05:10 Australia - Speech by RBA Governor Bullock.
- 08:00 UK - Public sector net borrowing. Consensus: 15.2 bn. Previous: 1.8 bn.
- 10:30 Eurozone - Speech by Bundesbank President Nagel.
- 12:00 UK - CBI Industrial Trends Orders. Consensus: -33. Previous: -25.
- 13:00 Eurozone - Speech by ECB President Lagarde.
- 14:15 US - ADP Weekly Employment Change. Previous: 16.3k.
- 16:00 Eurozone - Consumer Confidence. Consensus: -16. Previous: -16.
- 16:00 US - Richmond Fed Manufacturing Index. Consensus: 2. Previous: 4.
- 16:05 US - Speech by FOMC Member Williams.
- 16:20 US - Speech by FOMC Member Jefferson.
- 19:00 US - Speech by FOMC Member Barkin.
- 21:30 Eurozone - Speech by Bundesbank President Nagel.
- 22:30 US - API Weekly Statistical Bulletin.
- All day Japan - Market Holiday (National Holiday).
Markets to Watch
- AUDUSD: Remarks by RBA Governor Bullock regarding rising inflation risks and strong domestic demand put pressure on the Australian dollar valuation amid global interest rate differentials.
- EURUSD: Numerous speeches from ECB representatives (including President Lagarde and Bundesbank Chief Nagel) as well as fresh comments on cost pressures in Europe may determine the short-term direction of the common currency.
- GBPUSD: The release of domestic data on UK public sector net borrowing will directly impact government bond (Gilt) yields and the valuation of the pound.
AUDUSD: Correction in an Ongoing Uptrend
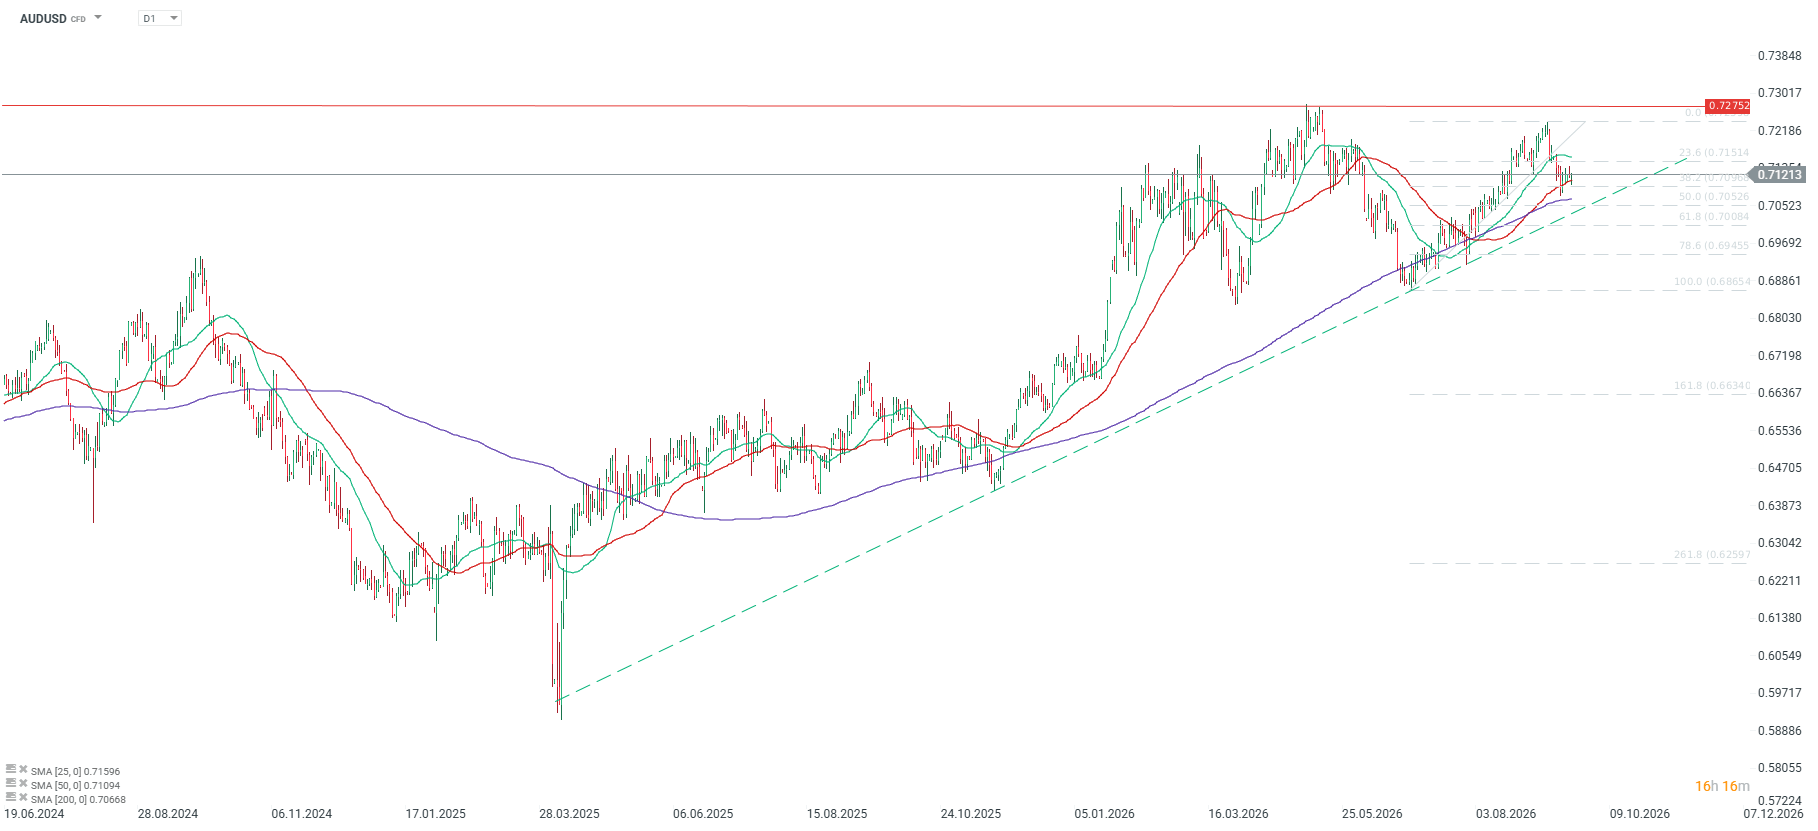
The Australian currency pair remains in a clear uptrend, which has continued uninterrupted since the March 2025 low near 0.5890 and is supported by an ascending trendline. Quotes reached strong resistance near 0.72752, where momentum faded before a breakout, and a clear correction has developed since then without altering the broader impulse. Currently, trading at 0.71213, the pair is testing a key support zone.
The moving average layout still favors bulls as a bullish alignment remains intact, with the 50 SMA at 0.71094 positioned above the 200 SMA at 0.70668. However, price has pulled back below the 25 SMA at 0.71596, reflecting short-term downside pressure. The first key support lies near 0.70969—the 38.2% Fibonacci retracement level—just alongside the 50 SMA. Defending this zone would preserve the scenario of a simple technical breather before the next upward leg.
Holding above the 0.70970 to 0.71090 band keeps the door open for another attempt to test the 25 SMA at 0.71596, followed by the 0.72752 resistance barrier, a break of which would resume the rally. The bearish scenario activates only after a sustained move below the 50% retracement at 0.70526 and the 200 SMA at 0.70668, turning attention toward support at the 61.8% level (0.70084) and the ascending trendline. As long as prices hold above these levels, buyers retain the technical advantage.


Morning Briefing: Global Markets Riding AI Wave, Rising Geopolitical Tensions, and Hawkish Central Banks (22.09.2026)

Chart of the Day: European Gas (NATGAS.EU) below 80 EUR, but Goldman Sachs warns of 105 EUR/MWh.

Economic Calendar: Day of central banker speeches led by Lagarde (21.09.2026)
Morning briefing: Trump-Xi in the shadow of geopolitical tensions (21.09.2026)
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.