


Although Monday brought a minor tremor to the market on the back of rising oil prices and an appeal from AI leaders, macroeconomic developments were relatively subdued. Attention focused primarily on inflation data from Canada. Tuesday opened with readings from China and the United Kingdom, which attracted significantly greater market focus.
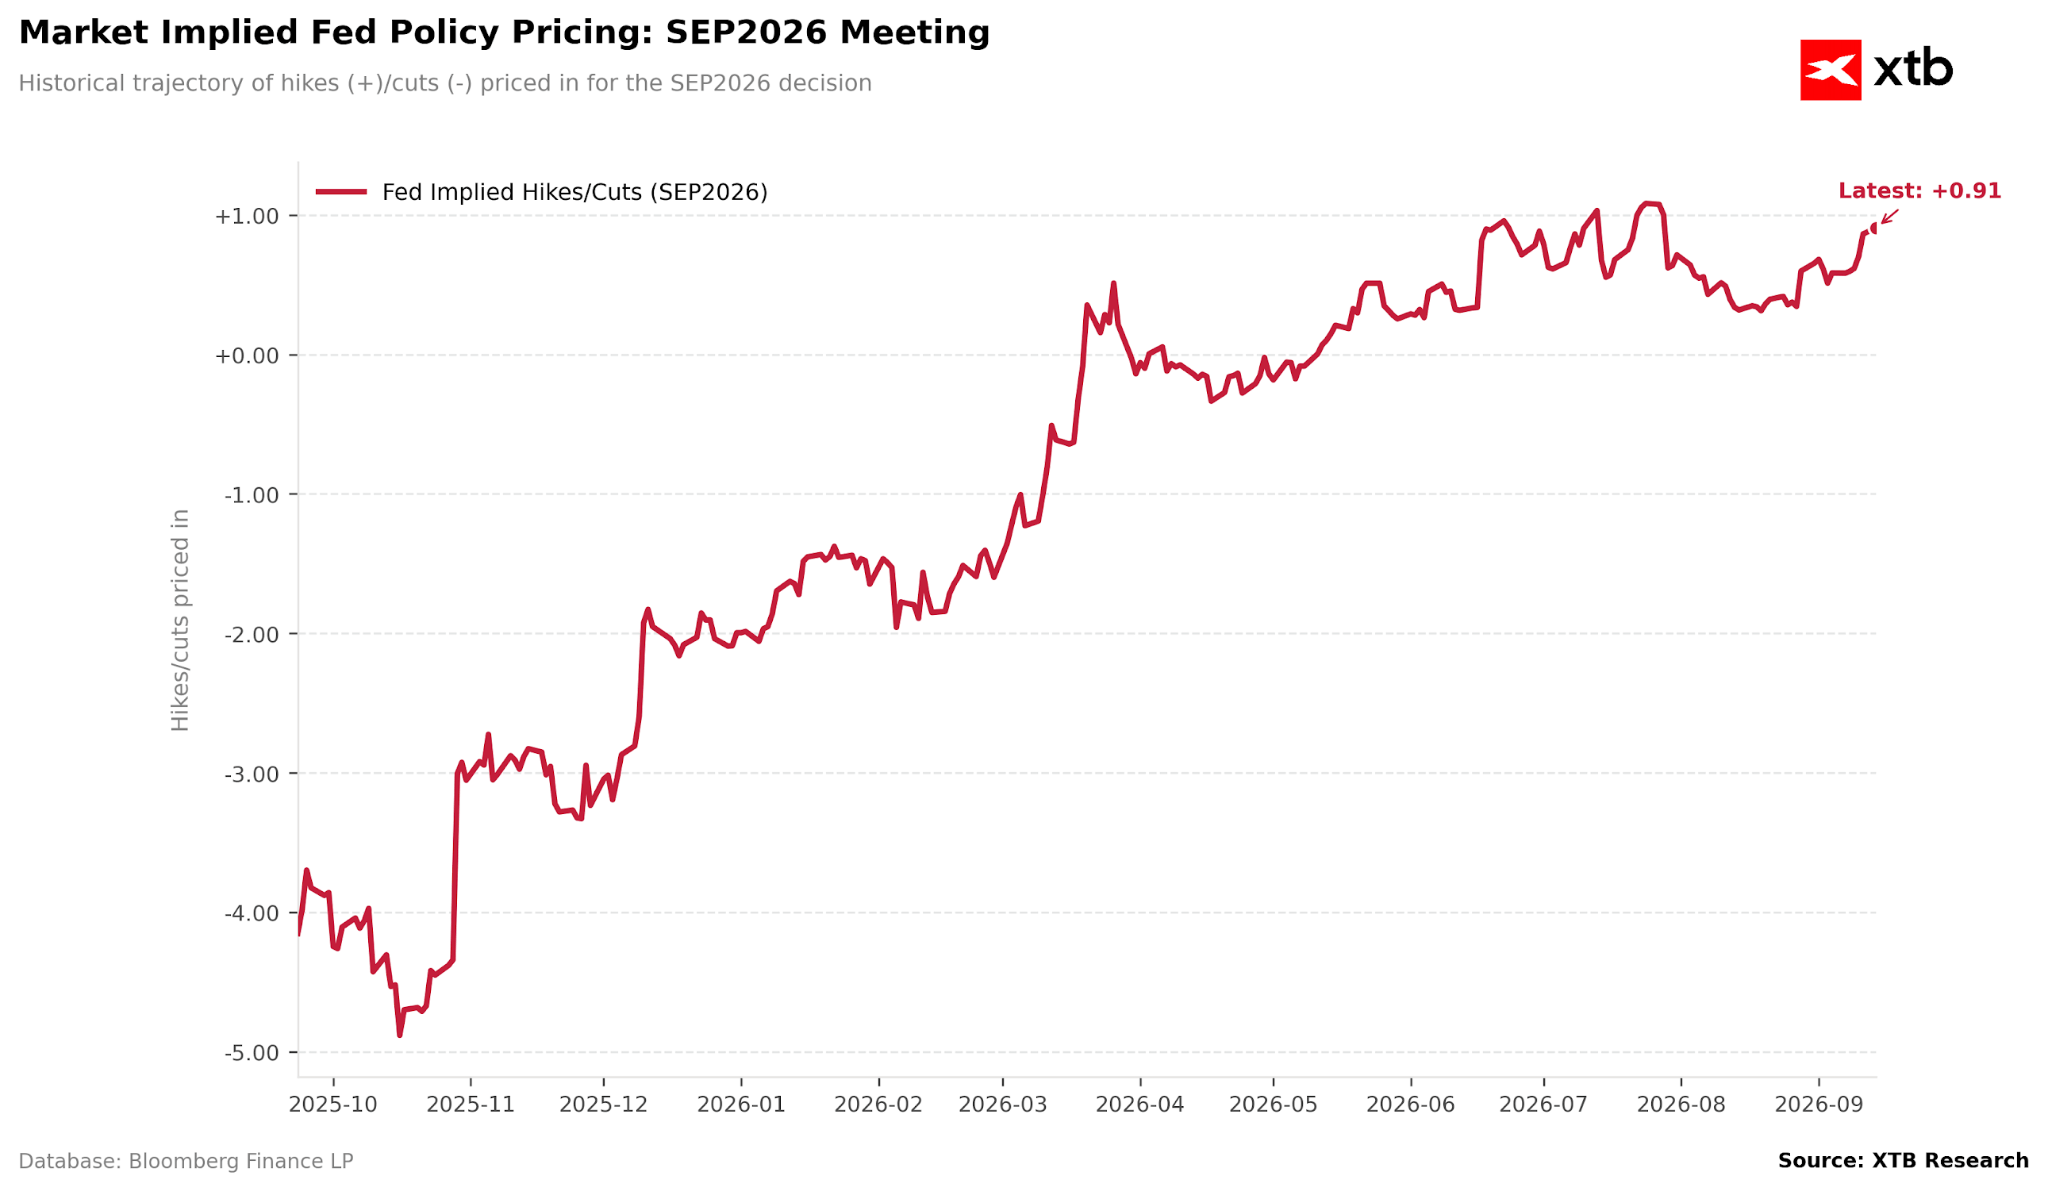
Investors, however, are above all awaiting Wednesday’s decision from the Federal Reserve. Indications suggest that on Wednesday at 7:00 PM it will announce its first rate hike since July 2023.
For a long time, there was doubt as to whether the committee would indeed opt for such a step, particularly given the less-than-credible messaging from the new Chair, Kevin Warsh. Currently, however, markets are pricing it at over 90%.
Figure 1: Change in Market-Implied Probability of a September Fed Rate Hike (2025 - 2026)
 Source: XTB Research, 15.09.2026
Markets could interpret a pause as the Fed ceding to pressure from Donald Trump, who has been vocal in expressing his preference for lower interest rates. This would most likely trigger a further increase in long-term bond yields and a resurgence of the debasement trade, a strategy based on shifting away from traditional fiat currencies towards hard assets with limited supply, including precious metals and Bitcoin. This would certainly not be positive news for the US dollar following a relatively successful period.
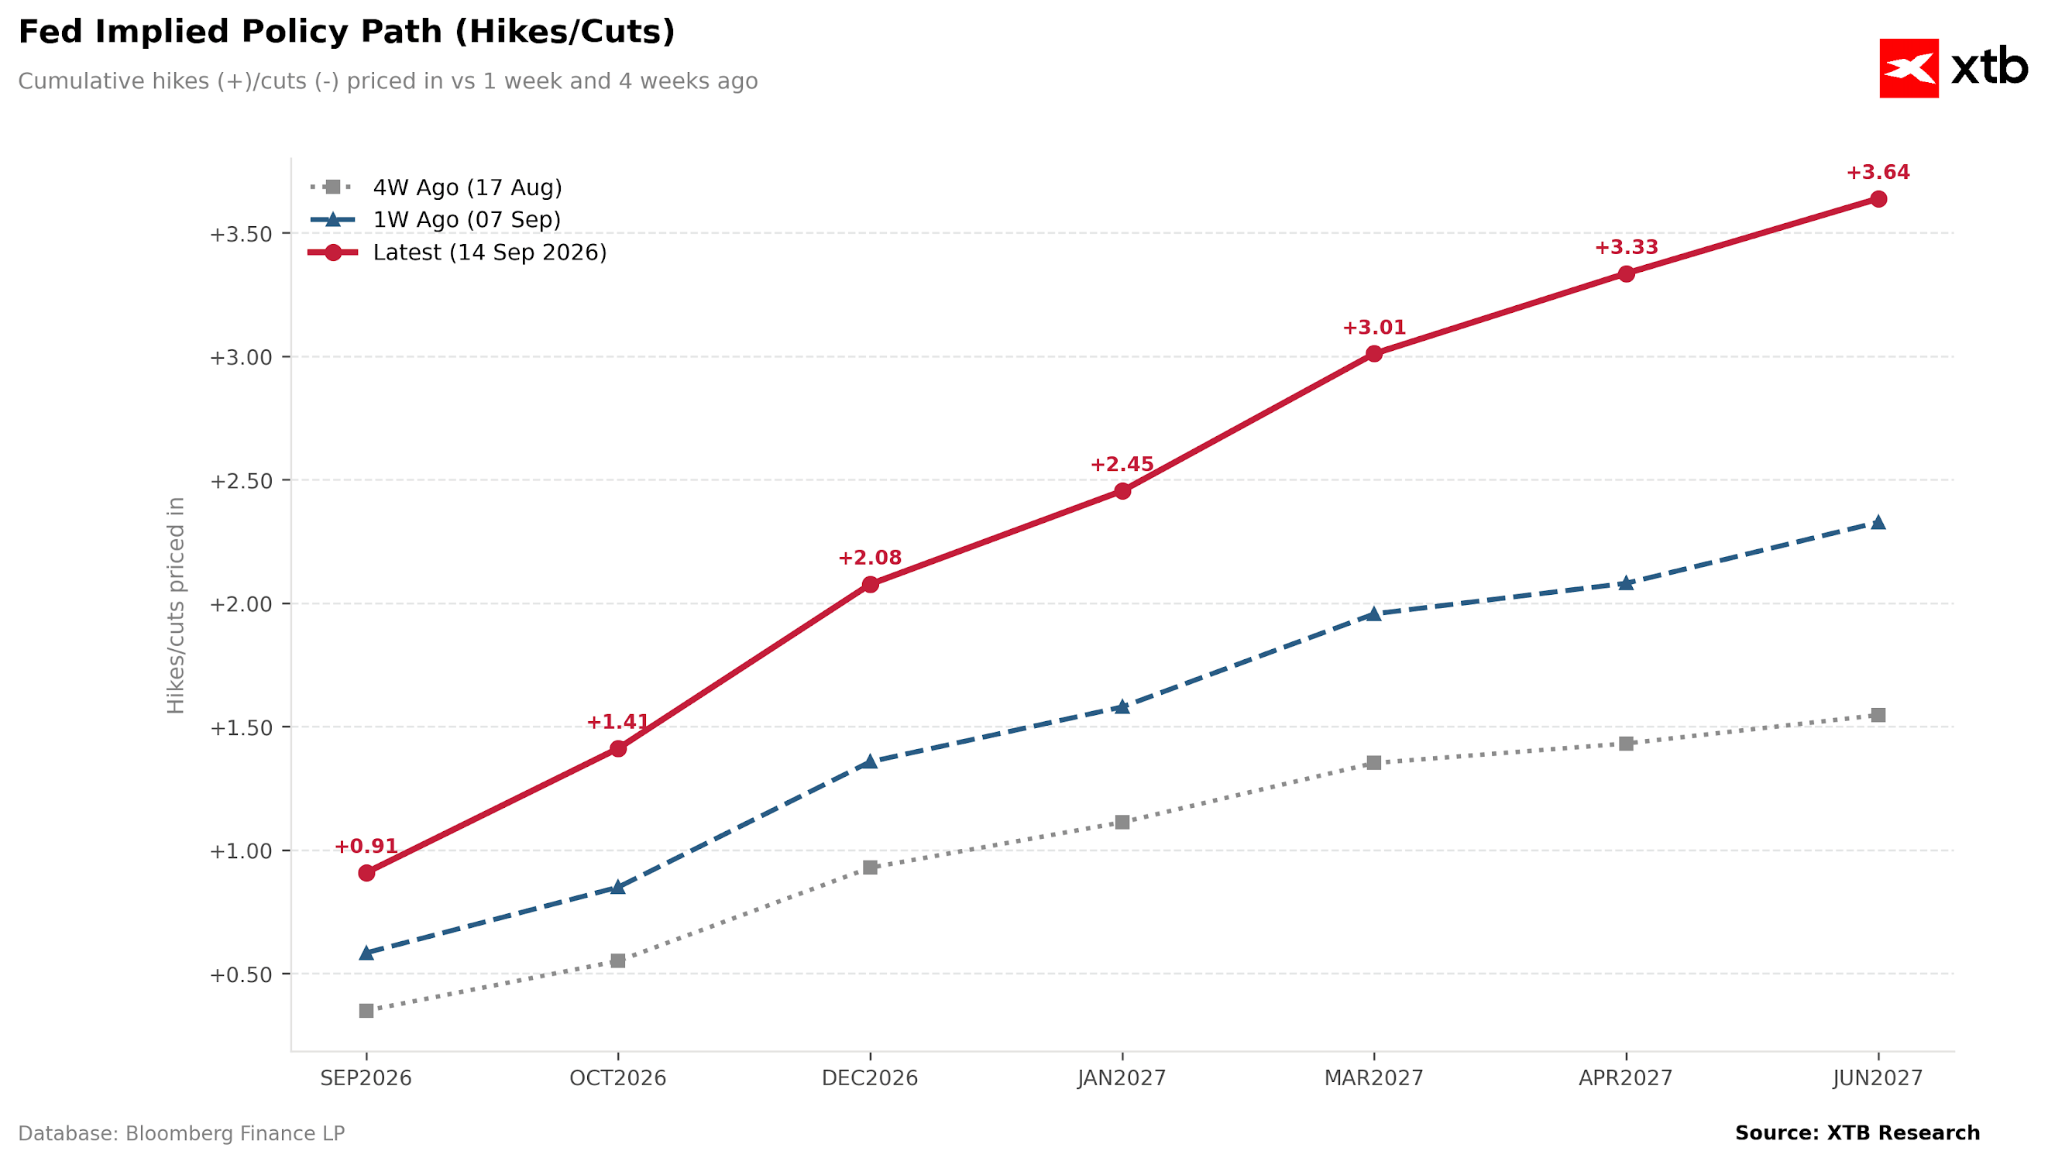
A rate increase does not, however, guarantee an appreciation of the US currency. Given that such a move is nearly fully priced in, a relatively hawkish and, crucially, credible narrative is also required. Should Warsh fail to convince markets once again, expectations for subsequent hikes could diminish, putting downward pressure on the greenback.
Figure 2: Market-Implied Fed Policy Rate Path (2026 - 2027)
 Source: XTB Research, 15.09.2026
What supports a rate hike?
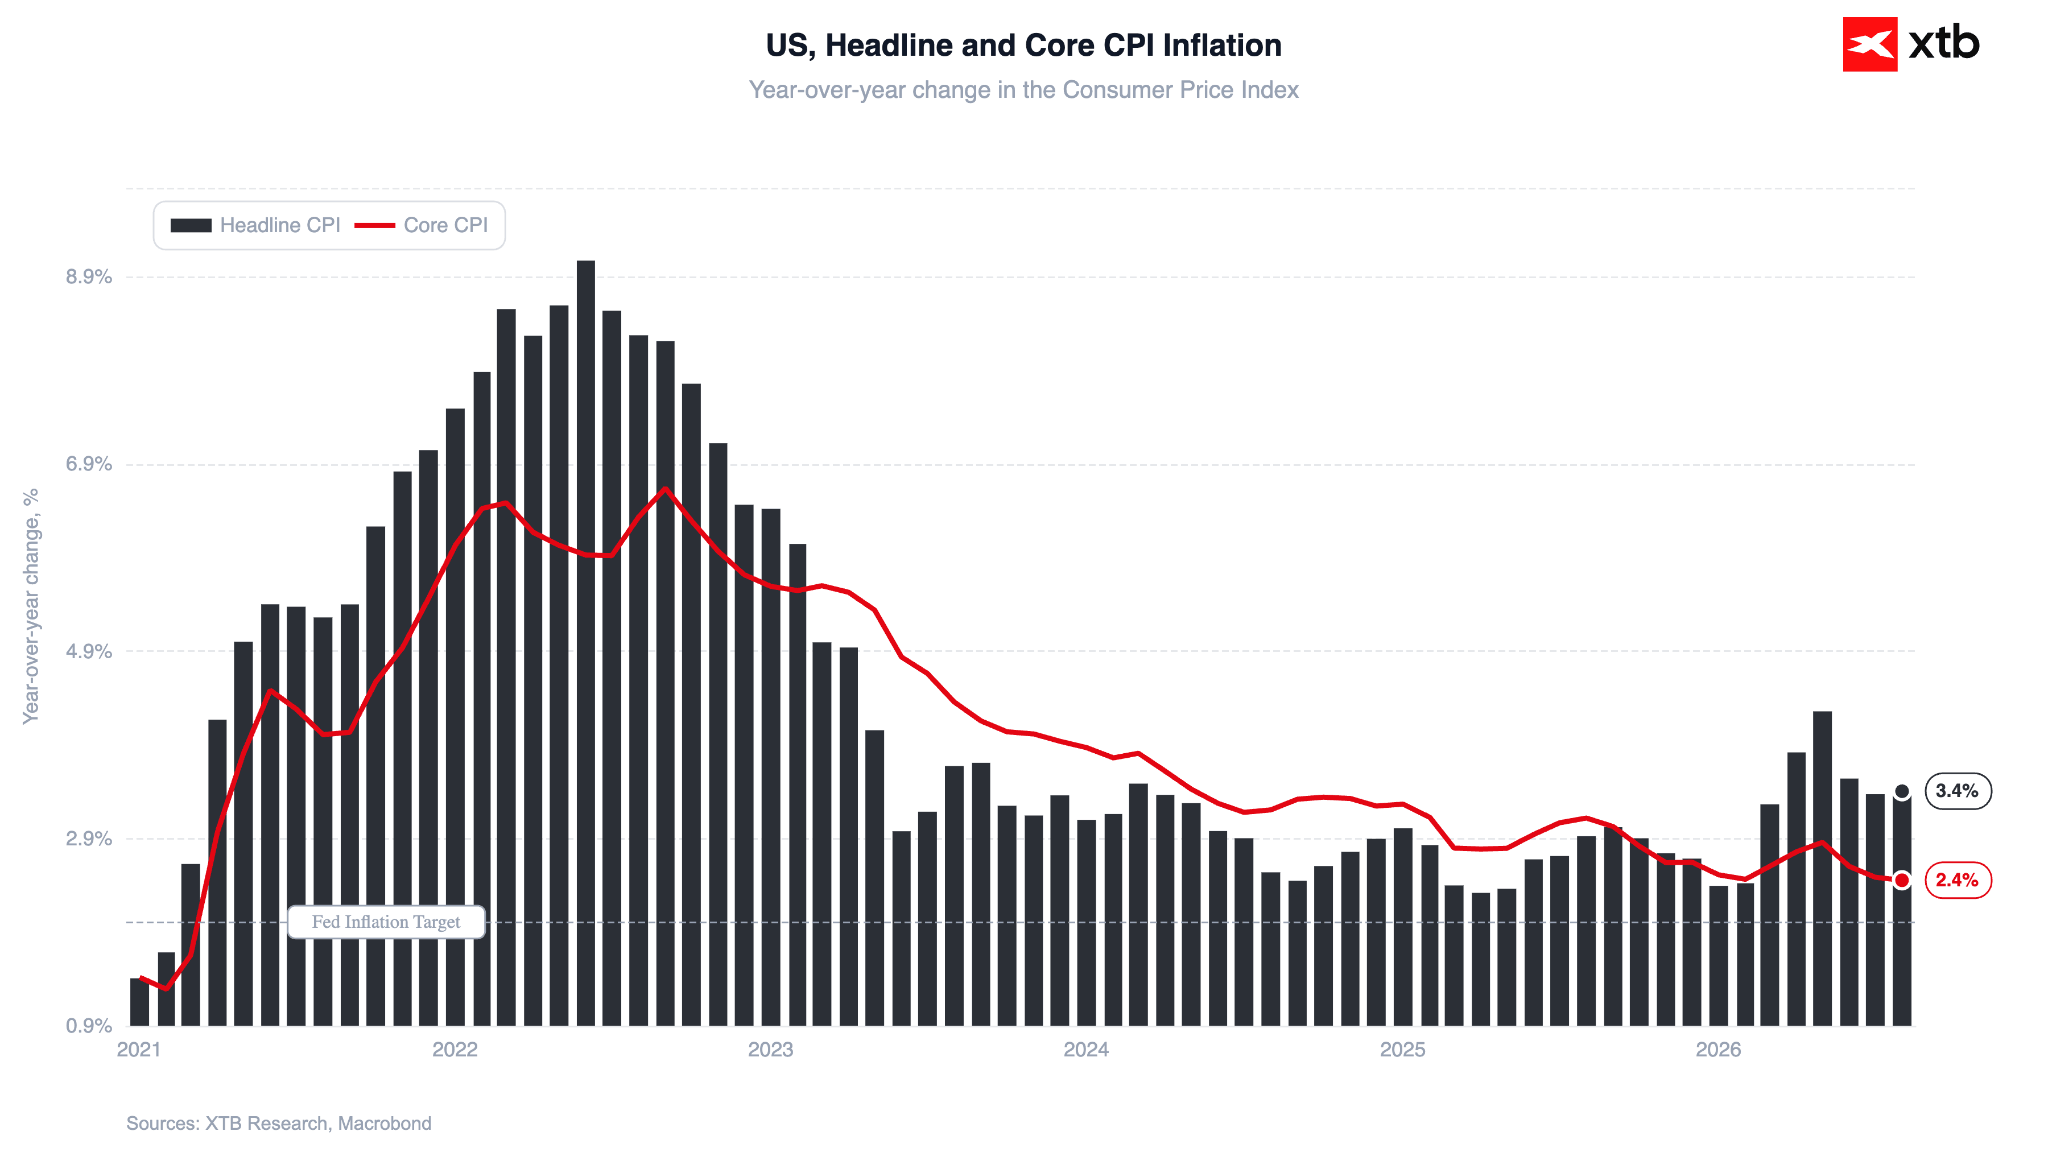
The August inflation figures themselves held no surprises on an annual basis, pointing to underlying inflationary pressure that remains modest (core CPI at 2.4% YoY, excluding volatile energy and food prices). On a month-on-month basis, however, inflation accelerated slightly to 0.3%, which markets perceived as a cause for concern. FOMC policymakers may nevertheless be most concerned by services sector inflation (3.1%), which could be driven by increasingly dynamic wage growth. The Atlanta Fed Wage Growth Tracker rose in August to 4.1%, its highest level since October 2025 (though, to present the full picture, this still represents less than 1% in real terms).
Figure 3: CPI Inflation in the United States (2026 - 2027)
 Source: XTB Research, 15.09.2026
Christopher Waller highlighted a week earlier that the August reading could prove decisive for the committee's final decision, tipping the balance one way or the other. While the data provided no definitive answer, markets interpreted the results as a precursor to a hawkish pivot.
🌏 Key macroeconomic publications
Monday
Canada
- CPI inflation remained at 3.0% YoY in August, matching consensus expectations and unchanged from July. The core rate was markedly lower at 2.4% YoY. Fuel prices surged by 22.8% on an annual basis.
- It is worth recalling that earlier in the month the Bank of Canada kept interest rates on hold for the seventh consecutive meeting.
Tuesday
United Kingdom
- The ILO unemployment rate held steady at 4.9%, below the consensus forecast of 5.0%.
- Wage growth (including bonuses) rose by 3.9% (in line with expectations), following an upward revision of the previous reading to 4.2% from 4.1%. Regular wage growth (excluding bonuses) remained at 3.5%.
- Claimant count entries rose by 27.8k, substantially exceeding expected levels (+8.3k).
- The pound's reaction was muted, with GBP/EUR falling by less than 0.1%.
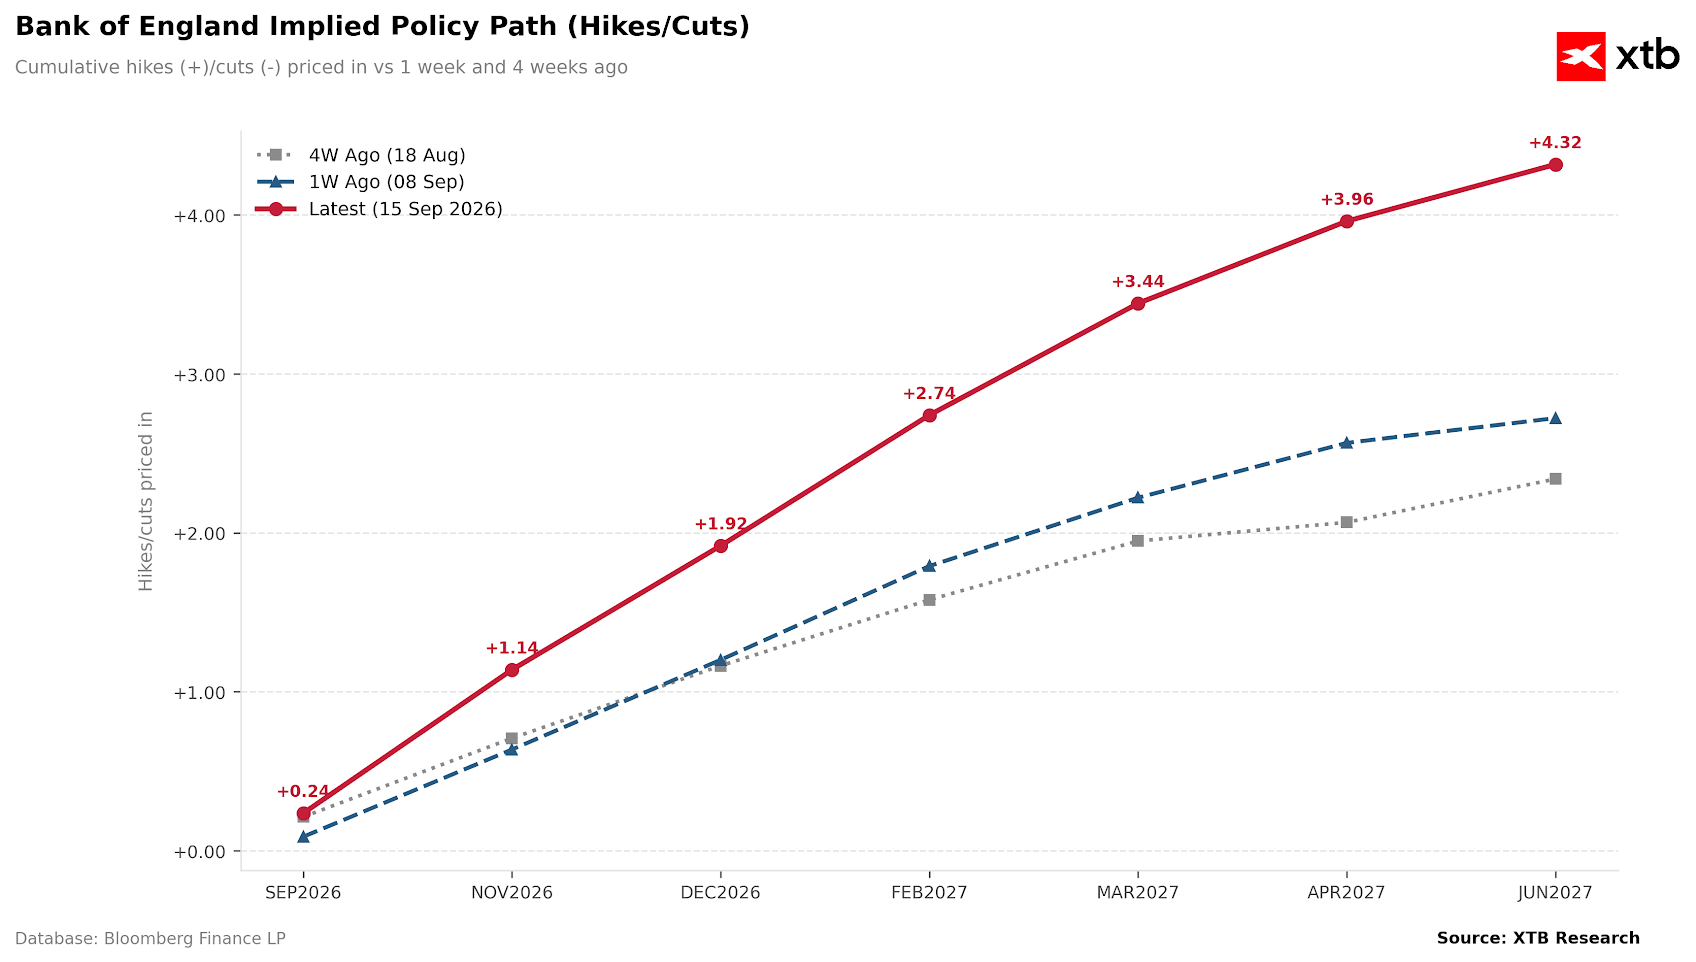
- Markets are currently pricing in approximately a one-in-four chance of a rate hike by the BoE, anticipating upward moves in November and December.
Figure 4: Market-Implied BoE Policy Rate Path (2026 - 2027)
 Source: XTB Research, 15.09.2026
China
- Industrial production accelerated in August to 5.2% YoY (up from 4.5% in July), driven in part by exports linked to the global expansion of AI infrastructure.
- Retail sales slowed to 0.4% YoY (below expectations of 0.8%), fixed-asset investment dropped by 7.2% year-to-date, and urban unemployment unexpectedly rose to 5.3%.
- The main drag on consumption remains the collapse in auto sales (-18.5% YoY) following the phase-out of subsidies.
- The PBOC set a stronger yuan fixing for a fifth consecutive day today (at 6.7670/USD), capping volatility ahead of the Xi-Trump summit scheduled for 24.09.2026. This marks the longest such streak since December 2025.
📆 Macroeconomic calendar
Tuesday
- Poland: August CPI inflation (final revision)
- Time: 8:30 AM
- Preliminary reading: 3.4%
- Germany: September ZEW Index
- Time: 10:00 AM
- Consensus: 39.8
- Previous reading: 34.2
Wednesday
- United Kingdom: August CPI inflation
- Time: 7:00 AM
- Consensus: 3.1%
- Previous reading: 2.9%
🗂️ Corporate Earnings
No major earnings releases scheduled.
3 Markets to Watch
- OIL: Brent crude breached 107 USD per barrel following Saudi Arabia's closure of the East-West pipeline, which served as a bypass for disruptions in the Strait of Hormuz. The US Energy Secretary anticipates a swift return to operation for the infrastructure, though AP reports a potential outage lasting several weeks.
- TNOTE: The 10-year Treasury yield surpassed 5%, reaching its highest level since 2007. The increase is driven by rising energy prices and growing debt in both the public and private sectors.
- GBPUSD: Sterling remains under pressure despite the unexpectedly low unemployment rate, with the market focusing on rising claimant count entries and tomorrow's CPI release, which, alongside Thursday's BoE decision, will determine the pair's trajectory.
—
Michał Jóźwiak, Financial Markets Analyst at XT



Chart of the Day: What’s next for the US stock market? (16.09.2026)


Economic Calendar: Time for an interest rate hike? (16.09.2026)

Morning Wrap: Market seeks balance ahead of Fed decision (16.09.2026)


Will Trump dissuade Fed from a rate hike? [FOMC Preview]
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.