

- US earnings season starts with reports from major banks like JPMorgan Chase and Goldman Sachs.
- Middle East tensions and flight suspensions raise geopolitical risk premiums in the crude oil market.
- Japan records a producer price index deceleration to 6.8 percent year-on-year in September.
- US500 reaches high levels without confirmation from financial sector leaders, creating a divergence warning.
- MACD indicators show a shrinking histogram, signaling negative momentum divergence similar to past pullbacks.
Tuesday's session will mainly be dominated by the official start of the quarterly earnings publication season in the US. Investors will learn about reports from the largest American financial institutions, including JPMorgan Chase, Goldman Sachs, Citigroup, and Wells Fargo, which will allow assessing the condition of the banking sector, credit portfolio quality, and consumer resilience in the face of persistent interest rates.
At the same time, the geopolitical situation in the Middle East remains an important market factor. Reports of airline flight suspensions by Etihad and Qatar Airways fuel concerns about an escalation of the conflict, translating into an elevated risk premium in the crude oil market. Overnight, hawkish RBA meeting minutes arrived from Australia, emphasizing the need for prolonged suppression of domestic demand to tame inflation, although local business sentiment suffered a sharp decline. Meanwhile, data from Japan brought a distinct deceleration in producer price dynamics (PPI to 6.8% YoY), easing pressure on rapid rate hikes by the Bank of Japan. During the day, volatility may be triggered by speeches from Fed central bankers (Waller, Barkin, Collins) and the final reading of German CPI.
Key Releases from the Asian Session
- Japan - Producer Price Index (PPI) YoY for September: 6.8% (consensus: 7.6%; previous: 7.6%). A clear slowdown in producer-side cost pressure reduces inflationary pressure in the Japanese economy.
- Japan - Bank Lending YoY for September: 5.3% (consensus: 5.5%; previous: 5.3%). Bank lending growth maintained its pace from the previous month, coming in slightly below market expectations.
- Australia - NAB Business Confidence Index for September: -13 pts (previous: -9 pts). The deepening negative sentiment among businesses reflects the growing burden of restrictive monetary policy and cost pressures.
- United Kingdom - BRC Retail Sales Monitor YoY for September: 1.0% (consensus: 0.8%; previous: 0.5%). A higher-than-expected reading indicates a slight improvement in UK consumer willingness to spend.
Macroeconomic Calendar
- 02:30 Australia - RBA Monetary Policy Meeting Minutes
- 05:00 United Kingdom - Speech by BoE MPC Member Megan Greene
- 08:00 Eurozone - Final German CPI MoM. Consensus: 0.6%. Previous reading: 0.6%.
- 09:45 USA - Speech by Fed Board Governor Christopher Waller
- 12:00 USA - NFIB Small Business Optimism Index. Consensus: 98.1. Previous reading: 98.7.
- 14:15 USA - ADP Weekly Employment Change. Previous reading: 23.8k.
- 16:00 USA - Existing Home Sales. Consensus: 3.95M. Previous reading: 3.98M.
- 16:30 Australia - Conference Board Leading Economic Index MoM. Previous reading: 0.5%.
- 19:00 USA - Speech by Richmond Fed President Thomas Barkin
- 22:00 USA - Speech by Boston Fed President Susan Collins
- 23:45 New Zealand - Tourist Arrivals MoM. Previous reading: 0.5%.
- TBD China - M2 Money Supply YoY. Consensus: 7.4%. Previous reading: 7.5%.
- TBD China - New Bank Loans. Consensus: 1,025B. Previous reading: 60B.
- All Day Global - IMF and World Bank Annual Meetings (Day 2)
Corporate Earnings
- JPMorgan Chase & Co (JPM) — before market open, EPS forecast: $5.94. The largest US bank, a key indicator of consumer financial health and loan loss provision scale.
- Johnson & Johnson (JNJ) — before market open, EPS forecast: $2.53. Defensive barometer of the healthcare sector and demand stability for medical equipment and pharmaceuticals.
- UnitedHealth Group Incorporated (UNH) — before market open, EPS forecast: $4.12. Important insight into healthcare costs and US insurance market profitability.
- The Goldman Sachs Group, Inc. (GS) — before market open, EPS forecast: $12.90. Main barometer of capital markets activity, trading revenues, and M&A recovery.
- Wells Fargo & Company (WFC) — before market open, EPS forecast: $1.85. Key player in the US mortgage market and net interest income.
- Citigroup Inc. (C) — before market open, EPS forecast: $2.66. Company undergoing business transformation, offering insight into global corporate flows and transaction banking.
- Domino's Pizza Inc (DPZ) — before market open, EPS forecast: $4.33. Benchmark for discretionary consumer spending in the quick-service restaurant segment.
- Albertsons Companies, Inc. (ACI) — before market open, EPS forecast: $0.31. Gauge of household purchasing behavior amid grocery inflation.
- AZZ Inc. (AZZ) — after market close, EPS forecast: $1.82. Reflection of demand for metal coatings and the health of the industrial infrastructure sector.
- Other reporting companies today: FB Financial Corporation (FBK, before open, EPS forecast: $1.21), Unity Bancorp, Inc. (UNTY, EPS forecast: $1.49), FingerMotion, Inc. (FNGR), and Biomerica, Inc. (BMRA).
Markets to Watch
- S&P 500 / Financial Sector (XLF) — financial earnings reports from major institutions will set the direction for US indices at the start of the quarter.
- Crude Oil (Brent / WTI) — Middle East tensions and flight suspensions in the region generate demand pressure amid concerns over supply continuity.
- Australian Dollar (AUD/USD) — currency pair reacts to the contrast between hawkish RBA minutes and a sharp slump in NAB business confidence amid global risk aversion.
US500: Index rises, banks do not. Earnings season is a test for this divergence
Today's start to the bank earnings season in the US hits a market that is itself sending mixed signals. US500 has built an uptrend from the mid-September low (around 7550 pts) and is challenging highs in the 7800-7850 pts region. The problem is that it is doing so without the participation of financial leaders.
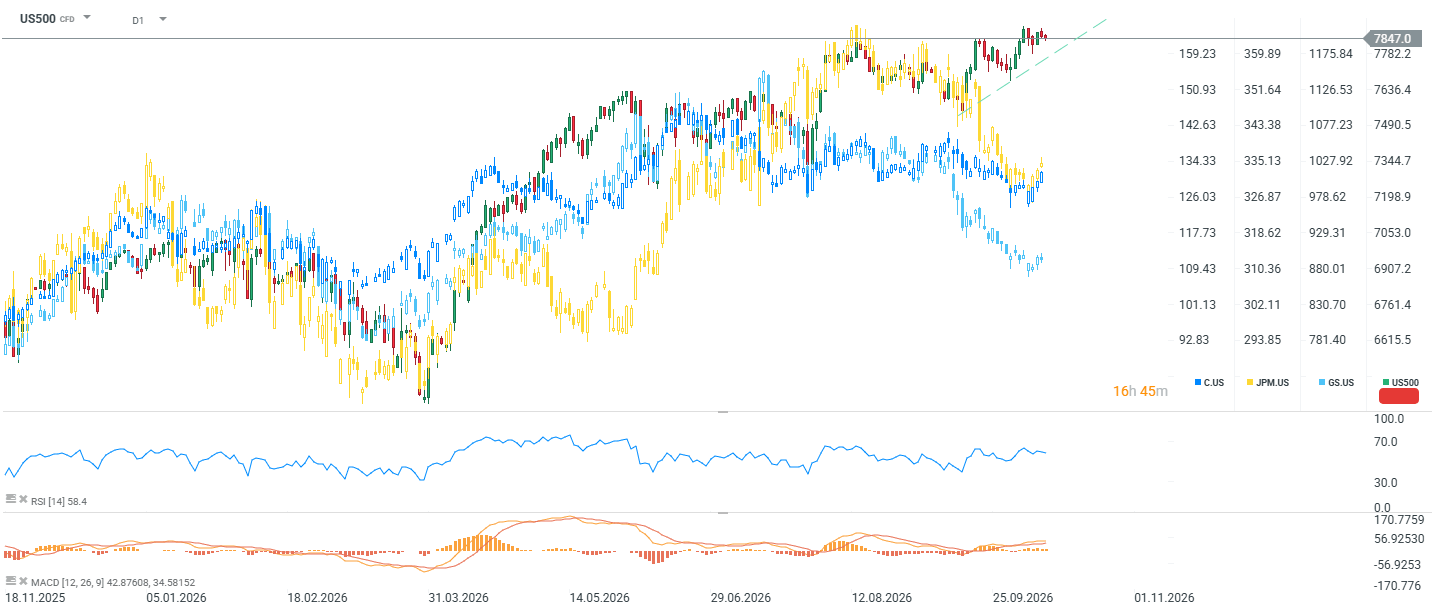
JPMorgan and Citi have been moving sideways since August, failing to confirm new index highs. Goldman Sachs is performing relatively strongest, but is not breaking out decisively above previous highs either. This is a classic warning sign — when the index rises without confirmation from a sector acting as a barometer of the economy's credit health, gains become increasingly dependent on a narrow group of non-financial leaders.
Indicators confirm weakening momentum rather than a potential reversal. RSI(14) at 58.4 is in neutral territory. Technically, room for further movement exists. MACD, however, shows a shrinking histogram despite rising prices — a negative momentum divergence similar to the one before the September pullback.
What this means for the reaction to earnings:
Strong earnings (especially robust trading and investment banking) could close the divergence in the healthiest way — lifting bank stocks and validating the index strength. The risk is a scenario of decent earnings paired with cautious guidance (credit quality, reserves), as the market may then deem the divergence justified and begin taking profits toward the trend line (around 7600-7650 pts) or lower toward 7300-7350 pts. Tech stock sell-offs could also contribute, considering the strong correlation between the Nasdaq and KOSPI.



Morning Wrap: Tech Crash in Asia and Hawkish Central Banks in the Shadow of an Oil Shock (13.10.2026)



📊Market Wrap: Europe Rebouns Despite Higher Oil and Dollar (12.10.2026)


Chart of the Day: Will the RBI's bold regulatory package rescue the rupee? (12.10.2026)


Economic Calendar: Where will stock exchanges remain closed today? (12.10.2026)
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.