


Sentiment in global financial markets continues to be shaped by the post-election political landscape in the US, but investors' attention is increasingly focused on current macroeconomic readings. The European industrial sector delivered mixed signals: factory orders in Germany rose by 4.4% m/m in September, while industrial production in France recorded a decline of 0.5% m/m. Combined with the preliminary estimate of the HICP inflation rate at 4.0%, the economic environment of the eurozone remains challenging. It is worth remembering that the statutory objective of the European Central Bank is solely to maintain price stability. The ECB's persistent restrictive stance may further hinder the recovery of European industry in the short term.
The Bank of England raised its key interest rate by 25 bps to 4.00%. Monetary authorities signaled that today's move is unlikely to be the last hike unless the military conflict surrounding Iran is resolved. At the same time, the bank raised the UK's GDP growth forecast for 2026 to 1.6% and increased inflation expectations, projecting the rate to peak at 4.9% in Q2 2027.
Furthermore, Norges Bank kept its main interest rate unchanged at 4.50%, which was in line with market consensus. However, the hawkish tone of the statement indicates that policymakers allow for a resumption of rate hikes if necessary in the process of bringing inflation to target.
FX Market
The dollar remains under pressure...
- EURUSD: The single currency's quotations are correcting by a symbolic 0.06% towards 1.1220, influenced by mixed readings from the European economy and concerns about the health of the industrial sector.
- GBPUSD: The pound records a modest increase of 0.05% to 1.3475 following the announcement of an interest rate hike by the Bank of England.
- USDPLN: The dollar exchange rate rises by 0.24%, stabilizing in the 3.91 region.
Commodities Market
- Crude oil: Brent (+2.2%) and WTI (+1.9%) quotes are rising, attempting to stabilize after a sharp, over 14% sell-off on a weekly basis, as the market political premium associated with Donald Trump is reduced.
- Natural gas: European gas (NATGAS.EU) rebounds sharply (+6.15%) after steep weekly declines, while the US benchmark NATGAS loses 0.31%, consolidating
- Gold: continues to appreciate (+1.67%), supported by a weaker US currency and lower treasury yields.
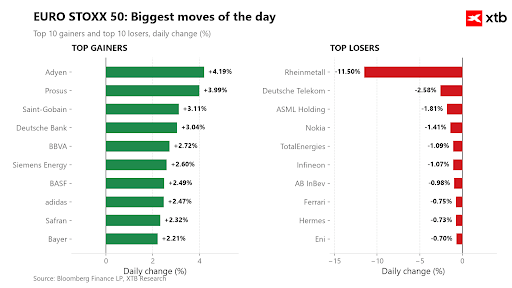
European Stocks
Top gainers:
- Prosus NV (PRX.NL): Shares of the technology holding company gain thanks to the continuation of the share buyback program and improved profitability in key e-commerce segments (up by nearly 4%).
- Compagnie de Saint-Gobain SA (SGO.FR): The company is rising thanks to effective margin defense through pricing discipline and favorable European thermal modernization trends (up by 3%).
- Adyen NV (ADYEN.NL): The share price is rebounding from an earlier wave of sell-offs, supported by double-digit revenue growth and more attractive valuation multiples (up by around 4%).
Top losers:
- Rheinmetall AG (RHM.DE): The sharp sell-off is the result of lowered forecasts for 2026 caused by the postponement of the Boxer vehicle contract and delays in ammunition acceptance (down by around 11%).
- TotalEnergies SE (TTE.FR): Selling pressure stems from general weakness in the oil and gas sector following declines in oil prices on world markets this week (down by slightly over 1%).
- ASML Holding NV (ASML.NL): The decline aligns with cooling sentiment in the semiconductor industry and market concerns over cuts in capital expenditures on chips (down by around 2%).


Norges Bank keeps rates unchanged, but leaves the door open to rate hikes. Is this really the end of the NOK strengthening, though?


Daily Summary: Blue Wave in Congress Triggers Market Euphoria, Oil Plunges

🛢️Oil suffers sharpest fall since April (-9%)
BREAKING: US oil inventories fall less than expected, but prices drop due to elections and hopes for a US-Iran deal
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.