


ServiceNow suffered a crushing sell-off of nearly 25% after releasing its Q3 2026 results. Were the figures and guidance really so terrible as to justify such a large and sudden loss in value?
Earnings
On the surface, the reported data was good, if not very good.
- Revenue grew a solid 20% year over year, reaching USD 4.1bn, slightly above consensus, which hovered around USD 4.095bn.
- Short-term receivables increased by 20% to USD 13.65bn. Meanwhile, long-term receivables rose to USD 29.7bn, up 22% year over year.
- At the same time, the company highlighted an increase in contracts worth more than USD 5m to 19, representing 135% growth.
- Potentially the best piece of news for investors is yet another increase in the AVC forecast, this time to USD 1.7bn versus USD 1bn at the beginning of the year. At the same time, the company revealed that customer usage of AI agents increased 13-fold over the year.
- All of this also allowed the company to raise its FCF margin forecast to 36%.
In light of these results, which number drove the share price down by more than a dozen percent?
The cause was the company’s EPS, which came in at USD 1.00 instead of the expected USD 1.02. Those two cents are far more important to shareholders than it might initially seem.
The CFO attributed the shortfall to lower interest income and higher debt costs following the acquisition of Armis. This means that acquisition financing costs weigh on shareholders even when the acquired businesses meet operational targets.
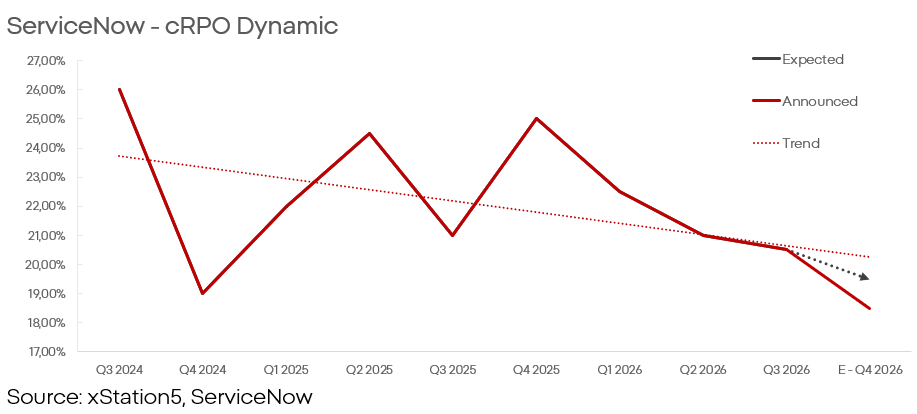
Not all guidance is positive either. Arguably even worse than EPS is forecast for cRPO growth (current remaining performance obligations) was cut for year-end to 18.5%. This is below the market’s minimum expectations of around 19% and signals a potential weakening, if not a breakdown, of operating leverage.
On its own, this signal is not a reason for as much concern as the market reaction suggests. However, a sustained decline in receivables growth relative to revenue would dramatically change the company’s outlook.
Beating the company’s own margin guidance does not mean margins improved year over year. The decline in profitability, even on an adjusted basis, suggests the issue cannot be explained solely by amortization of acquired assets.
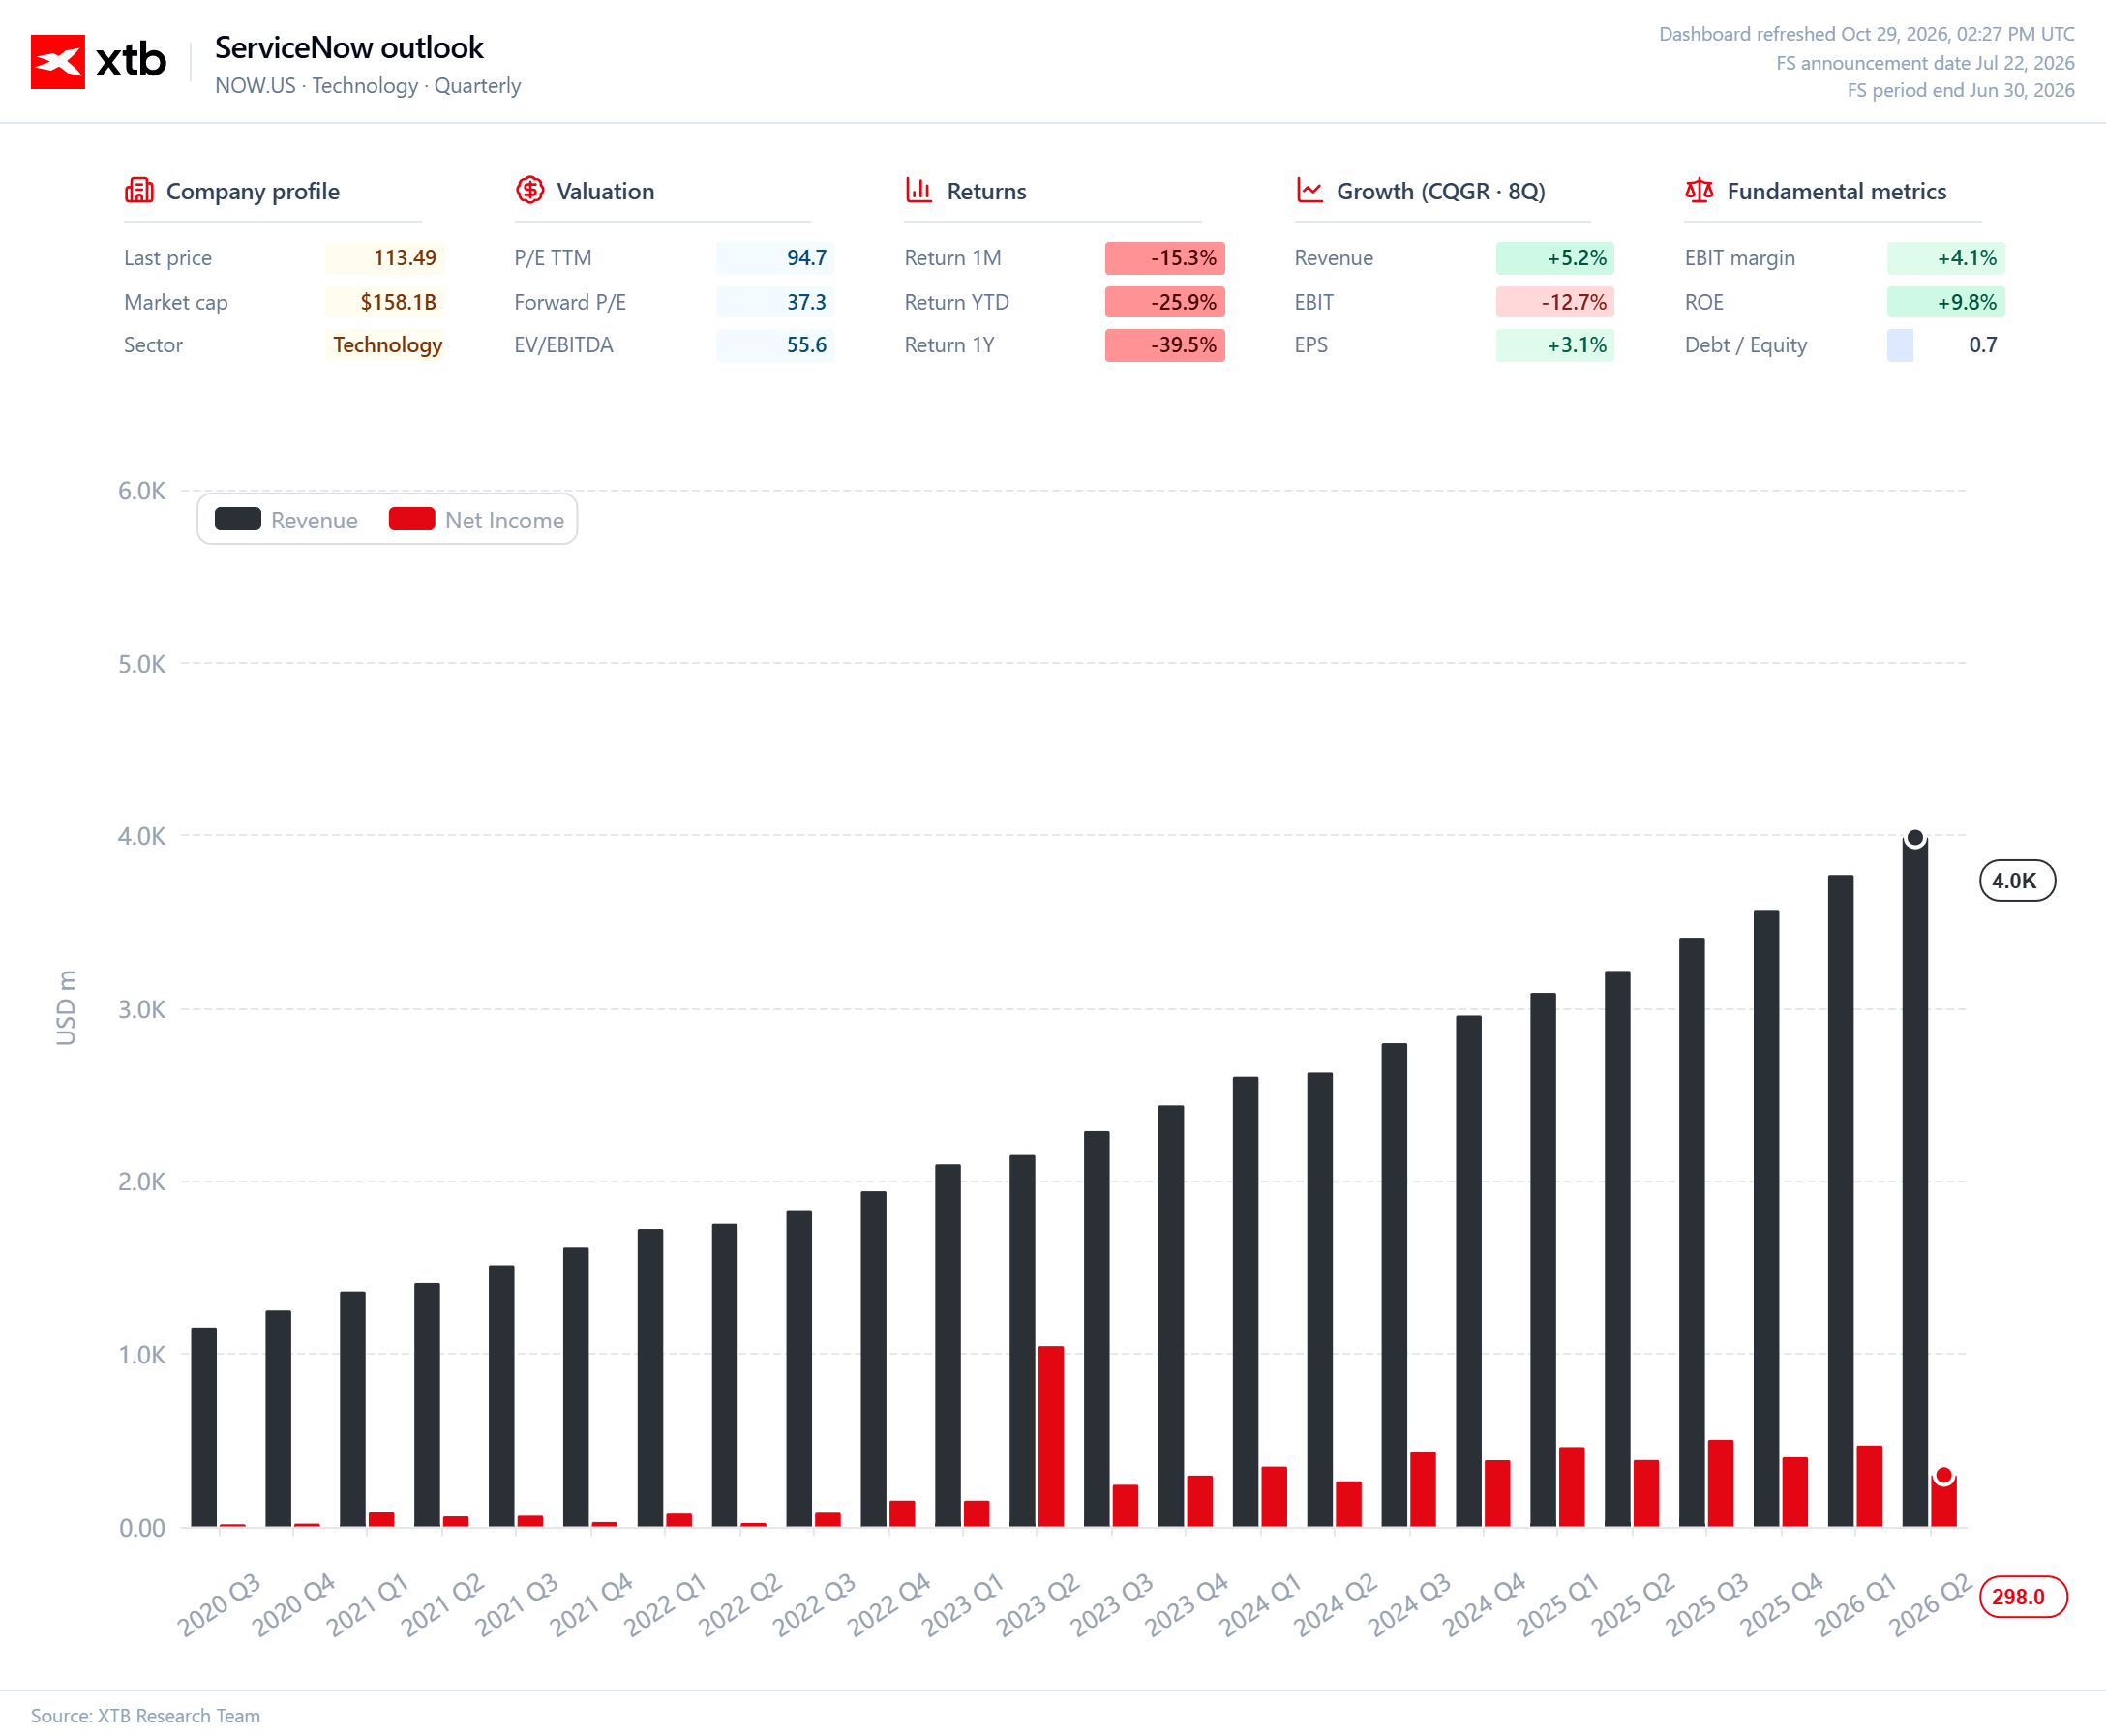
All of this indicates that, in the short- to medium-term, AI monetization will not be as fast or as inexpensive as the market had previously priced in. At the same time, monetization itself may not have as immediate an impact on profitability as earlier guidance implied.
Is the Panic Justified?
While margin compression, both adjusted and reported, is a genuine cause for significant shareholder concern, it is difficult to justify the scale of the stock’s reaction, even after accounting for operating leverage effects.
Management points to earlier renewals pulled into Q3, a larger share of on-premise implementations, and contracts with T4C clauses being excluded from backlog. Implementation support added to agreements shifts part of the value from subscriptions to services.
Growth remains solid by almost every measurable metric, and the customer base is expanding at a very high pace. Monetizing that base is an opportunity for enormous cash flows for the company and shareholders, even if it is moderately delayed.


Microsoft earnings: Cloud growth overshadows CAPEX & FCF questions



Daily Summary: Oracle drives the market higher, dollar weakens following Fed meeting (28.10.2026)


📊Hyperscaler Results: Alphabet and Microsoft. Will results justify giant investments?



Market Wrap: Renewed confidence in AI drives stock market recovery (27.10.2026)
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.