

- Intel plummets by nearly 29% following weak Q4 forecasts and ongoing PC market weakness.
- Binance suffers a record hacker attack resulting in the theft of 6.3 billion USD in digital assets.
- US tech indices face heavy selling pressure as massive artificial intelligence spending weighs on free cash flows.
- Intel plummets by nearly 30% following disappointing Q4 forecasts and persistent weakness in the PC processor market.
- Nasdaq loses over 2% at the open, deepening yesterday's Big Tech sell-off triggered by rising spending on artificial intelligence.
- Cryptocurrencies and related companies under pressure after a record hacker attack on the Binance exchange, from which $6.3 billion worth of assets were stolen.
The beginning of Friday's session across the ocean is marked by a sharp retreat from risk and a continuation of the deep sell-off of technology companies. The trigger for another wave of selling turned out to be the quarterly reports of Amazon and Intel, which confirmed investors' conviction that gigantic capital expenditures on artificial intelligence infrastructure are starting to weigh on free cash flows without bringing immediate monetization in core business segments. Sentiment is also weighed down by a huge security incident in the digital asset industry and geopolitical tensions between Washington and Tehran. With the VIX volatility index surging over 9%, capital is clearly withdrawing from risky assets and flowing toward US Treasuries.
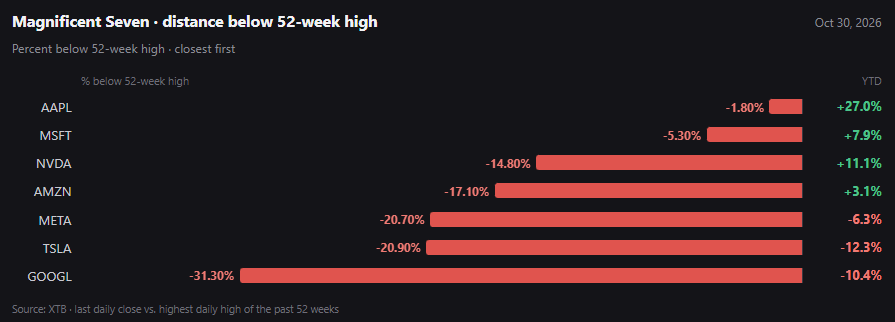 The Mag7 group looks terrible in terms of where the stocks stand compared to their 52-week highs. Nevertheless, Apple looks best in this comparison, still gaining solid ground year-to-date. Source: XTB
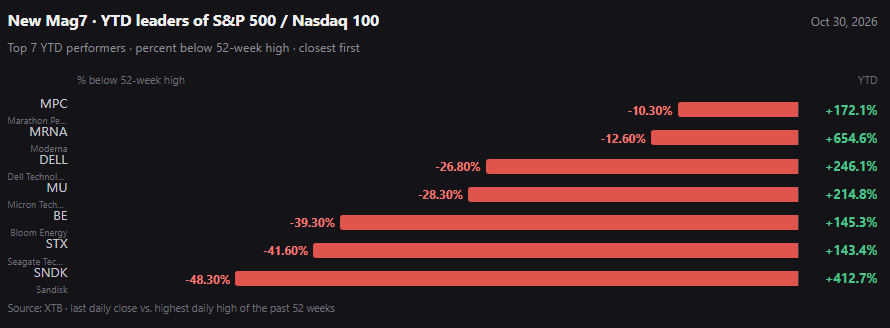 Looking at the "new" Magnificent 7, i.e., the strongest performers in the S&P 500 and Nasdaq 100 year-to-date, we also observe a clear pullback from 52-week highs. Source: XTB
Intel crash and the bill for the artificial intelligence boom
The US stock market faces a brutal valuation reality check in the semiconductor and tech giant sectors. Although investor attention earlier in the week focused on attempts at stabilization, earnings releases from Alphabet, Microsoft, and now Amazon and Intel, have triggered a avalanche of doubts regarding the sustainability of the AI arms race. After Alphabet lost over half a trillion dollars in market cap during the previous session, Friday's focus turns to the massive cash drain at other industry leaders. Hyperscalers are increasingly turning to debt financing—symbolized by Microsoft's $25 billion bond issuance—while their traditional profit engines, such as digital advertising and e-commerce, show signs of slowing down.
Negative sentiment spread broadly across the digital asset market following an unprecedented attack on Binance, from which $6.3 billion was siphoned off, dragging Bitcoin down toward $77,000. Flight to safety is supporting the US government debt market, where Treasury yields are falling in response to safe-haven demand. Meanwhile, a risk premium remains in crude oil markets due to reports that the US is considering military options regarding Iran.
Major stock indices are recording clear losses at the market open:
- US500: trading around 7,664 pts (-0.5%), the broad market index buckles under the weight of tech megacaps, though defensive and industrial sectors partially cushion losses.
- US100: trading near 28,816 pts (-0.8% on futures, with the spot Nasdaq Composite down over 2.2%), the tech benchmark is the epicenter of today's sell-off.
- US30: around 52,297 pts (-0.4%), the traditional blue-chip index performs relatively best thanks to lower exposure to chip manufacturers and cloud providers.
- US2000: trading near 2,841 pts (-0.8%), the small-cap index loses ground amidst general risk aversion, despite maintaining a modest gain for the week.
US100 Technical Analysis
On the US100 tech index, the technical setup deteriorated sharply after breaking below local consolidation. According to futures market data, contract prices slid to around 28,816 pts, losing nearly 1.6% on a weekly basis. The chart is currently testing a critical support zone defined by the 10-week moving average. The 29,000 pt level, which served as a key local low in recent days, was breached. Momentum indicators turned sharply lower, reflecting a sudden surge in supply. The primary static resistance for the index now lies in the 29,000–29,200 pt zone, where former support has turned into a supply barrier. A fall back below the downward trendline of the recent correction, along with the lowest levels since early August, signals significant trouble—a situation that could currently only be reversed by a rebound in sentiment following US midterm elections and upcoming results from giants like Apple or AMD.
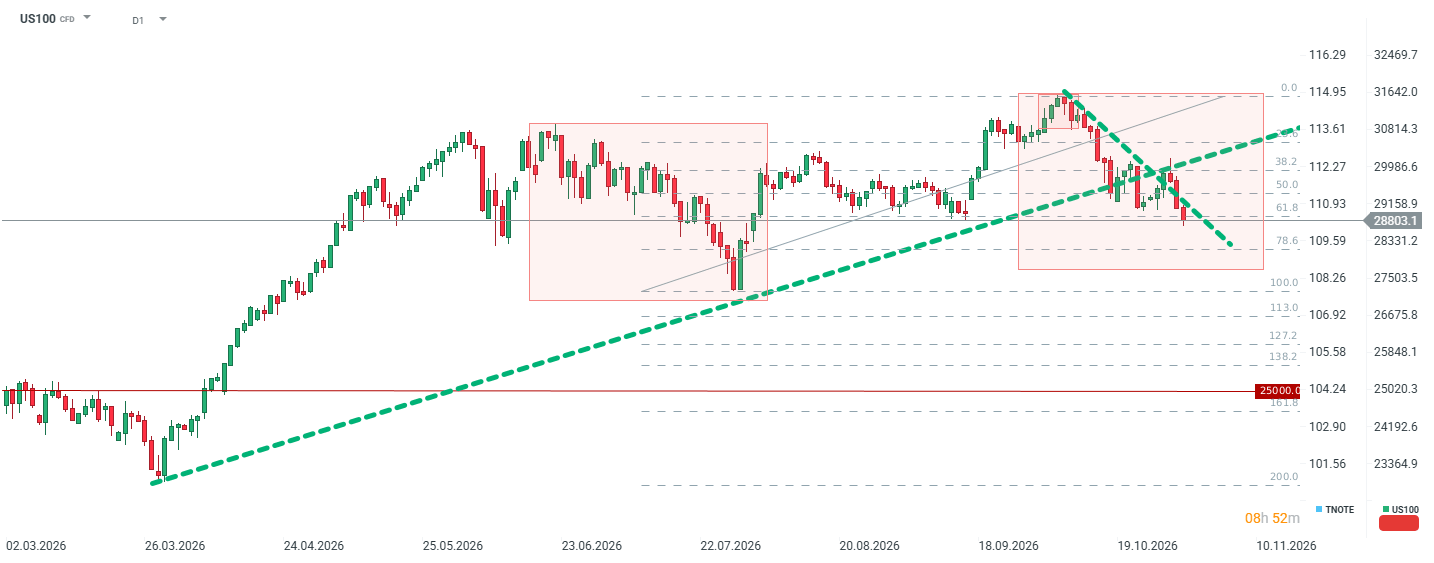
- Bearish scenario: A sustained session close below 29,000 pts opens the path for bears toward a deeper correction targeting the 40-week moving average around 27,800 pts. The next psychological reference point remains around 27,500 pts.
- Bullish scenario: Halting selling pressure requires a swift rebound above 29,000 pts and a dynamic break above 29,350 pts, which would signal a false breakdown and could trigger a short-covering rally, given short interest on the QQQ ETF reached multi-year highs since 2023.
Key Corporate News
- Chipmakers slump: Intel (INTC.US) plummets by nearly 29% (trading around $65) after presenting dismal Q4 guidance (revenue expected at $15–16 billion vs. consensus of $17.08 billion, and EPS at $0.25 vs. $0.44 expected). CEO Lip-Bu Tan and CFO David Zinsner highlighted continued weakness in the PC market and supply chain bottlenecks, overshadowing a 78% surge in Data Center and AI segment revenues.
- Competitors are hit by collateral damage: AMD (AMD.US) drops 8.7% to around $517 (despite a P/E ratio of 142.6 and a YTD rally of 141%), while Nvidia (NVDA.US) retreats 3.2% to near $207.
- Amazon (AMZN.US) drops 2.8% to trade around $237. Investors skeptically received slowing growth in e-commerce and advertising, eclipsing a record $46 billion in revenue from the AWS cloud division. Concerns were also raised by plans to maintain full-year capital expenditure (capex) at $220 billion, pushing trailing 12-month free cash flow (FCF) into negative territory. The RSI index dipped into oversold territory at 36.4, while consensus analyst ratings (4.86/5) maintain a price target of $314.42.
- Alphabet (GOOGL.US) slips 1.0% to near $281, continuing its decline following Thursday's crash of over 10%. The market continues to digest slower growth in search revenue (12%) and negative FCF last quarter. Shares remain in deep technically oversold territory with an RSI of 21.9 and a P/E ratio of just 16.3 (analyst target stands at $433.94).
- Microsoft (MSFT.US) retreats 2.2% to around $518. Although Azure recorded solid 48% growth with margins around 50%, the need to place $25 billion in debt to finance AI infrastructure dampened buyer enthusiasm. Valuation stands at a P/E ratio of 29.4.
- Sell-off in software and social media: Reddit (RDDT.US) plummets 25.8% (to around $96) following disappointing daily active user (DAU) figures and weaker Q4 revenue guidance, linked by analysts to changes in Google search algorithms. Twilio (TWLO.US) drops 21.9% after issuing forecasts that renewed fears over AI tools negatively impacting traditional communication platforms.
- Crypto sector crash: Coinbase Global (COIN.US) dives 11.6% to near $142. Despite solid Q3 earnings, sentiment was hit by the massive attack on Binance and falling Bitcoin prices. MicroStrategy (MSTR.US) lost ground in similar fashion, falling over 9%.
- MedTech and pharma buck the trend: Regeneron Pharmaceuticals (REGN.US) surges 14.4% (trading near $929) after beating Wall Street Q3 earnings and revenue estimates. Eli Lilly (LLY.US) also stands out with gains, rising 4.6% toward $1,435.
- FedEx Freight Holding (FDXF.US) gains 12.7% to around $124 after reporting 9.2% revenue growth to $3.3 billion for the four-month period ending in September, along with solid Q4 guidance.
- Mondelez International (MDLZ.US) rises over 8% following its majority stake acquisition in Undercover Snacks and reiteration of full-year organic revenue targets.
What's the sentiment among retail investors?
- Capitulation and shock on Intel and Reddit threads: On r/wallstreetbets and r/stocks forums, disbelief dominates regarding the scale of the sell-off in Intel (-29%) and Reddit (-26%). Retail investors bitterly comment on Intel CFO's statements regarding lack of positive cash flow perspectives in 2027.
- Growing skepticism toward AI narrative: Discussions increasingly feature theories about an AI capex bubble bursting. Retail traders openly criticize megacap management (Amazon, Alphabet, Meta) for massive data center spending that eats free cash flow at the expense of core business performance.
- Potential fuel for a short squeeze: As JPMorgan strategists point out, retail investors aggressively bought leveraged ETFs during recent dips, pushing short positions on the QQQ ETF to multi-year highs. Any attempt to lift indices during the second half of the session could trigger rapid short covering by hedge funds.
- Panic surrounding the Binance hack: The digital asset trading community is reeling over reports of a $6.3 billion theft attributed to the North Korean TraderTraitor group. Despite exchange assurances regarding deposit safety, fears of forced liquidations and stablecoin liquidity drains dominate online forums.


Amazon: Record-breaking operating margin outshined by capex growth


ServiceNow Earnings: What Went Wrong?


Microsoft earnings: Cloud growth overshadows CAPEX & FCF questions



Daily Summary: Oracle drives the market higher, dollar weakens following Fed meeting (28.10.2026)
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.