


Wall Street is trading lower today, a day after the S&P 500 set another all-time high and closed above 7,800 points for the first time. Dow Jones futures are down around 0.8%, S&P 500 futures are falling 0.5%, while Nasdaq 100 futures are off by around 0.8%. Renewed gains in oil prices and US Treasury yields are adding pressure to equities. WTI is moving back toward $90 per barrel, while Brent is rising toward $101, reviving concerns over inflation and the interest-rate outlook. The 10-year Treasury yield has climbed above 5.33%, while the 30-year yield is around 5.72%, bringing both back close to their highest levels since 2002.
Investors are also awaiting a $39 billion auction of 10-year Treasury notes, which could provide another test of demand for US government debt. Attention is also focused on the minutes from the Fed’s September meeting, when the central bank raised interest rates for the first time since 2023. Despite today’s pullback, the broader market picture remains relatively strong, as the previous session was supported by gains in semiconductor stocks and a temporary decline in bond yields.
- US: Dow Jones futures are down around 0.8%, S&P 500 futures are off 0.5%, and Nasdaq 100 futures are down around 1%, as oil prices and bond yields rise.
- Bond market: the 10-year Treasury yield is up more than 6 basis points to around 5.35%, while the 30-year yield has risen more than 7 basis points to around 5.72%, both remaining near multi-year highs.
- Oil: WTI is approaching $90 per barrel, while Brent is up nearly 1% to around $101, adding to inflation concerns and weighing on equity valuations.
- Investors are waiting for the minutes from the September FOMC meeting, which may provide more detail on how Fed officials view inflation, growth and the future path of interest rates.
- The Stoxx 600 is down around 0.8%, the DAX 1.3%, the CAC 40 1%, the FTSE 100 0.7%, and the FTSE MIB around 1.9%.
- Japan’s Nikkei 225 fell 0.92%, South Korea’s Kospi nearly 2%, and the Kosdaq 2.34%, while the S&P/ASX 200 ended the session little changed and mainland Chinese markets remained closed for Golden Week.
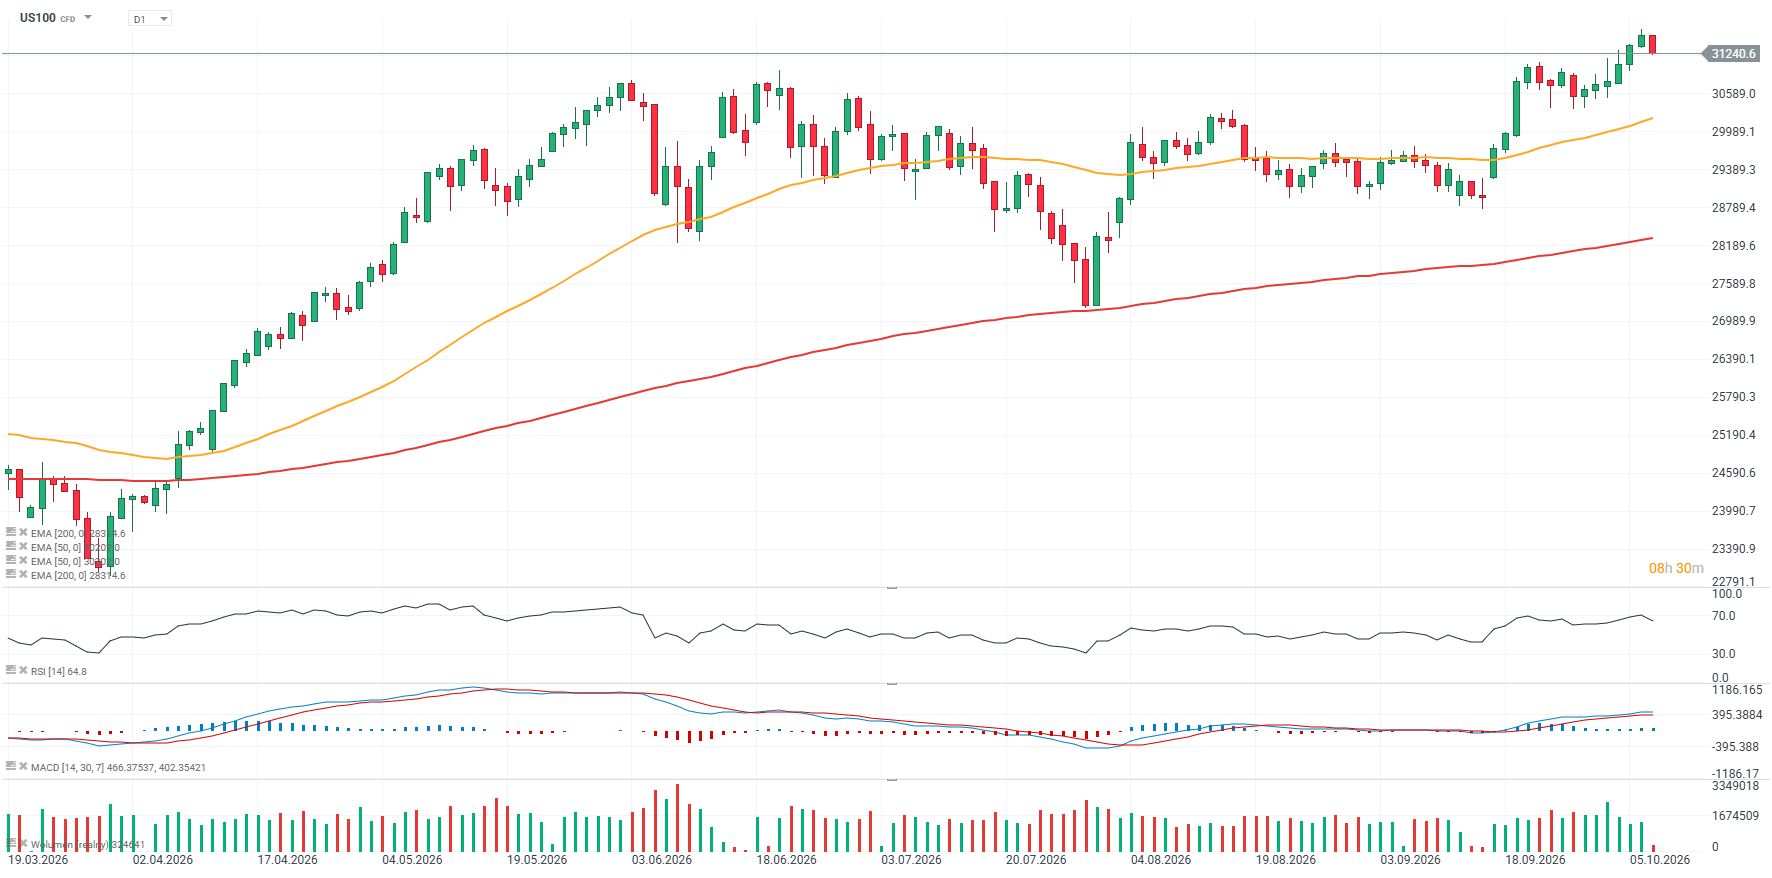
US100 chart (D1 timeframe)
Nasdaq 100 futures (US100) are pulling back from record highs today, while the US 10-year Treasury yield rose by nearly 8 basis points on Wednesday to around 5.35%, its highest level since April 2002. Such elevated yields increase financing costs across the economy and can weigh particularly heavily on growth-stock valuations.
 Source: xStation5
Company news
- Neogen is up around 11% after raising its full-year outlook. The company provides food-safety, diagnostics and testing solutions for the food and agriculture industries. It now expects revenue of $885–890 million, compared with its previous forecast of $880–885 million and the FactSet consensus of $883.2 million.
- Penguin Solutions is gaining more than 4% after reporting better-than-expected quarterly results. The company provides computing infrastructure and data-center solutions, including systems used in artificial intelligence projects. Adjusted earnings came in at $1.00 per share on revenue of $566.7 million, versus expectations of $0.77 and $521 million, respectively.
- Constellation Brands is gaining just under 2% after results exceeded market expectations. The company is a producer and distributor of alcoholic beverages, known in the US market for brands including Modelo and Corona. Earnings per share came in at $3.74 on revenue of $2.63 billion, although investors remained cautious about a 160-basis-point year-on-year decline in beer operating margins and slightly weaker demand.
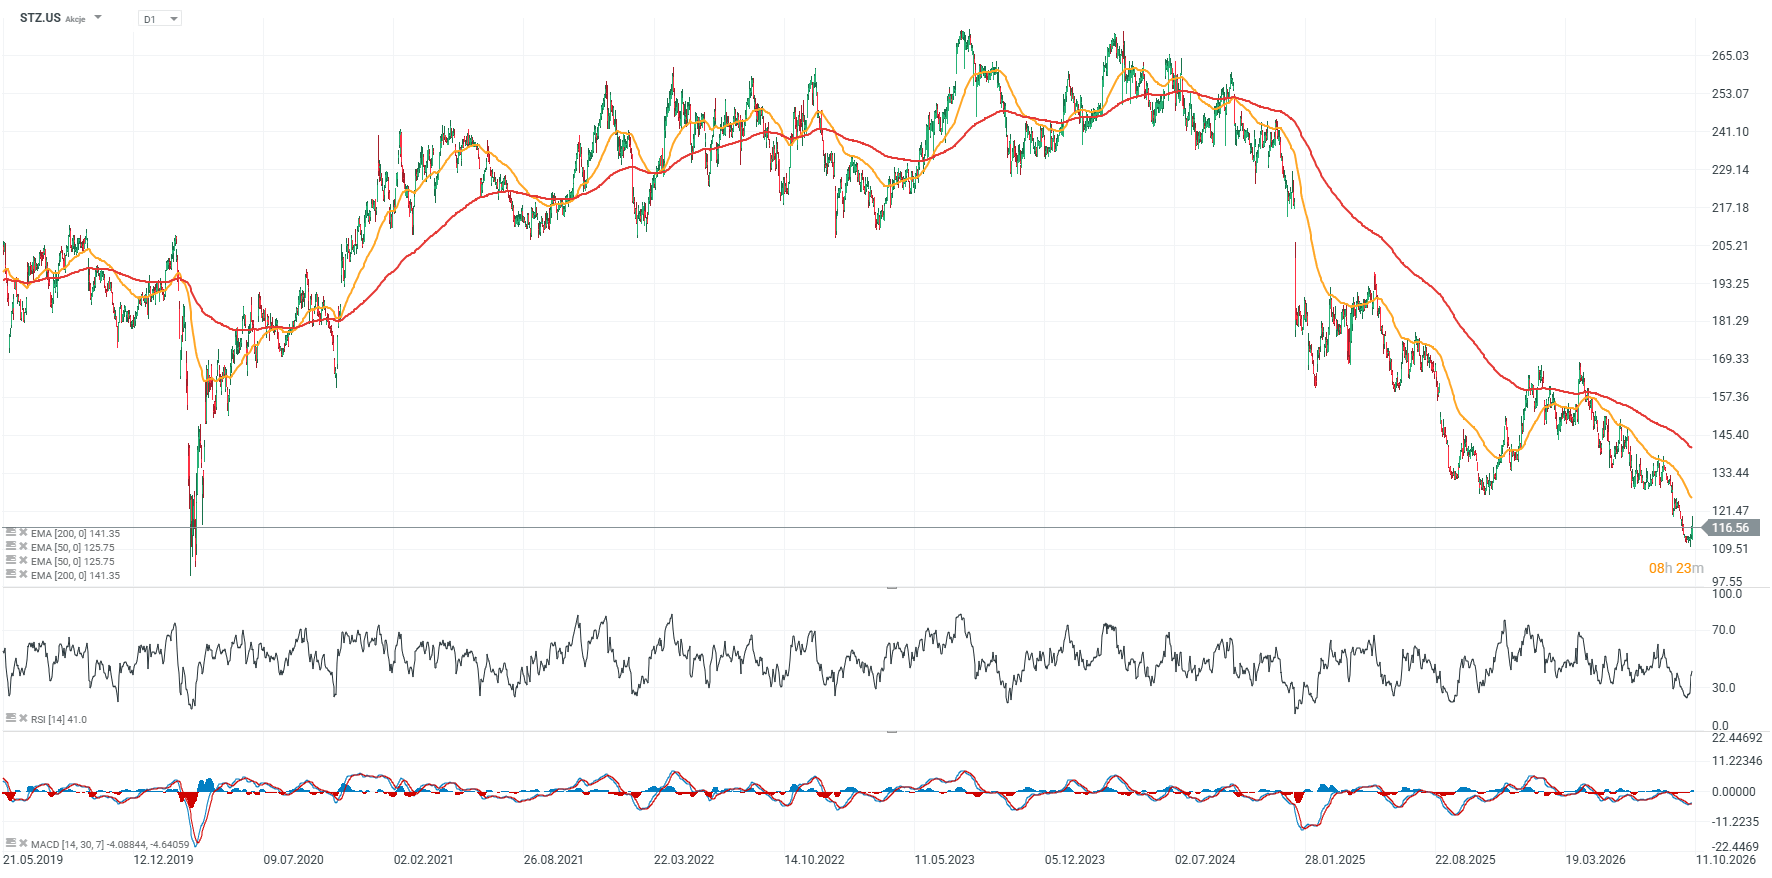
Constellation Brands STZ.US chart (D1 timeframe)
Over the past five years, Constellation Brands shares have fallen by almost 47% and are now trading near levels last seen in March 2020. Between 2012 and 2020, however, the company was one of the strongest performers in the beverage sector.
 Source: xStation5
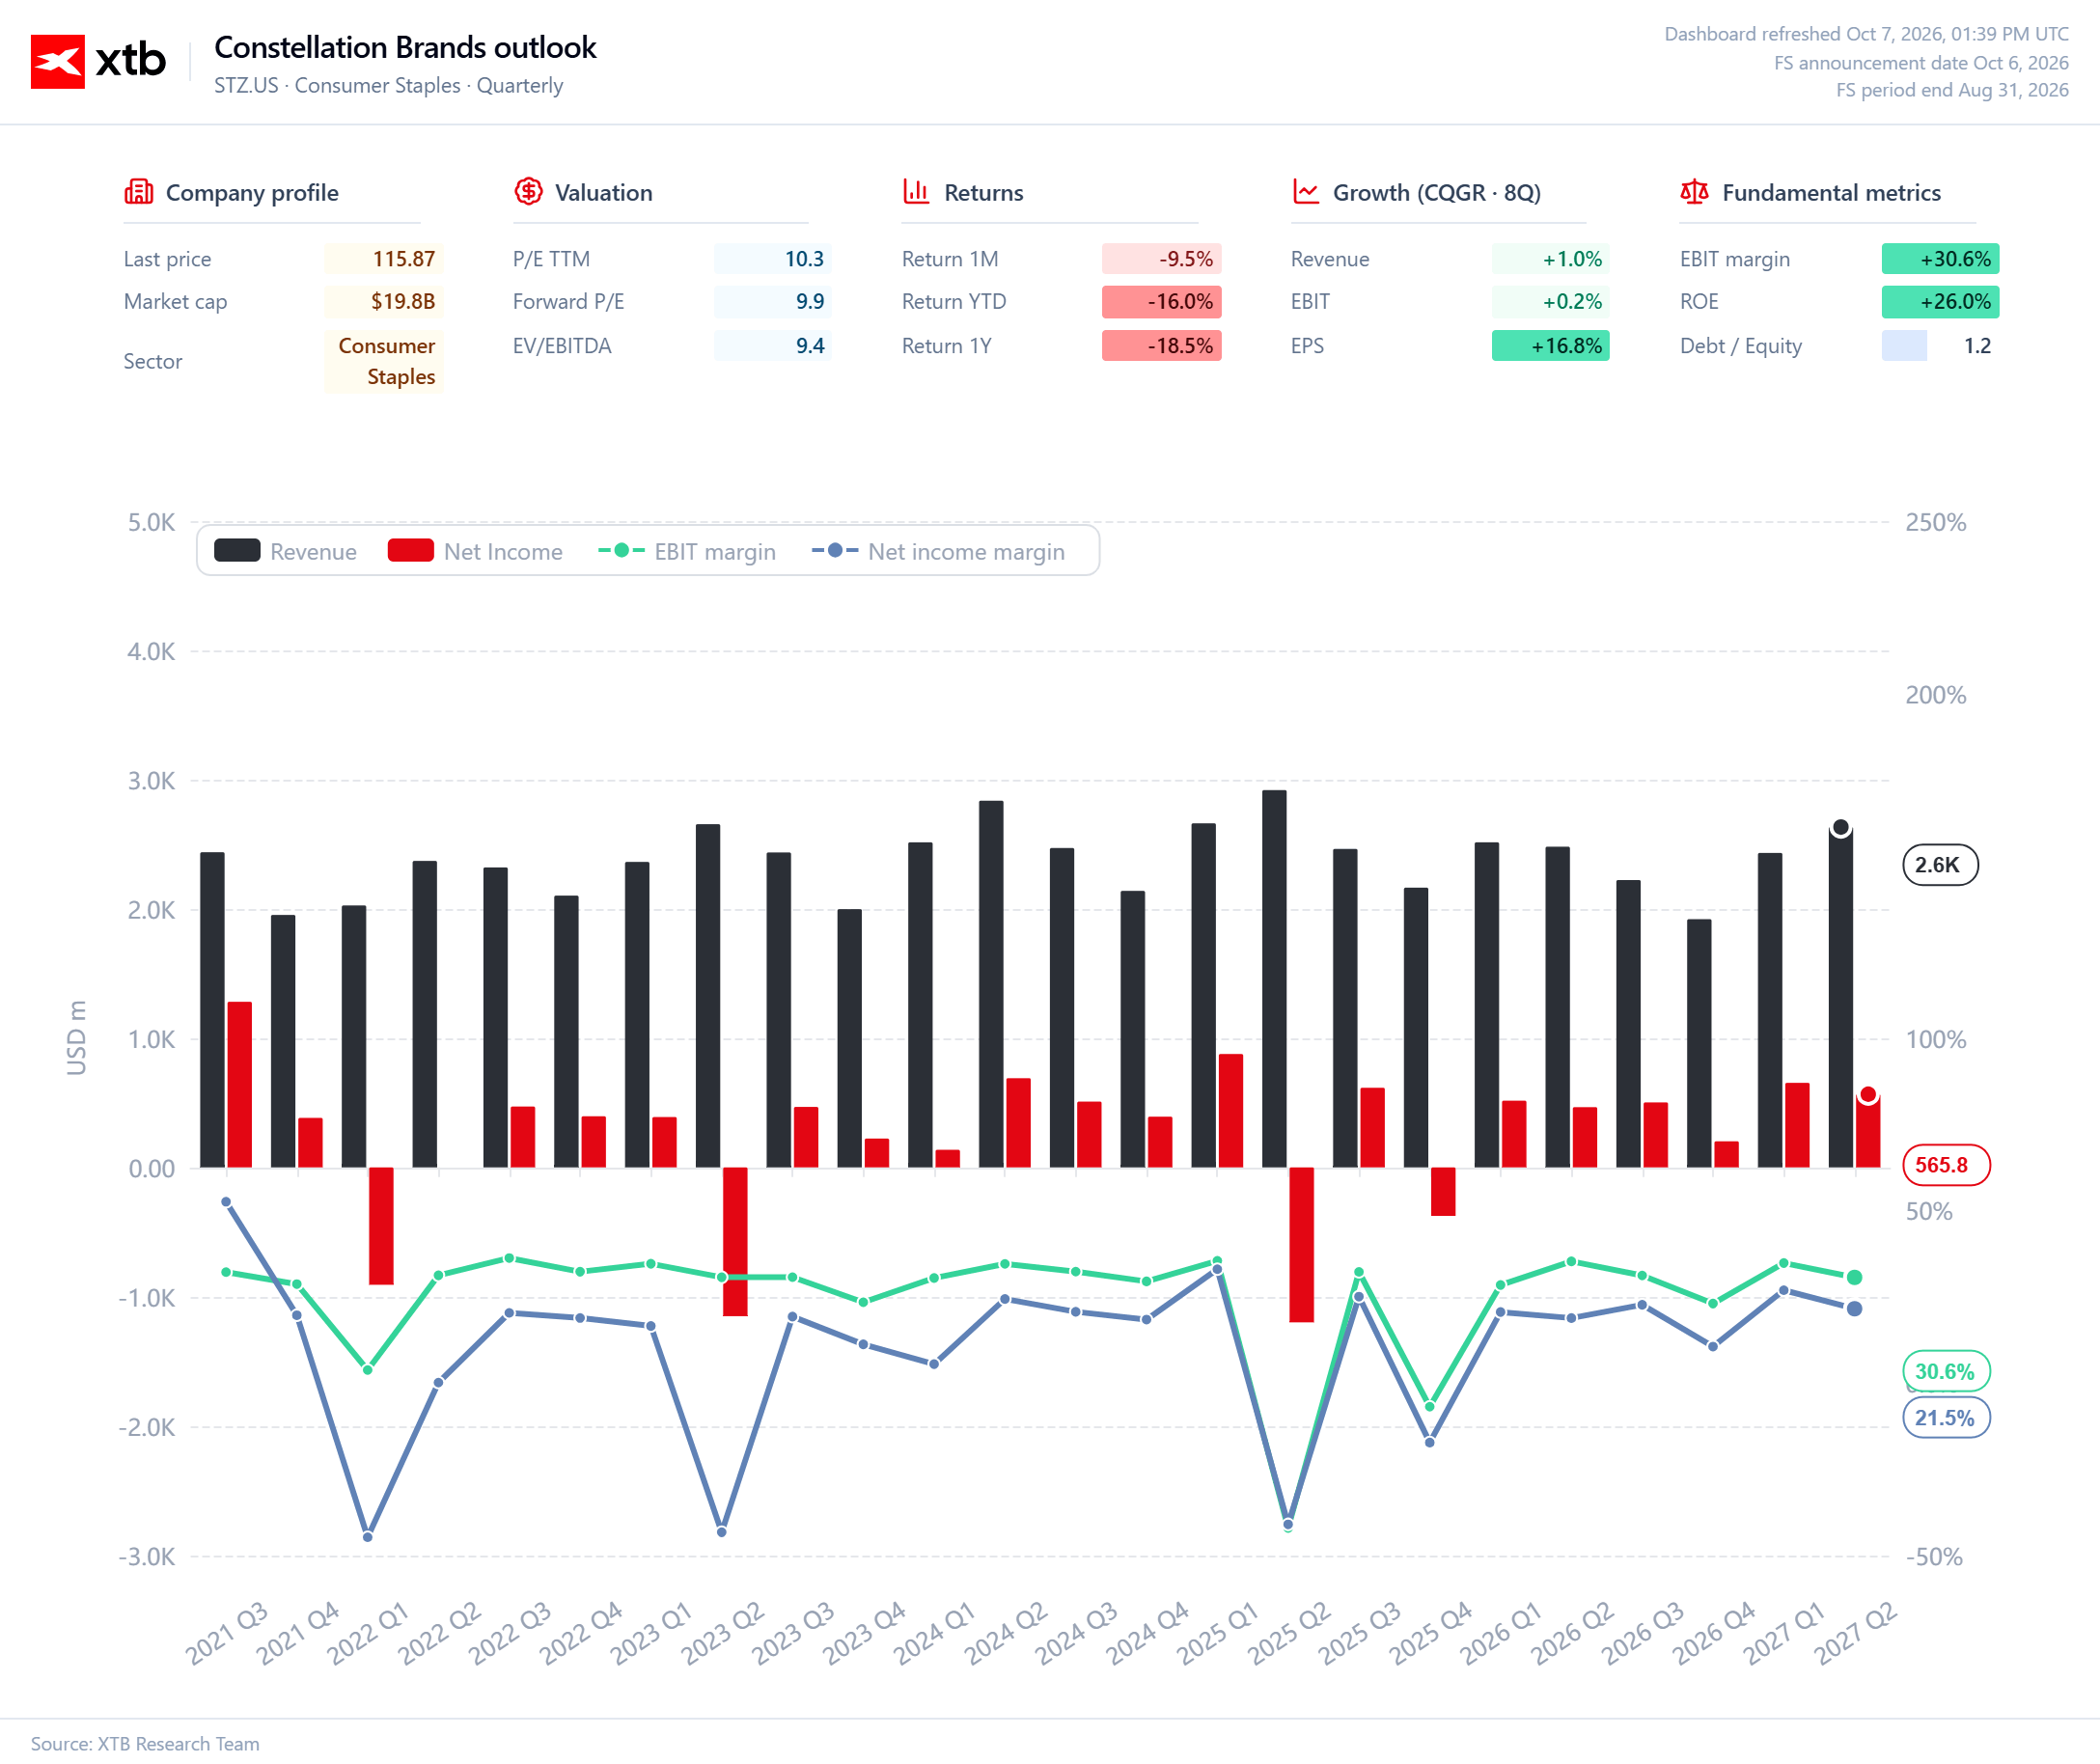
Constellation Brands currently looks significantly de-rated relative to its own history, with a trailing P/E of 10.3 and a forward P/E of 9.9, suggesting that the market has already priced in a meaningful degree of weaker sentiment and operational pressure. At the same time, the share price remains in a clear downtrend, with a year-to-date return of around -16% and a 12-month return of -18.5%, indicating that investors still demand a substantial risk discount. The underlying fundamentals, however, remain relatively solid: EBIT margin is still high at around 30.6%, while ROE stands at 26%, pointing to strong underlying profitability. Revenue and EBIT growth are close to flat, but expected EPS growth of 16.8% suggests that future earnings improvement may come more from efficiency, product mix and cost control than from rapid top-line expansion. The current setup can therefore be viewed as a classic case of a falling share price despite still-healthy margins, with the key question being not whether the stock is cheap, but whether the market is correctly pricing in a lasting slowdown in growth.
 Source: XTB Research


Large decline in crude inventories 🛢️📉

📉 Gold loses 1.7%

Wheat Rebounds? 📈 Weak U.S. Planting, Russian Exports Down 75%

Bitcoin Hits a Wall. Will “Uptober” Bring a Crypto Correction?
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.