



The performance of Amazon Web Services will be the most important factor. Last quarter, AWS revenue increased 37% year over year to $42.2 billion, marking its fastest growth rate in 18 quarters. The market now expects approximately $45.4 billion in cloud revenue, implying further year-over-year growth of nearly 38%. AWS must demonstrate that rising demand for computing power, AI services, and cloud infrastructure is enabling Amazon to expand its business at a pace that justifies increasingly large investments.
Following Microsoft’s and Alphabet’s earnings reports, however, simply confirming that customers continue to spend on cloud services will not be enough. Investors will be looking for evidence that Amazon can capitalize on this demand as effectively as its competitors. Both AWS revenue growth and segment profitability will be important. Consensus estimates point to an operating margin of approximately 37.3%, compared with the 35% expected as recently as the previous quarter. Strong revenue combined with an improving margin would be a much more encouraging signal for investors than growth achieved at the expense of further margin deterioration.
Key Market Expectations
-
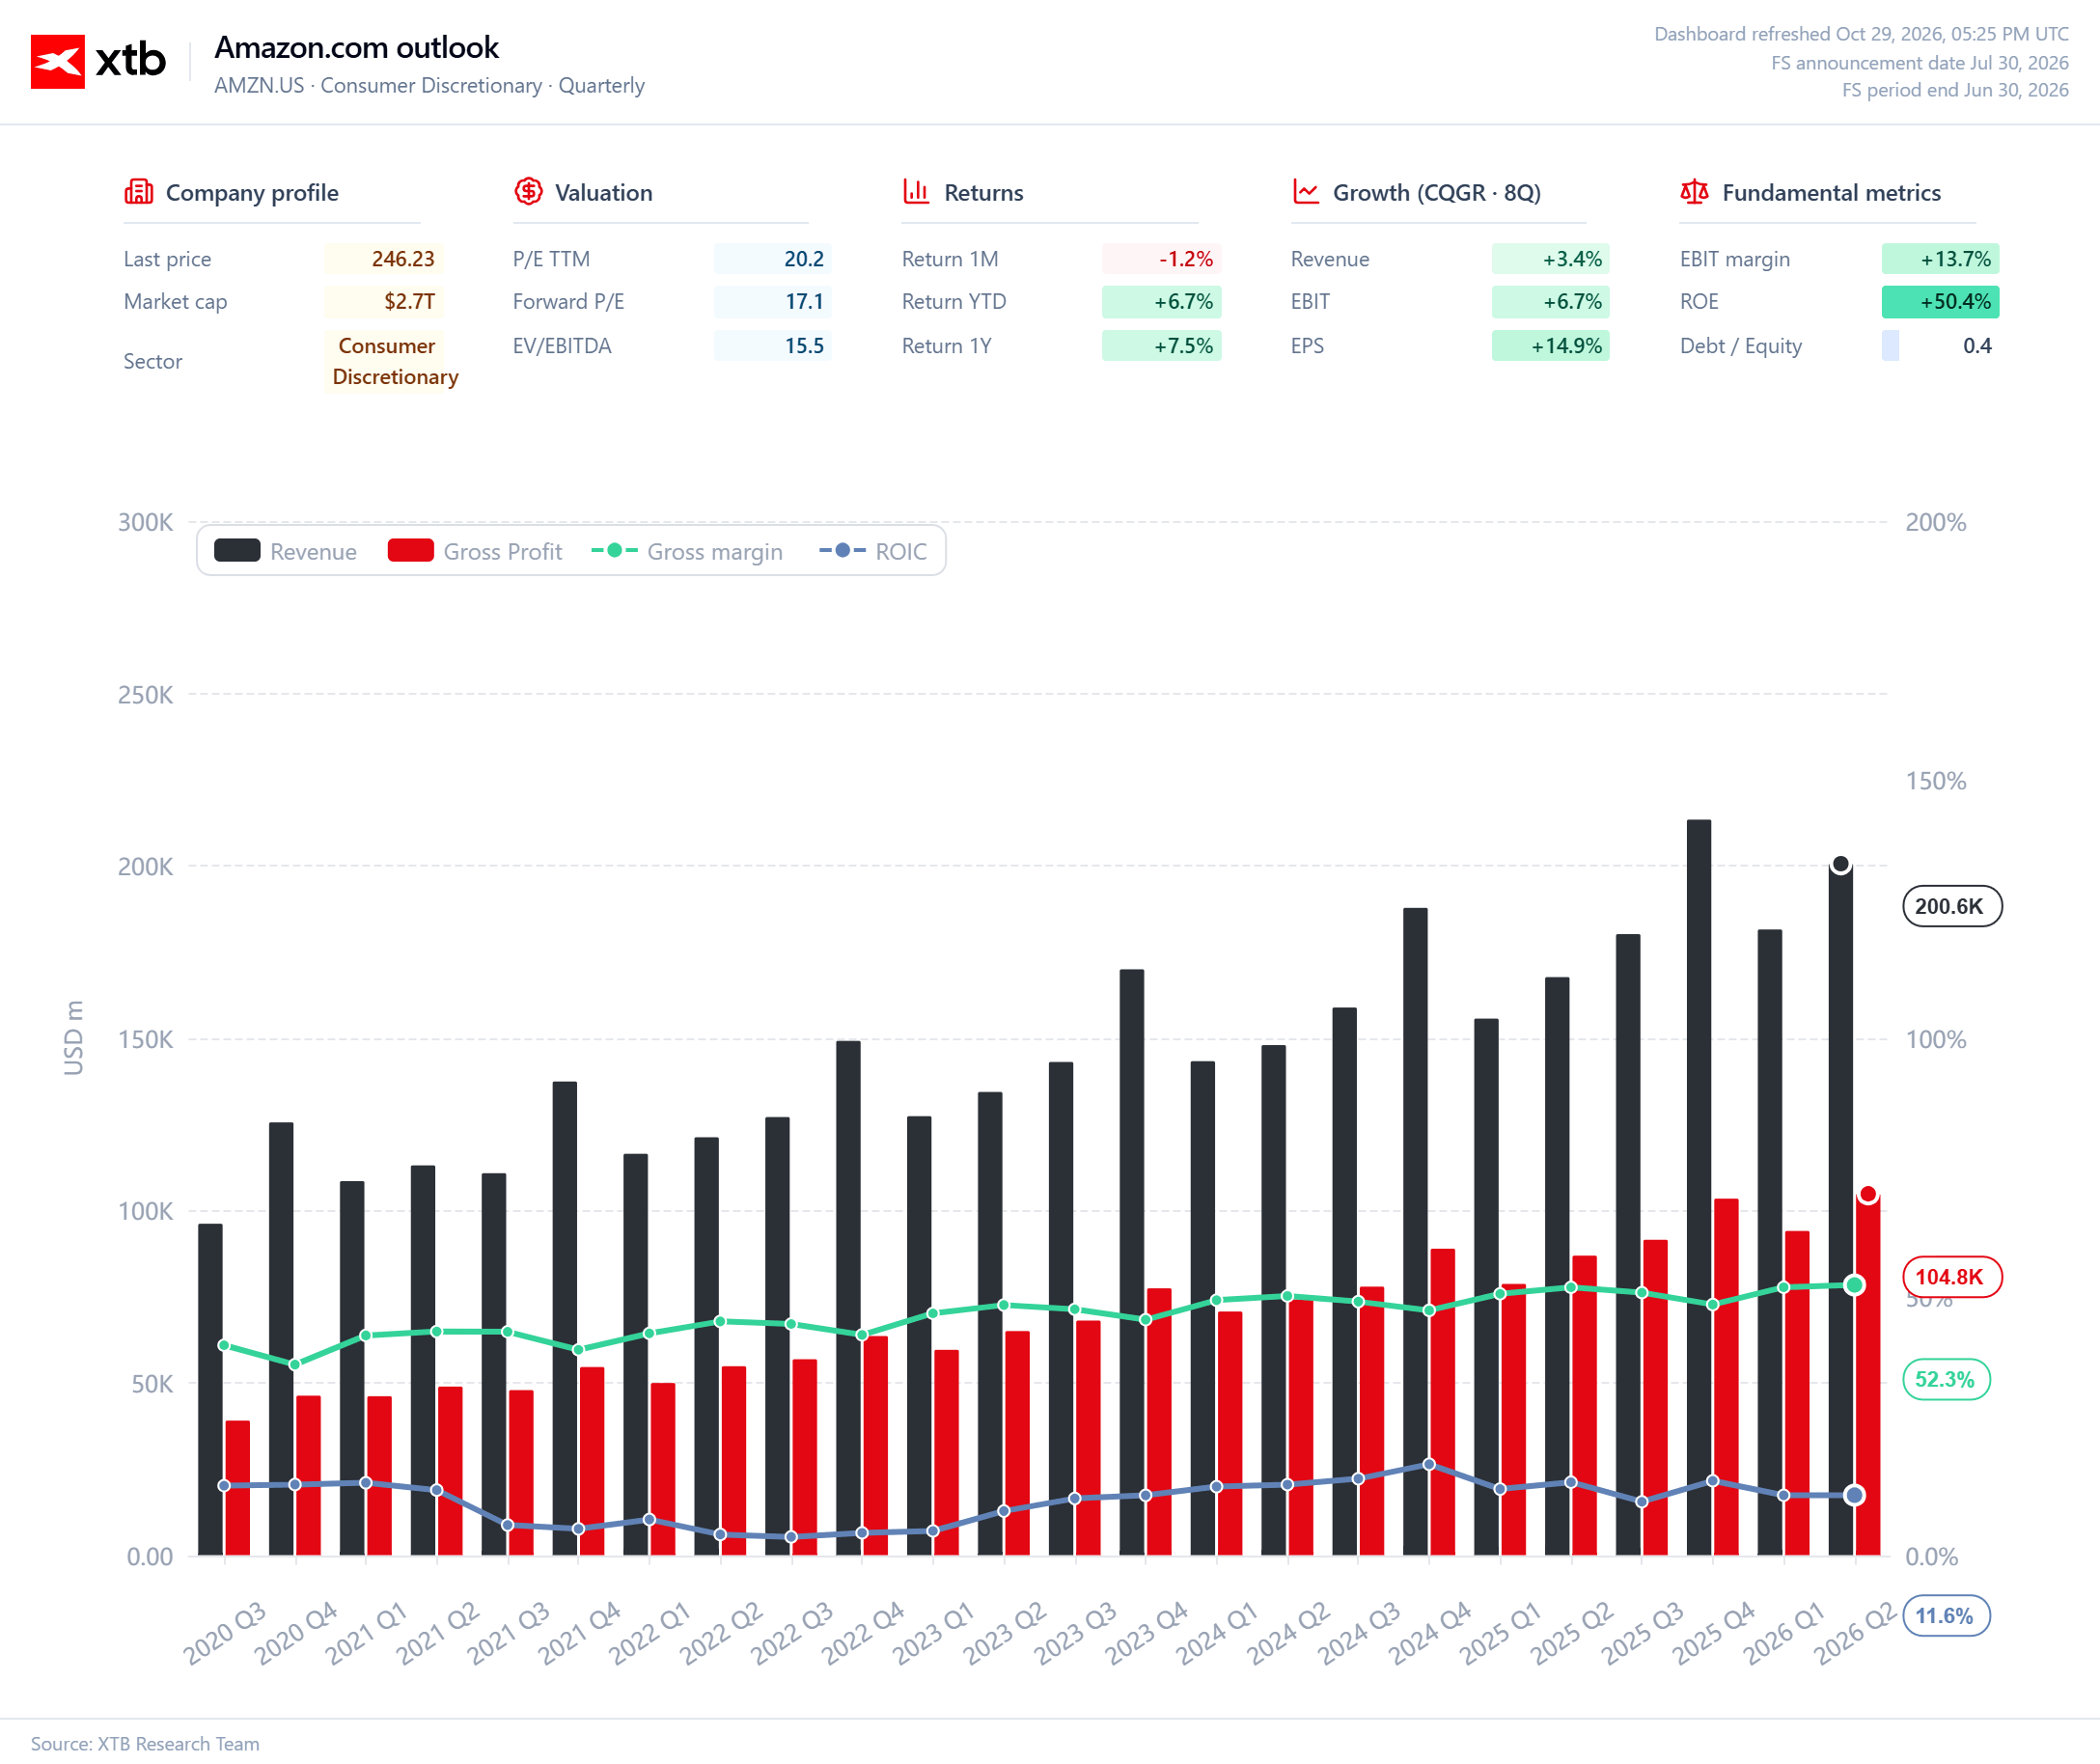
Total revenue: approximately $202.2 billion, up around 12% year over year.
-
Earnings per share: approximately $1.97.
-
AWS revenue: approximately $45.4 billion, up nearly 38% year over year.
-
AWS operating margin: approximately 37.3%.
-
North America revenue: approximately $113.8 billion.
-
North America retail operating margin: approximately 6.8%.
-
2026 capital expenditure: approximately $220 billion.
AI Spending Must Start Delivering Results
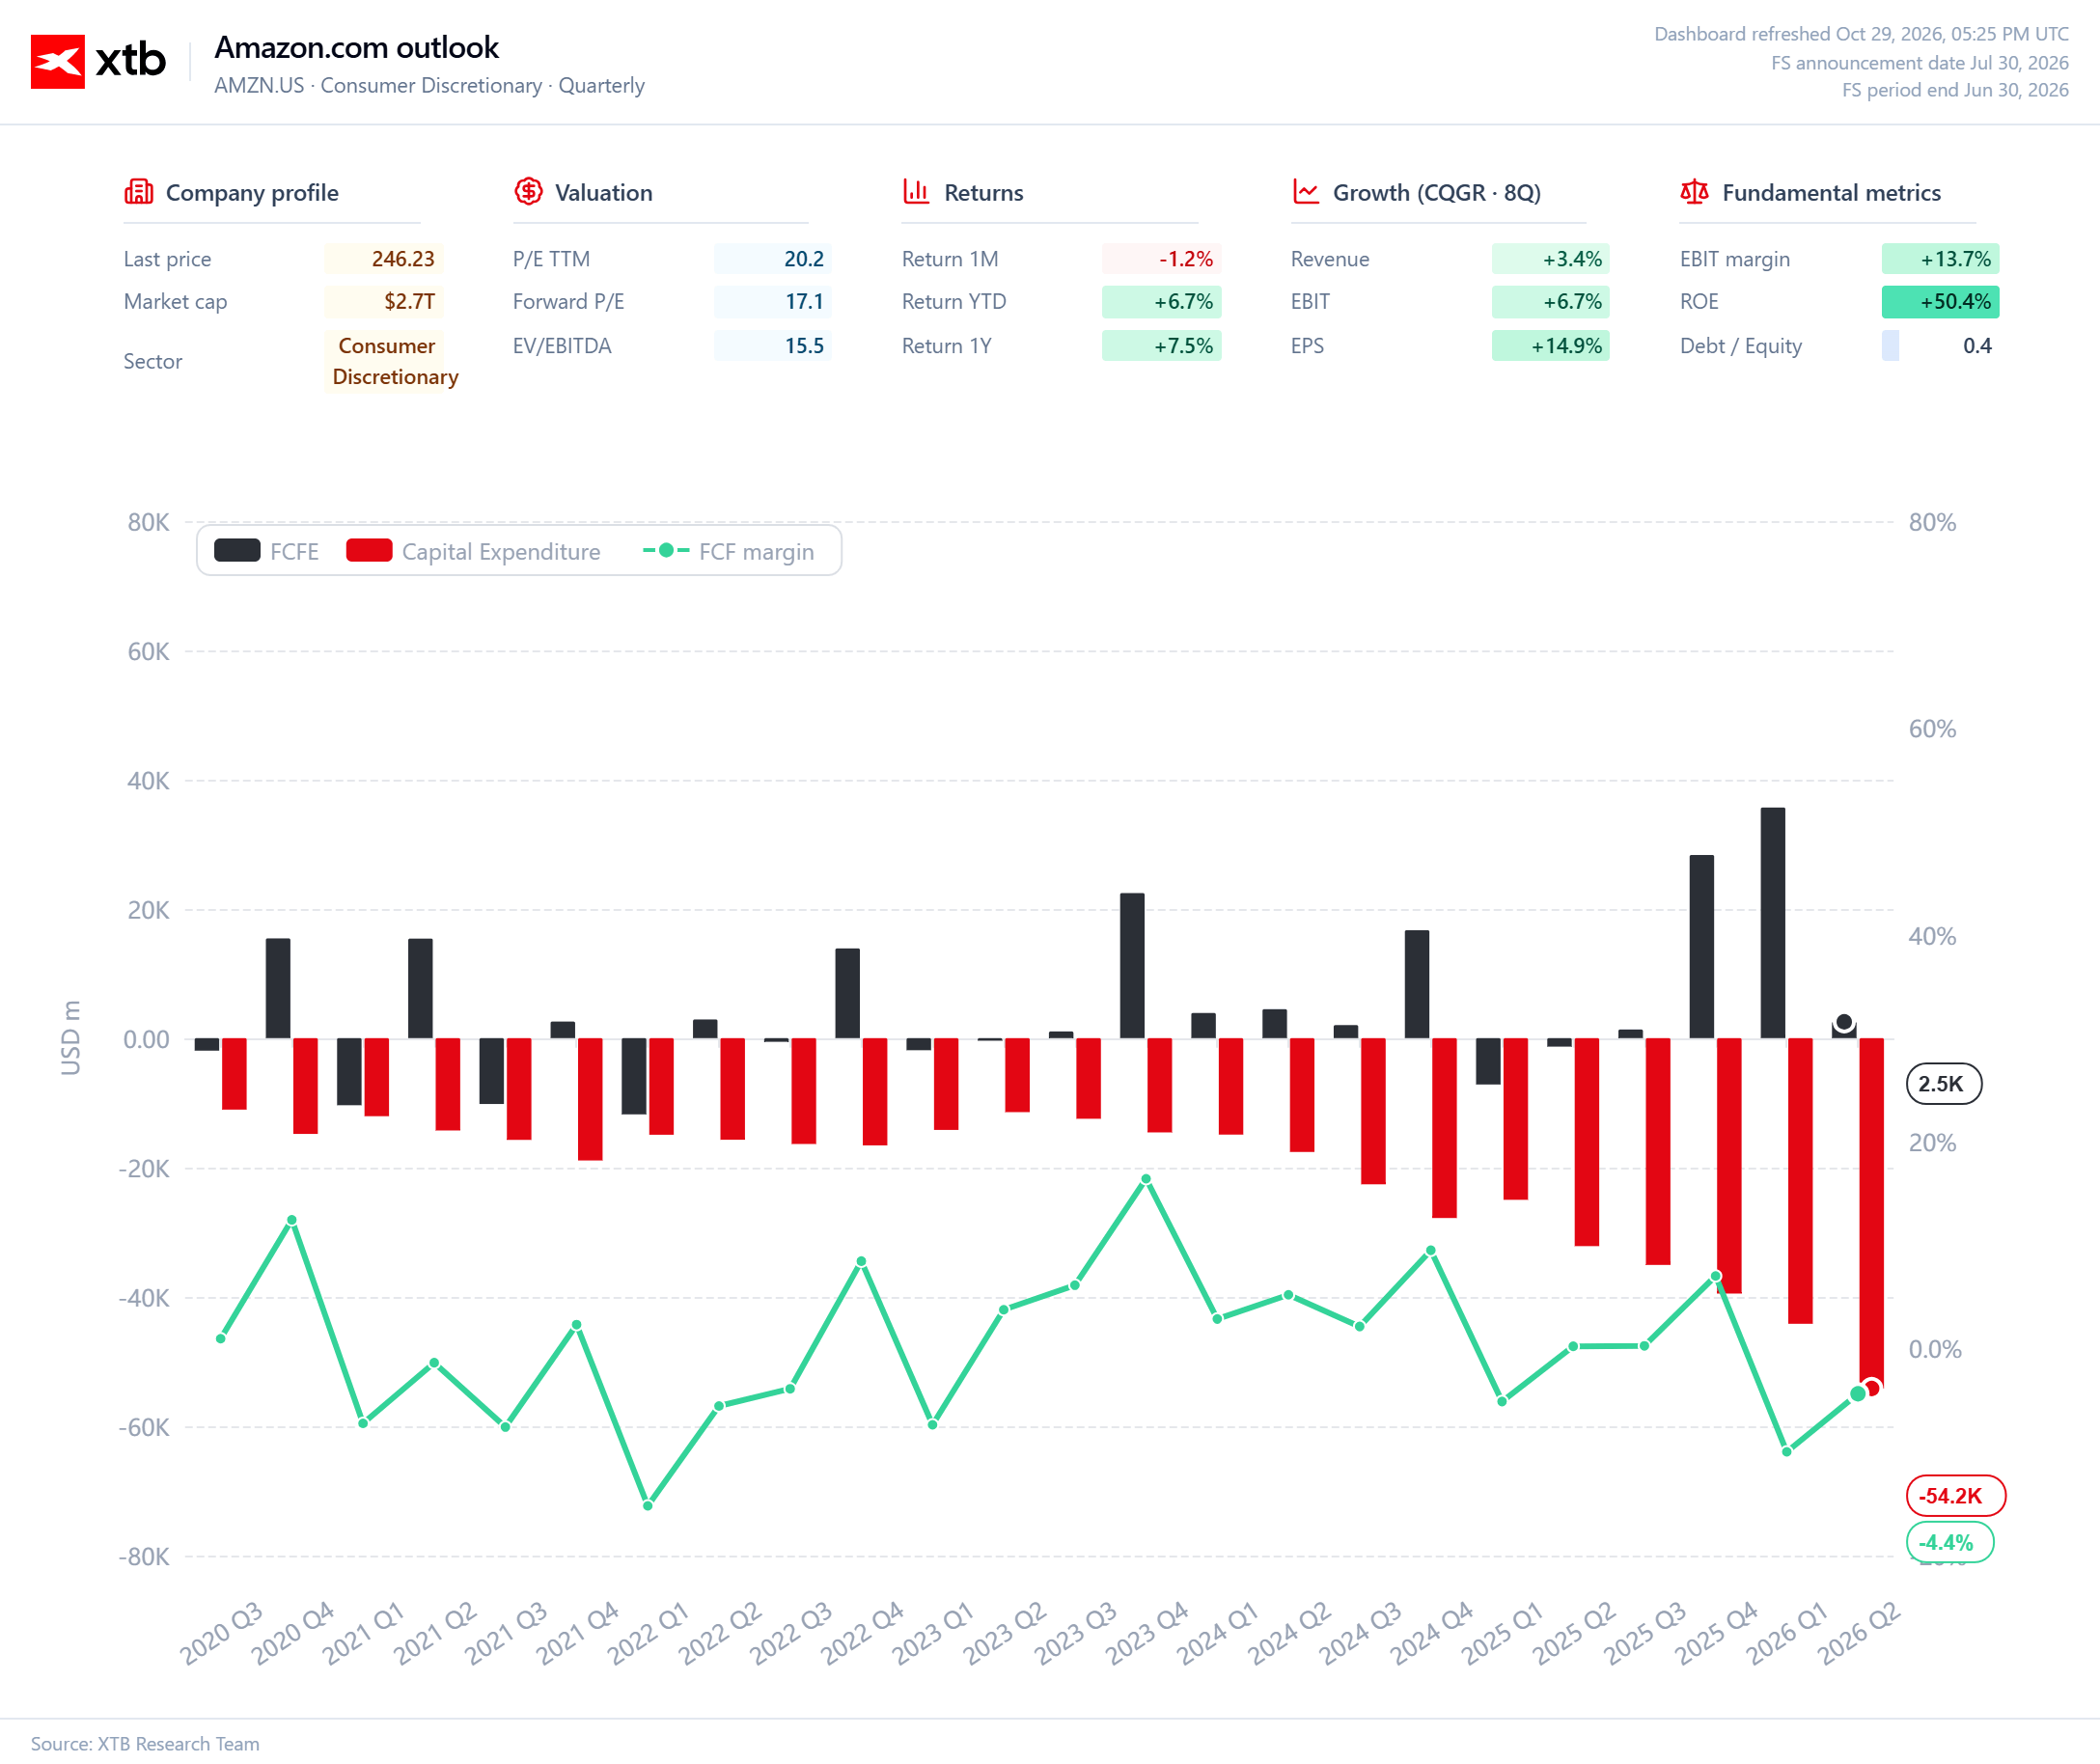
Amazon plans to spend approximately $220 billion on capital expenditure this year, having raised its previous estimate by $20 billion. A substantial portion of this spending is going toward expanding its technology infrastructure, including the data centers needed to meet growing demand for AI. The scale of these investments is so significant that it is becoming increasingly difficult to assess the company solely on the basis of revenue growth. Investors want to know when additional computing capacity will begin translating into correspondingly strong cash flow and earnings.
This is where the biggest risk lies. Capital expenditure may outpace revenue growth for some time, weighing on free cash flow and increasing pressure on profitability. Amazon therefore needs to demonstrate not only that demand for AWS remains strong, but also that its investments are enabling it to monetize that demand. Management’s comments on capital expenditure in 2027 will be equally important. If the next phase of infrastructure expansion requires an even larger budget, the market will expect concrete arguments to justify the decision.
Retail Takes a Back Seat, but Remains on Investors’ Radar
Although investors will focus on the cloud business, retail remains an important part of Amazon’s overall financial picture. Expectations for North America revenue have eased somewhat, while inflationary pressures and tariffs could affect both consumer spending and the company’s margins. Consensus estimates put North American retail operating margin at 6.8%, while profitability forecasts for the third and fourth quarters have been revised downward in recent months.
The market will also be watching the outlook for the fourth quarter, traditionally a critical period for retail because of the holiday shopping season. Amazon needs its core business to remain stable to finance expansion into new areas and limit the impact of high capital expenditure on cash flow. Weakness in retail would not necessarily undermine an otherwise strong earnings report, but combined with disappointing AWS growth, it could significantly change the market’s assessment.
Guidance for the Next Quarter Could Determine the Stock’s Reaction
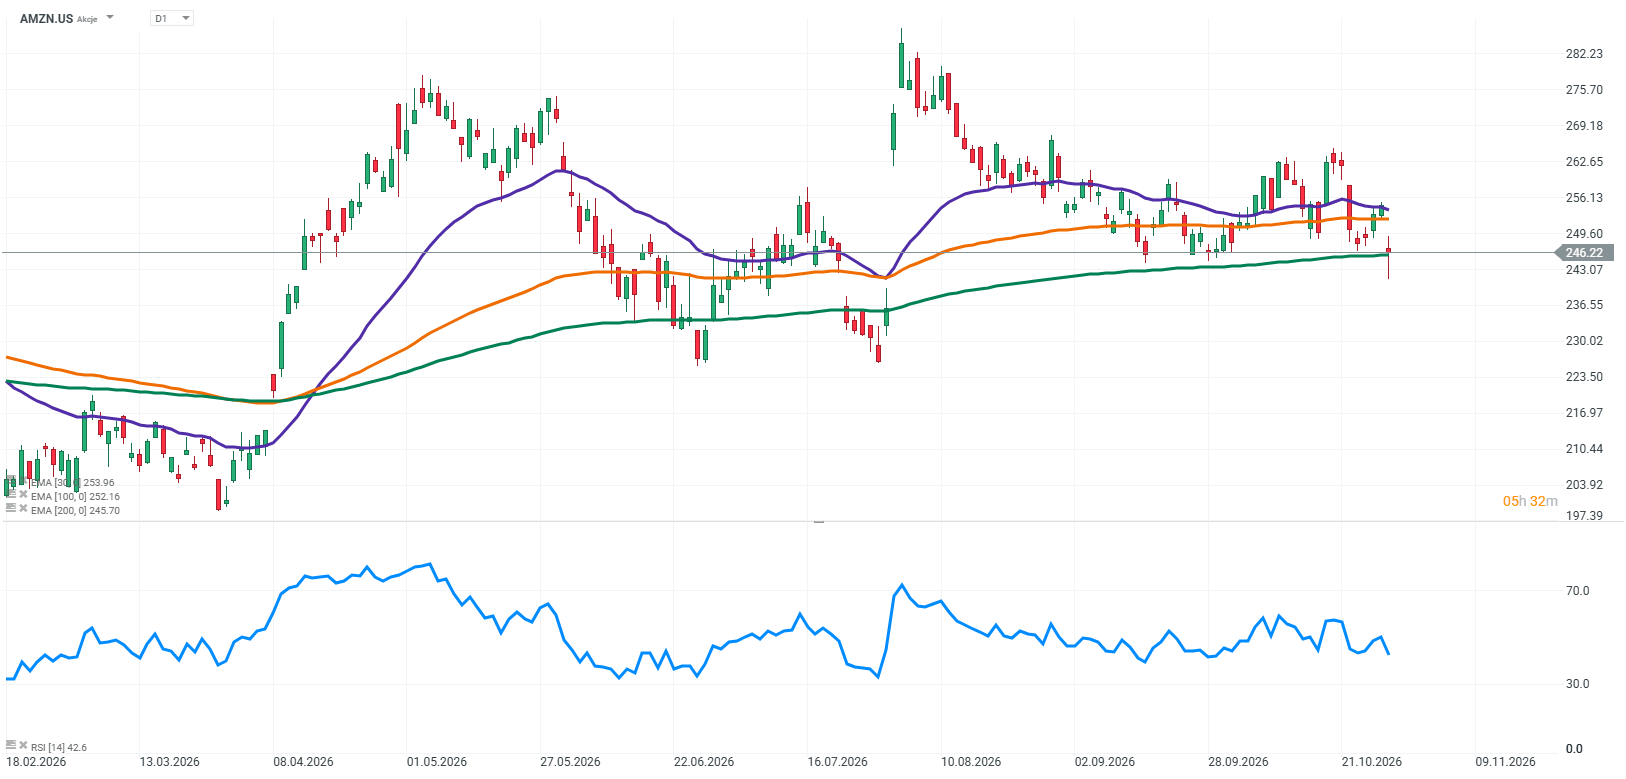
Given current expectations, guidance for the remainder of the year will be just as important as the results for the quarter that has just ended. Investors will want to see whether AWS can sustain its strong growth rate, how management assesses demand for AI services, and whether rising infrastructure costs are beginning to put greater pressure on margins. The company’s position on capital expenditure will also be crucial. Any indication that Amazon needs to spend even more before its investments begin delivering the expected returns could trigger a nervous market reaction.
Options markets suggest that investors are bracing for a significant move in the share price following the earnings release. Derivatives pricing implies a potential move of approximately 8% in either direction. This highlights the high stakes involved and suggests that results merely in line with consensus may not be enough if guidance for the next quarter disappoints.
Amazon Must Prove That the Scale of Its Investments Makes Sense
Amazon is reporting earnings at a time when the market is clearly distinguishing between winners and losers in the race to build AI infrastructure. Microsoft demonstrated that accelerating cloud growth can justify massive investments and prompt a positive investor response. Alphabet, meanwhile, showed how sharply a stock can sell off when an earnings report fails to meet market expectations. Amazon must now demonstrate that it is closer to the first scenario. The key factors will be not only AWS revenue, but also margins, guidance, and the outlook for capital expenditure.
Investors want to see that the billions being spent on AI today will build an even larger business tomorrow. If management fails to make a convincing case, even strong results may not be enough to shield the stock from a negative reaction. After Microsoft won market approval and Alphabet suffered a sharp sell-off, Amazon must show that it can do more than invest on an enormous scale: it must demonstrate that these expenditures can be translated into sustainable business growth and lasting earnings.
Source: XTB Research

Intel Preview: Server CPU Boom Creates Opportunity for Improved Results


ServiceNow Earnings: What Went Wrong?



US Open: Alphabet Sends Nasdaq Plunging. Strong US Data Fails to Rescue Wall Street

Microsoft earnings: Cloud growth overshadows CAPEX & FCF questions
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.