


Caterpillar (CAT.US) shares are down around 5.5%, making the stock the weakest performer in the Dow Jones Industrial Average. The immediate catalyst for the sell-off was a price-target cut by Truist Securities from $1,225 to $1,100, although analysts maintained a Buy rating. The bank pointed to concerns over the durability of spending tied to power generation, data centers and artificial intelligence, as well as the negative impact of high interest rates and rising diesel prices.
Today’s decline, however, follows a very strong rally. Caterpillar shares are still up more than 50% year to date, outperforming the Nasdaq 100 and S&P 500 by nearly three times, which makes the stock more vulnerable to profit-taking and valuation concerns. Investors will now focus mainly on the company’s Q3 earnings, which are expected at the end of October.
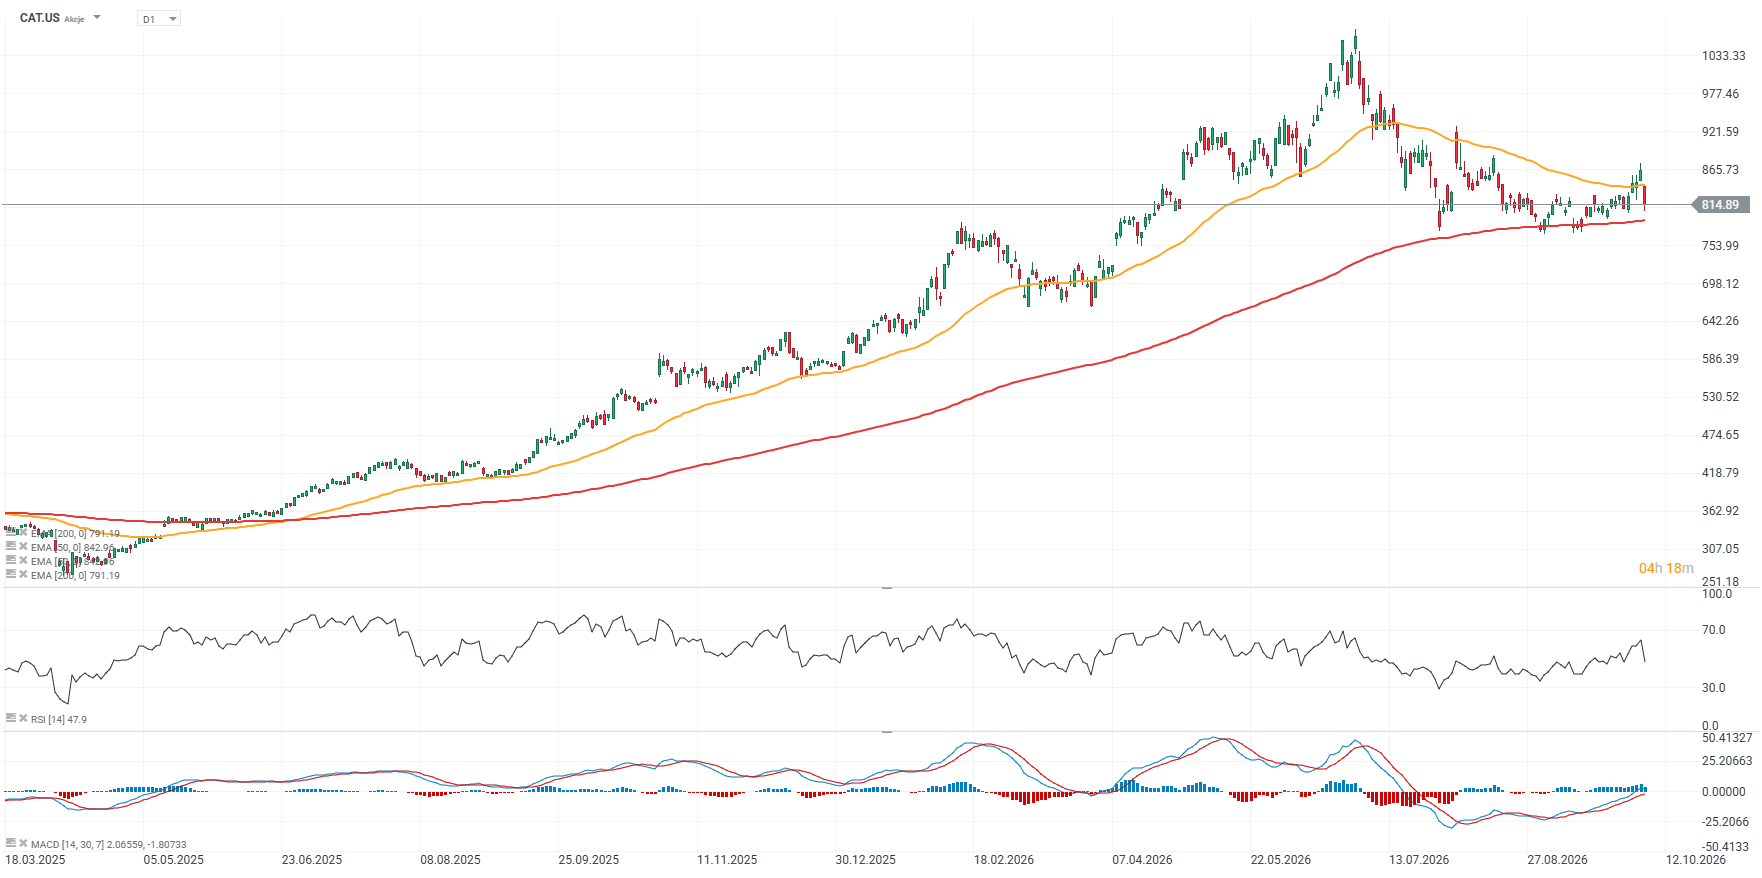
Caterpillar share price chart (D1 timeframe)
Investors increasingly view Caterpillar as one of the major beneficiaries of AI-related capital spending, with meaningful exposure to data-center construction. The shares have fallen by around 30% from their local peak and are now trading close to the 200-day exponential moving average, EMA200 (red line). Caterpillar is scheduled to report earnings on October 29 after the US market close. The market is no longer valuing the company like a typical cyclical industrial manufacturer, but rather as a business expected to deliver sustained growth from power generation, infrastructure and data-center investment.
 Source: xStation5
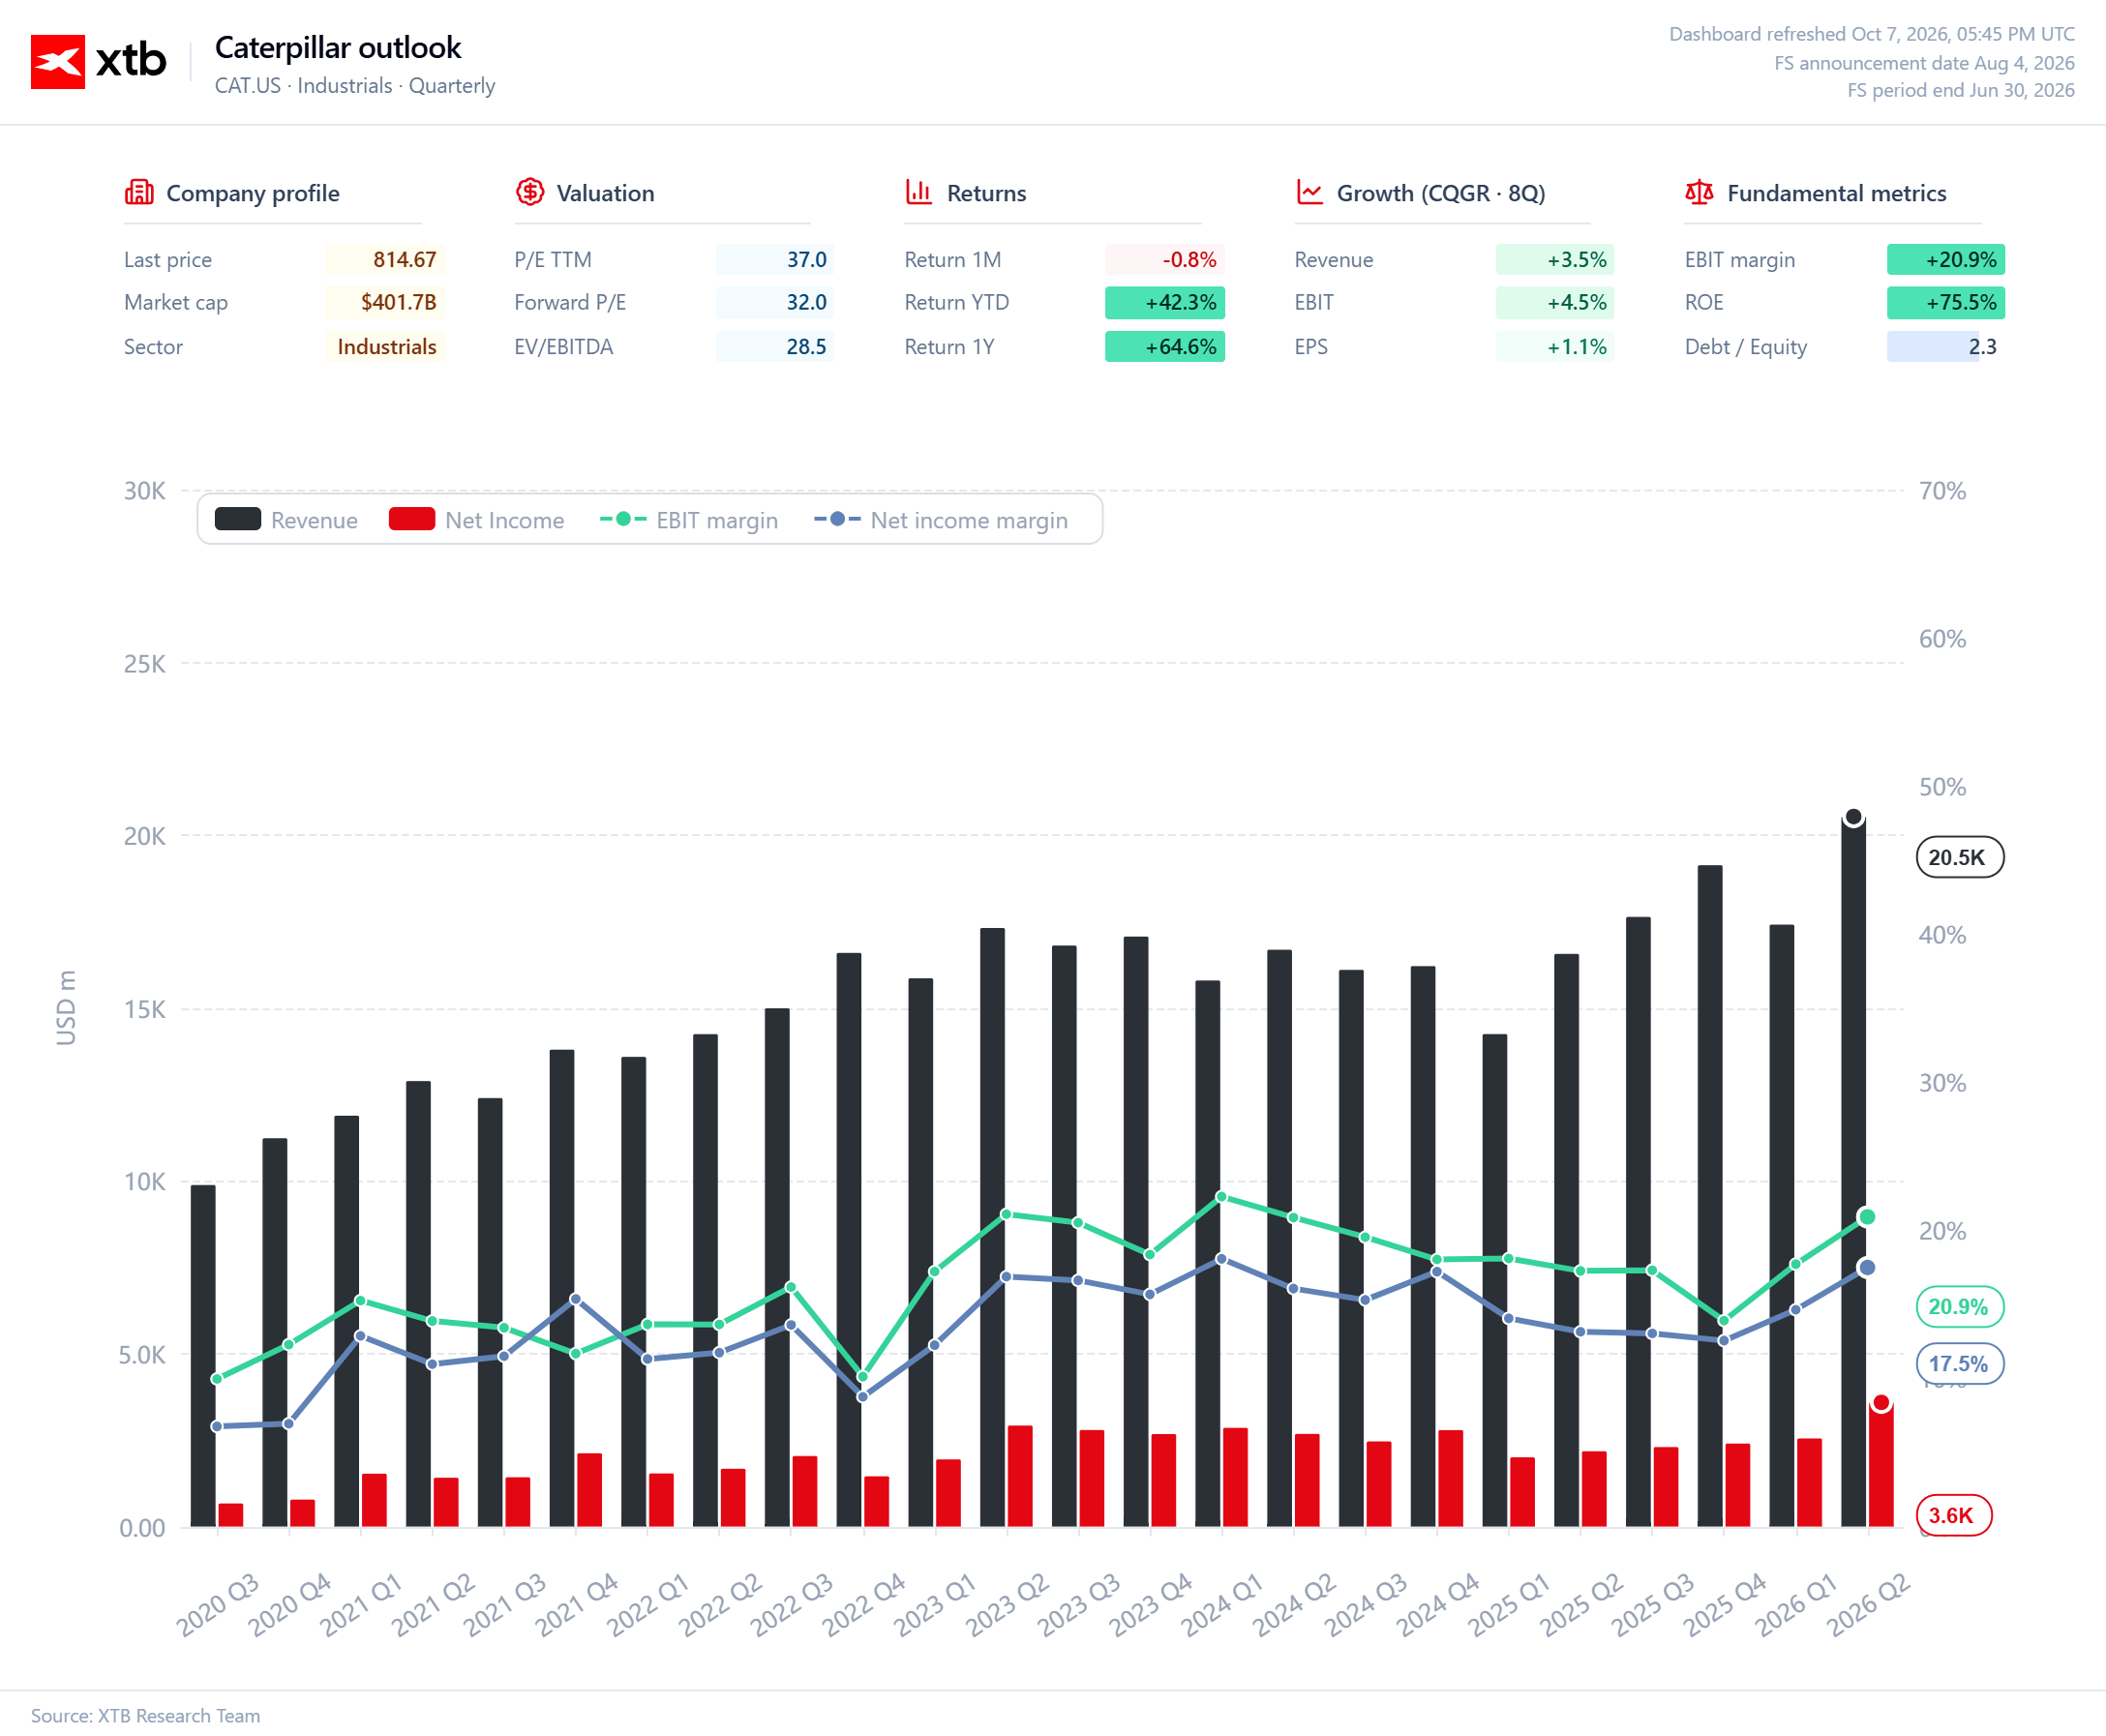
From a valuation perspective, Caterpillar is a classic example of a company whose strong share-price performance appears to have moved ahead of the pace of fundamental improvement. The stock has gained around 42% year to date and nearly 65% over the past 12 months, while average growth over the last eight quarters stands at roughly 3.5% for revenue, 4.5% for EBIT and just 1.1% for EPS. With a trailing P/E of 37 and a forward P/E of around 32, the market is paying a substantial premium for further earnings improvement and the continuation of a strong investment cycle. On the other hand, the company continues to show strong operating quality, with an EBIT margin of around 20.9% and ROE of 75.5%, pointing to very high profitability on equity.
It is worth noting, however, that such a high ROE coincides with a relatively elevated level of leverage, with Debt/Equity at 2.3, meaning that not all of the return on equity comes purely from improvements in the underlying operating business. The biggest valuation risk today is therefore not weakness in Caterpillar itself, but overly optimistic market expectations: if revenue and earnings growth remain in the single digits, current valuation multiples may prove difficult to sustain. At the same time, record revenue and net income shown on the chart suggest that the underlying fundamental trend remains positive, so the key question is whether Caterpillar can convert strong demand from infrastructure, power generation and data centers into sustained free cash flow growth. In the current setup, the company looks more like a high-quality business priced for continued near-perfect execution than a traditional value opportunity.
 Source: XTB Research

Webull shares down 20% amid fears over potential China ties


US Open: Wall Street in the Red 🚩 Nasdaq Falls 1% From Record Highs, Constellation Brands Back at March 2020 Level



Market Wrap: Oil rises again, French fiscal concerns weigh on euro (07.10.2026)


US Open: Wall Street Pushes Back Expectations of Another Fed Hike
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.