


- Norges Bank kept its main interest rate unchanged at 4.5%.
- Governor Ida Wolden Bache stated that inflation remains too high.
- Interest rates are expected to stay elevated for an extended period.

- Norges Bank kept its main interest rate unchanged at 4.5%.
- Governor Ida Wolden Bache stated that inflation remains too high.
- Interest rates are expected to stay elevated for an extended period.
Norges Bank kept its main interest rate unchanged at 4.5% today, which was clearly expected by the market. Swaps prior to the decision were pricing in only about a 4% chance of a rate hike. This was an interim meeting, so the bank did not publish new projections or a rate path.
However, the message remained hawkish, which also aligns with the sentiment presented by Riksbank, which hiked rates yesterday and will be catching up with Norges Bank's decision.
Governor Ida Wolden Bache stated that "inflation is too high" and that interest rates will likely need to be kept at an elevated level for some time. She added that the bank is ready to raise them if necessary. According to policymakers, restrictive monetary policy is still necessary to bring inflation down to the 2% target within a reasonable time horizon.
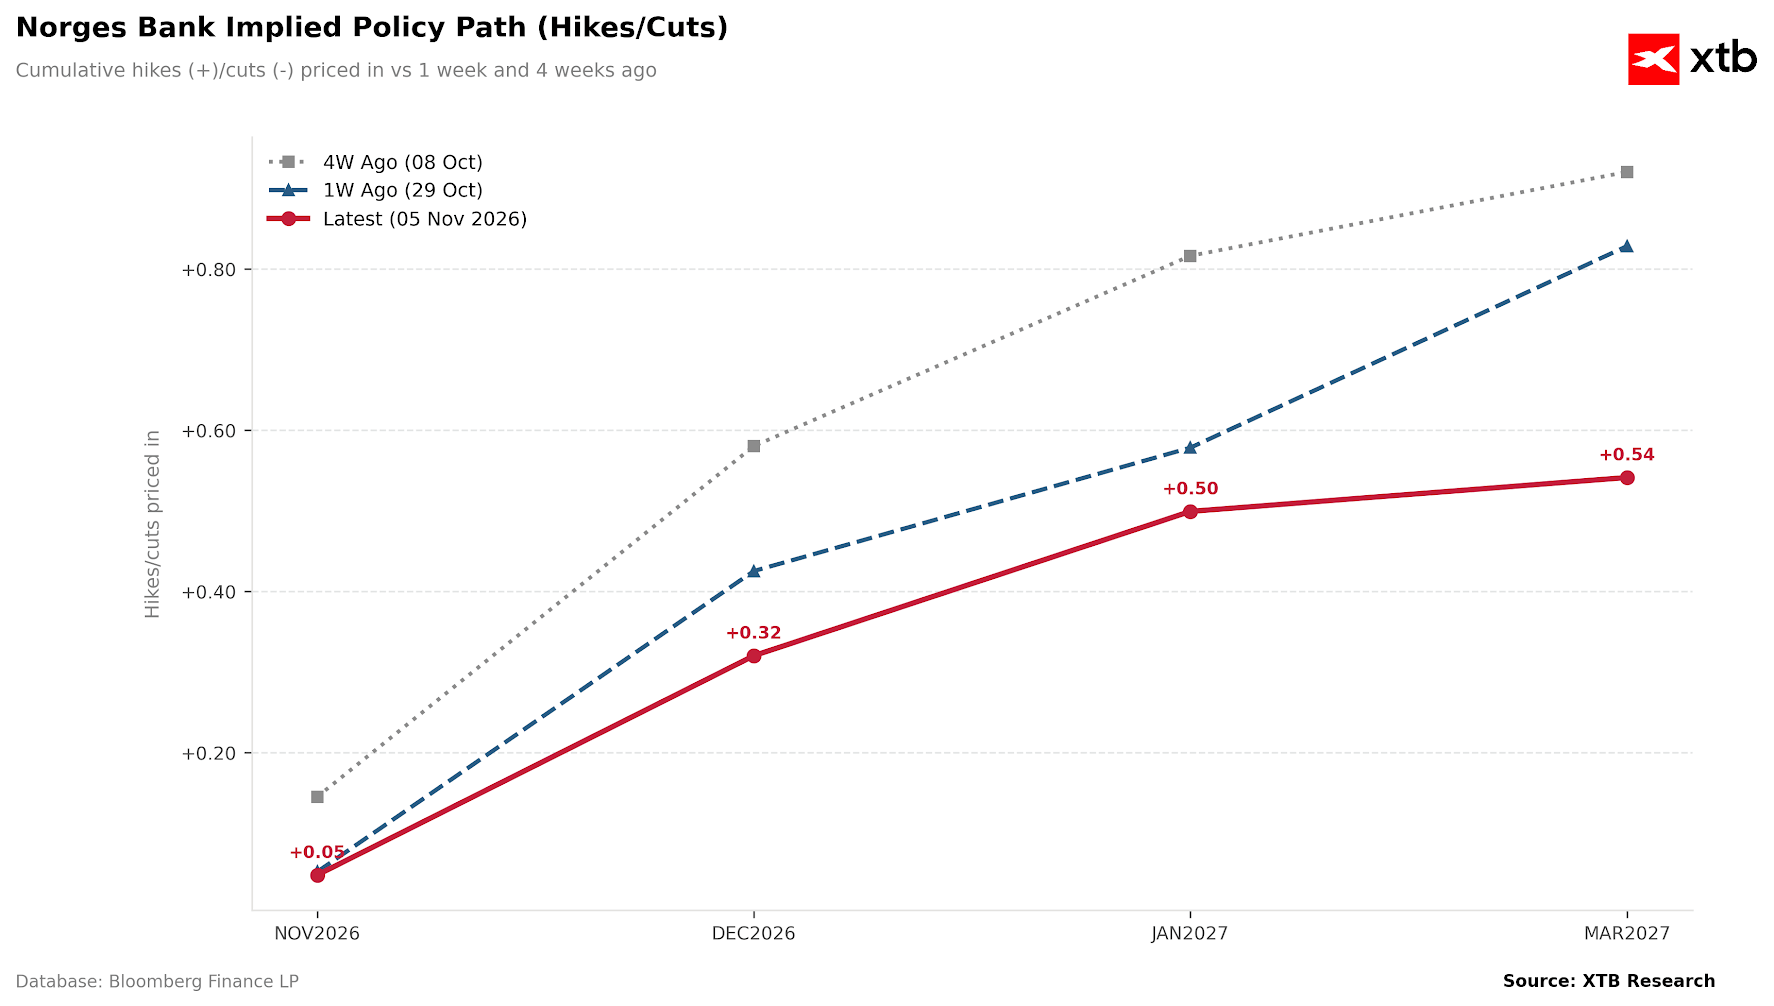 Just a month ago, expectations for another rate hike in March were very high. Currently, they have dropped to around 50%. Source: Bloomberg Finance LP, XTB
Inflation in Norway for September remains elevated at 3.4%, but the trend remains sideways when looking at recent years. The inflation peak was reached in 2022 above 7%.
Norges Bank has already raised rates by a total of 50 bps this year, most recently by 25 bps in September. Core inflation has remained around 3% for about two years, and unemployment is near multi-year lows. On the other hand, the bank noted that the krone has strengthened and is stronger than assumed. The exchange rate against the euro is at its highest level in four years, which limits the risk of imported inflation, while the economy is slowing under the impact of higher borrowing costs. This may mean that further rate hikes are by no means certain, especially as crude oil prices drop, which could also weigh negatively on the entire Norwegian economy.
Before the decision, the market was pricing in about 9 bps of rate hikes in December, compared to 16 bps a week earlier. Most economists believe that 4.5% is the peak of the cycle and expect the first rate cut in Q4 2027. Nordea is more cautious and sees no signs of cuts before 2028. However, if greater pressure on oil and gas prices emerges, potential interest rate cuts could arrive in the second half of 2027.
Norway stands out compared to other central banks. The Bank of Sweden and the Reserve Bank of Australia raised interest rates this week, while Norges Bank decided only to maintain readiness for action.
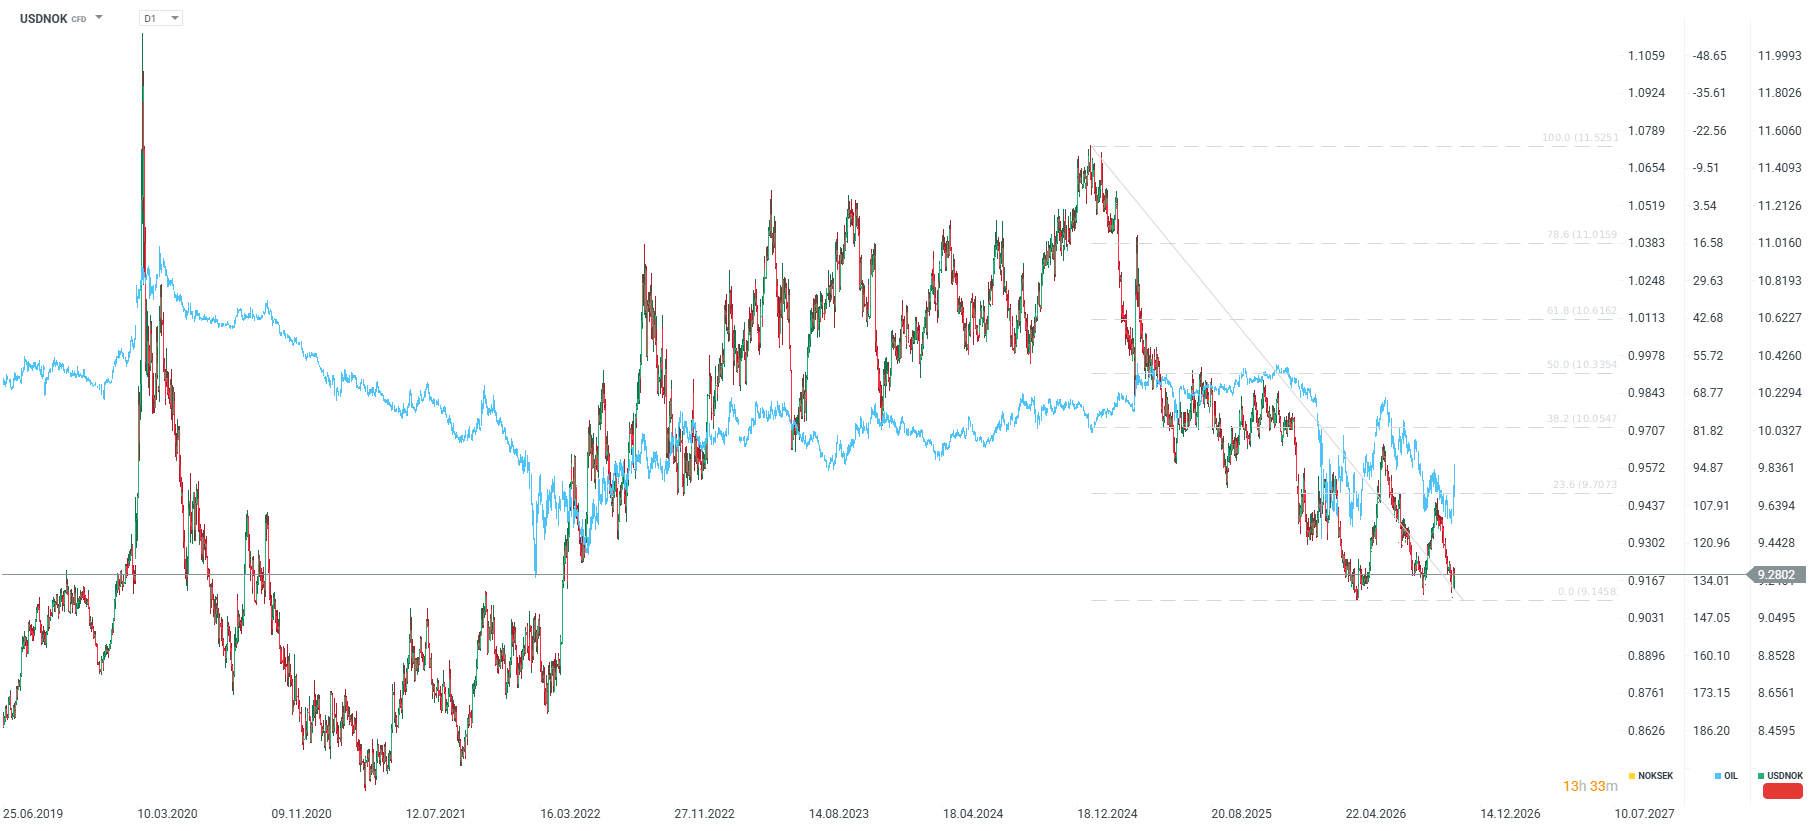 Since the beginning of 2026, the correlation between the NOK and crude oil has been very strong, while the monetary effect was visible primarily after 2024. Nevertheless, it can currently be expected that we may have already reached the peak in interest rates, whereas hikes could still take place in the EMU and the US, and additionally, falling oil prices could act to the disadvantage of the NOK. Technically, it is also visible that the area around 9.2 constitutes a very important support level. A fall in crude oil prices towards $80 could lead to a rebound in USDNOK towards 9.60.


Daily Summary: Blue Wave in Congress Triggers Market Euphoria, Oil Plunges

🛢️Oil suffers sharpest fall since April (-9%)
BREAKING: US oil inventories fall less than expected, but prices drop due to elections and hopes for a US-Iran deal


US OPEN: Blue Wave in Congress Triggers Massive Wall Street Rally, Dow Gains Over 1,000 Points
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.