


- Saudi crude loadings from ports on the Persian Gulf rose sharply over the weekend, while the number of vessels at the country’s main export port climbed to its highest level since June.
- Fresh developments in the AI sector are reinforcing expectations for continued investment and stronger semiconductor demand. The MSCI All Country World Index is rising for a fourth consecutive session, reaching its highest level in two weeks.
- Samsung and SK Hynix shares extended gains in Asia, while sentiment was additionally supported by news of Alibaba’s new AI chip, designed to compete with Nvidia’s solutions, as well as the launch of Tencent’s latest image-generation model.
- Brent crude is attempting to snap a four-session losing streak, however. The OIL contract is up more than 1% today and has moved back above $100 per barrel.
S&P 500 earnings outlook remains strong for Q3
Expectations for S&P 500 earnings have improved noticeably over the course of the third quarter. Consensus currently points to year-over-year earnings growth of 28.9%, up from 26.7% expected at the end of June. If the estimate is confirmed, this would mark the third consecutive quarter of earnings growth above 25% and the eighth straight quarter of double-digit growth. Wall Street is expecting a very strong earnings season, which, if results exceed expectations, could become an important driver of further gains.
One particularly notable development is that analysts have raised earnings estimates by 1.6% during the quarter, whereas historically estimates tend to be revised lower over this period. Over the past five years, earnings expectations have declined by an average of around 2.2% during the quarter, while the average decline over the past decade has been around 2.5%. At the same time, 72 S&P 500 companies have issued positive EPS guidance for Q3, compared with 43 companies issuing negative guidance, also representing a strong reading relative to historical averages.
Earnings growth is expected across all 11 sectors of the index, with five projected to post double-digit growth. Energy, Information Technology, Communication Services and Materials are expected to lead the way. Revenue forecasts have also been revised higher: the market now expects year-over-year revenue growth of 11.9%, compared with 10.9% at the end of June. The S&P 500 forward P/E ratio stands at around 19.1, slightly below its five-year average of 19.8 and roughly in line with its 10-year average.
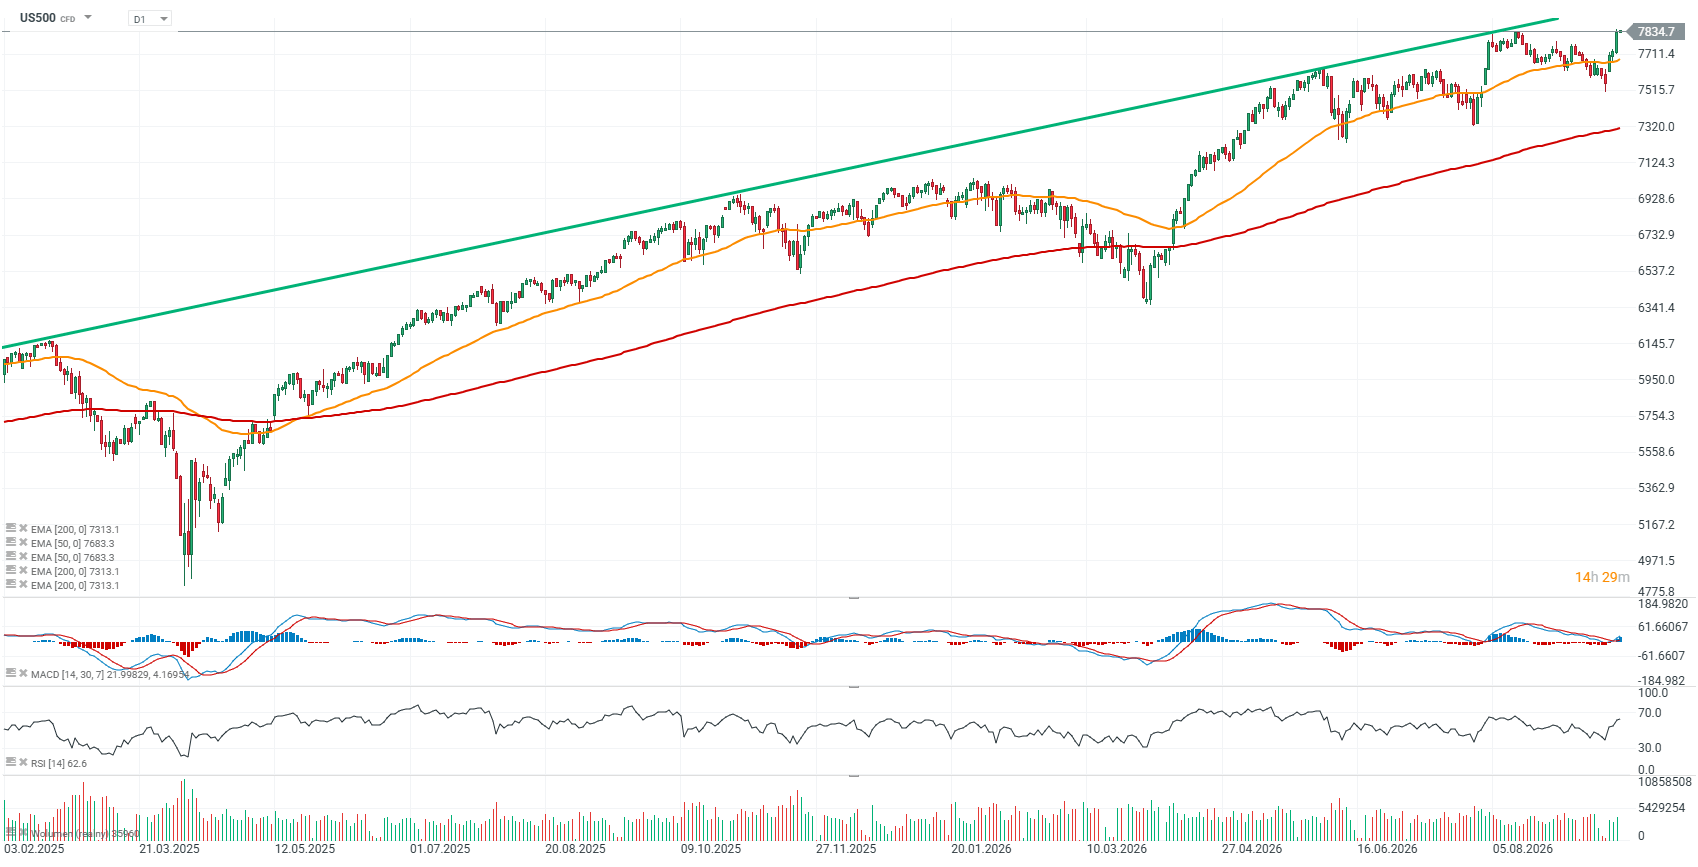
US500 chart (D1 interval)
The S&P 500 futures chart continues to favor buyers, with the index forming a sequence of higher lows and trading near 7,830 points, around the level of the previous peak from June 17. If the breakout continues, the contract could move toward the first major psychological resistance level at 8,000 points. In a bearish scenario, however, an unfavorable technical “double top” formation could begin to emerge. An important support zone appears to be around 7,500–7,600 points, where previous price reactions and the EMA50 moving average (orange line) are located.
Source: xStation5



Chart of the Day: Record session for US100 behind us (with a small asterisk)


Economic Calendar - Another day of central bankers' speeches. Is AUDUSD responding to inflation risks?


Morning Briefing: Global Markets Riding AI Wave, Rising Geopolitical Tensions, and Hawkish Central Banks (22.09.2026)
Daily Summary: Optimism returns, chips rise, oil falls.
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.