


We begin the week in the markets under the influence of a familiar pattern: the lack of a breakthrough in US-Iran talks is pushing crude oil prices higher. This amplifies inflation concerns, increases bets on further Federal Reserve interest rate hikes, and drives up Treasury yields. The latter have reached their highest levels since 2007 today, pulling down both equities and gold.
Debt Market
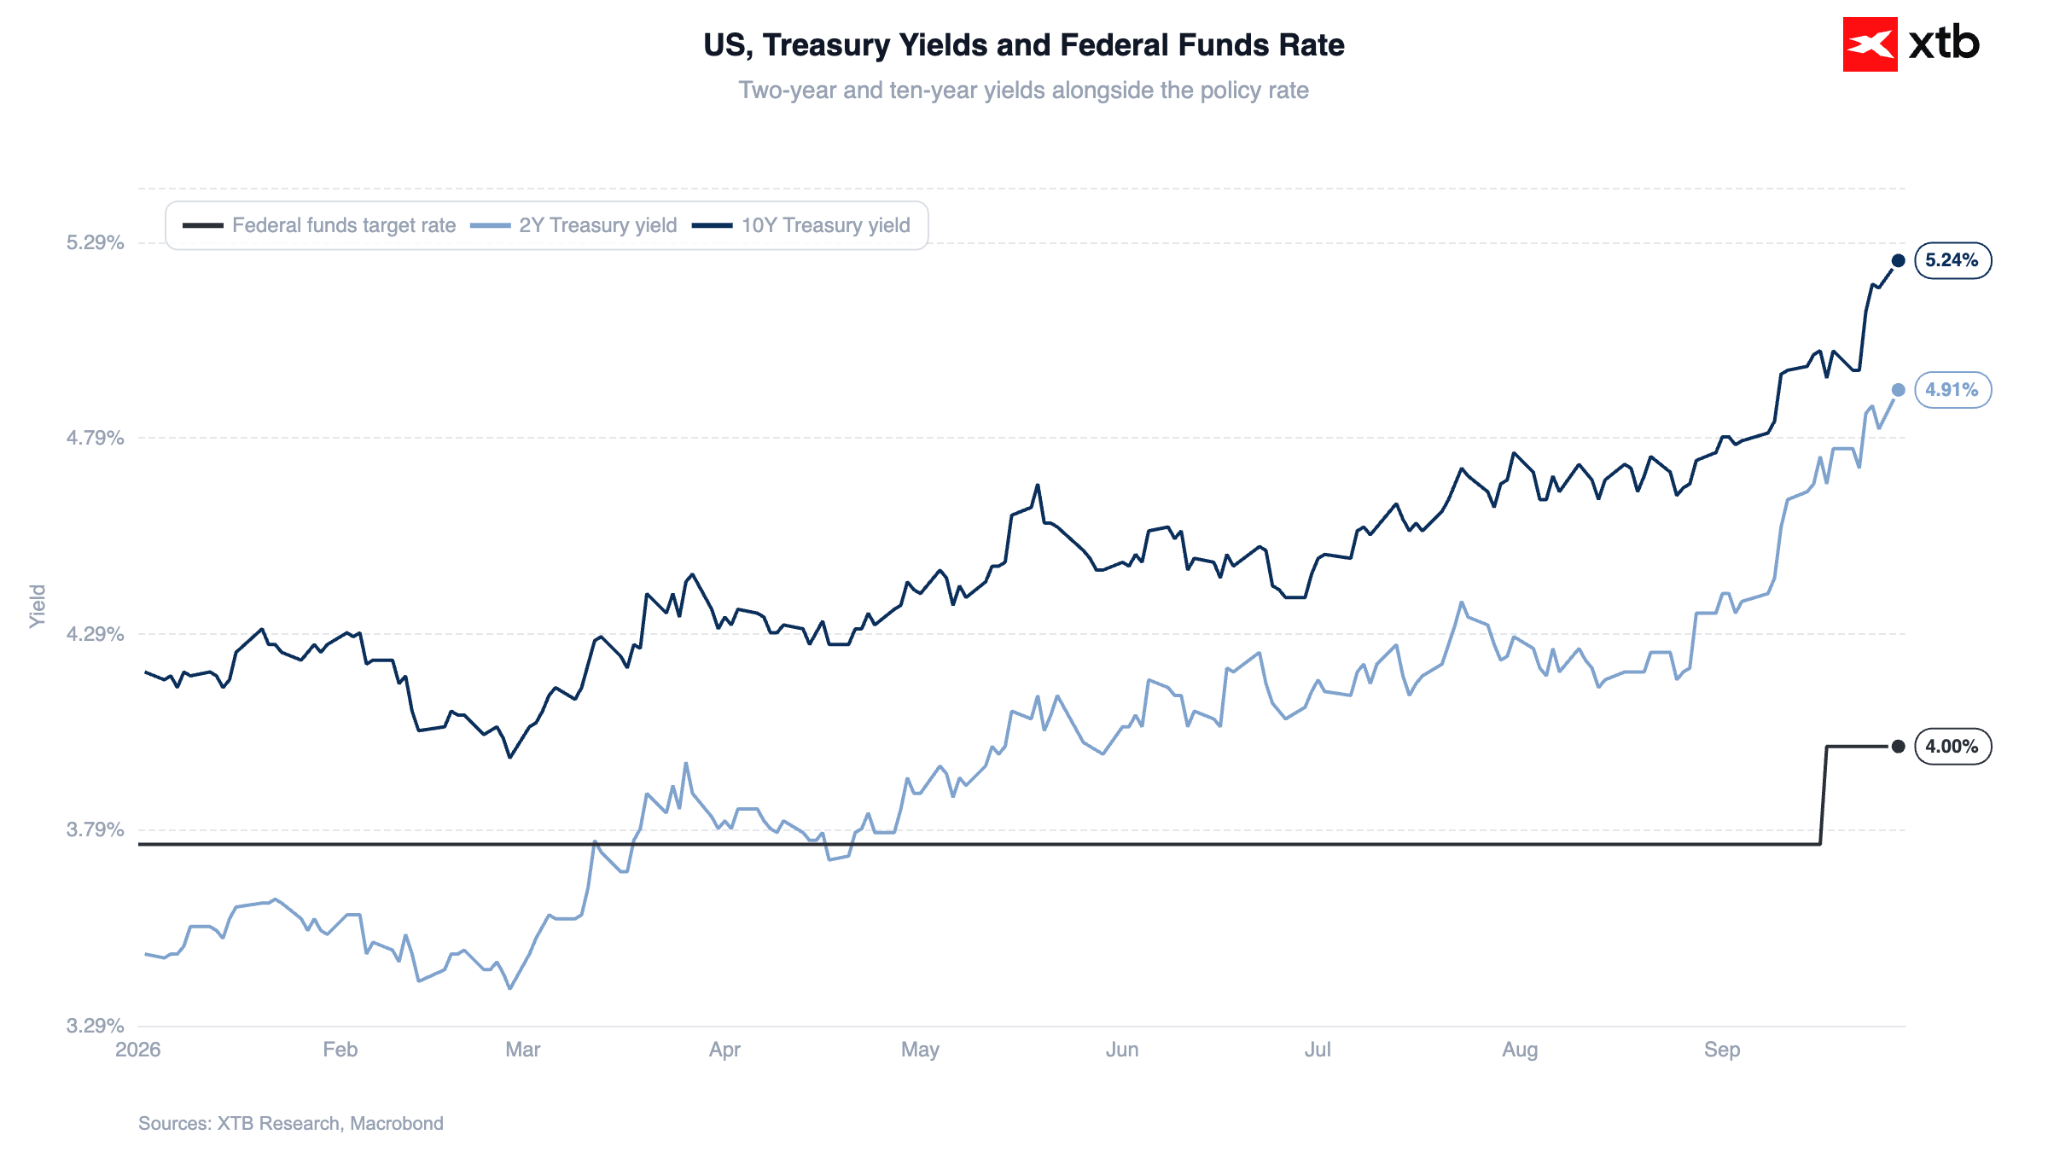
The yield on US 10-year Treasury bonds is up several basis points today, briefly touching 5.28%, its highest level since 2007. The 30-year yield rose to 5.58%, the highest since 2004. All US Treasuries with maturities exceeding two years are currently trading above 5%.
Figure 1: US Treasury Yields and Federal Funds Rate (2026)
 Source: XTB Research, 28.09.2026
It is worth noting the broader trend in real yields (adjusted for inflation expectations); those for 10-year bonds rose to 2.9% today. Since the beginning of the year, the increase stands at nearly 100 bps, with almost half of that movement occurring in September alone.
Energy Commodities
Hopes for a swift agreement, which buoyed the market last week, have visibly faded today. The parties appear far apart regarding both a ceasefire and the reopening of the shipping route. Iranian Foreign Minister Abbas Araghchi is scheduled to meet mediators in New York today (without the participation of a US representative). Tehran maintains its commitment to the proposal concerning the opening of the Strait of Hormuz, which Donald Trump rejected last week. Trump himself is reportedly prepared to offer Iran sanction relief and unfreeze funds in exchange for "concrete progress" on the nuclear issue.
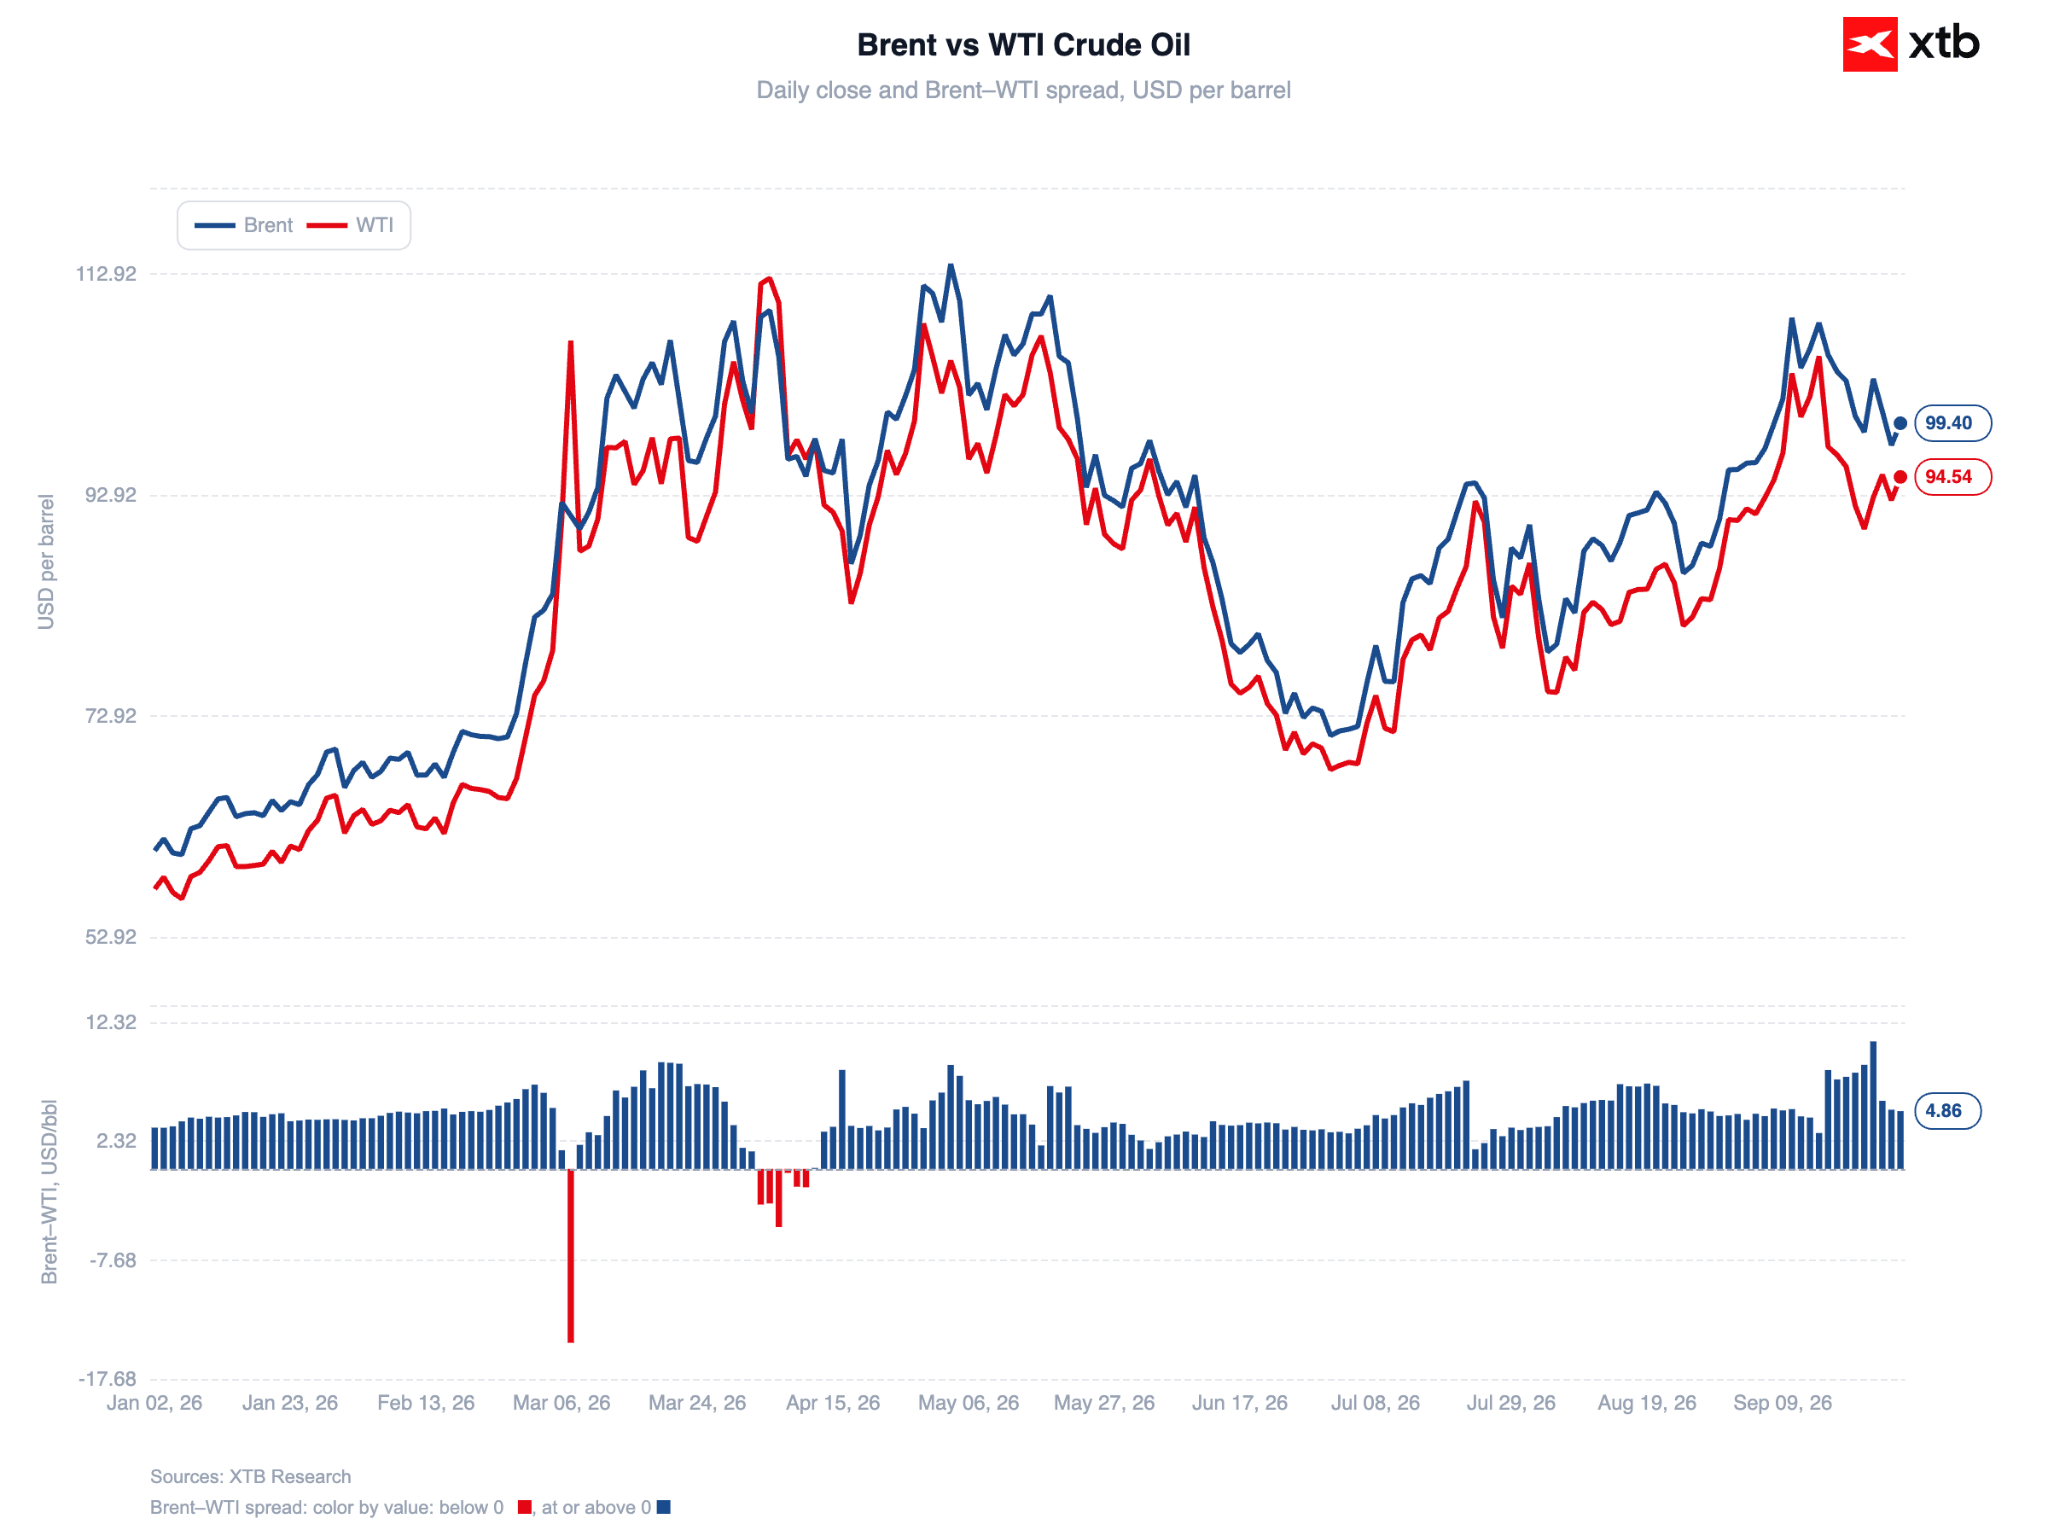
At its peak today, Brent crude reached approximately $101 per barrel. Prices are currently hovering around $98.
Figure 2: Brent and WTI Crude Oil (2026)
 Source: XTB Research, 28.09.2026
An evening retreat in prices was supported by positive supply updates. Saudi Arabia resumed oil exports via the East-West pipeline following repairs to damage caused by drone attacks on 10 September. This involves approximately 3.5 million barrels per day out of a throughput capacity of around 7 million (typically around 5 million is exported, with 2 million supplying local refineries). Restoring full capacity is expected to take another six weeks or so. By utilizing the route via Hormuz, total oil exports from Saudi Arabia reached a war-time record of over 5 million barrels per day in September, primarily bound for Asia.
However, the kingdom's western coast remains threatened by Houthi attacks, which intensified this month targeting energy infrastructure, including the port of Yanbu at the terminus of the pipeline.
Stock Market
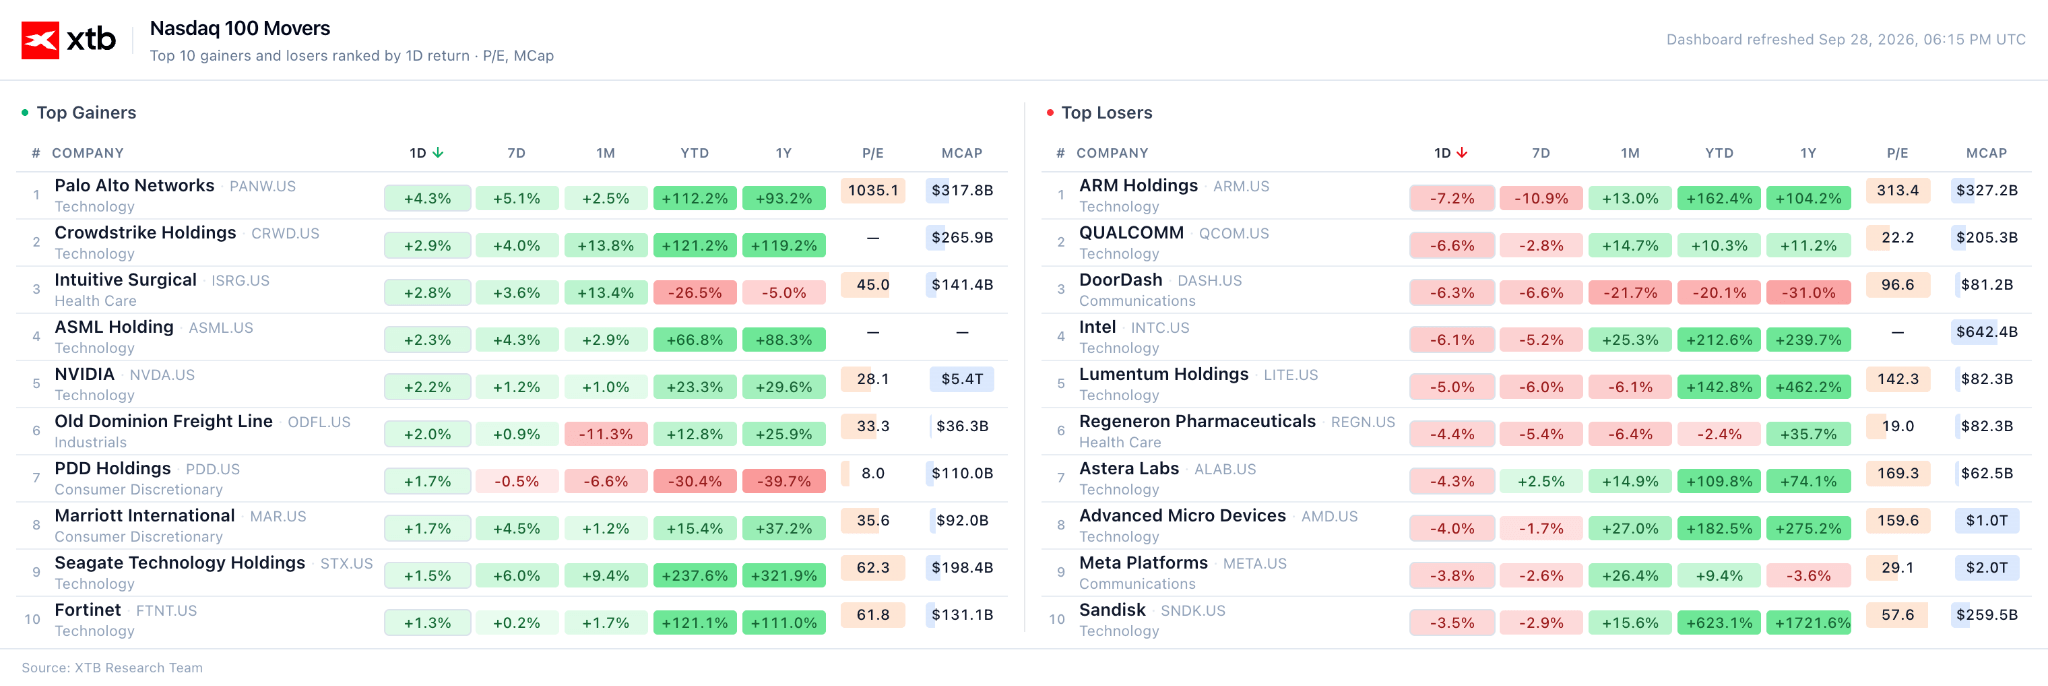
US indices are trading in the red today. The Nasdaq 100 is down 0.8%, while the S&P 500 and the Dow Jones have each lost 0.5%.
Figure 3: Gainers and Losers in Nasdaq 100 (28.09.2026)
 Source: XTB Research, 28.09.2026
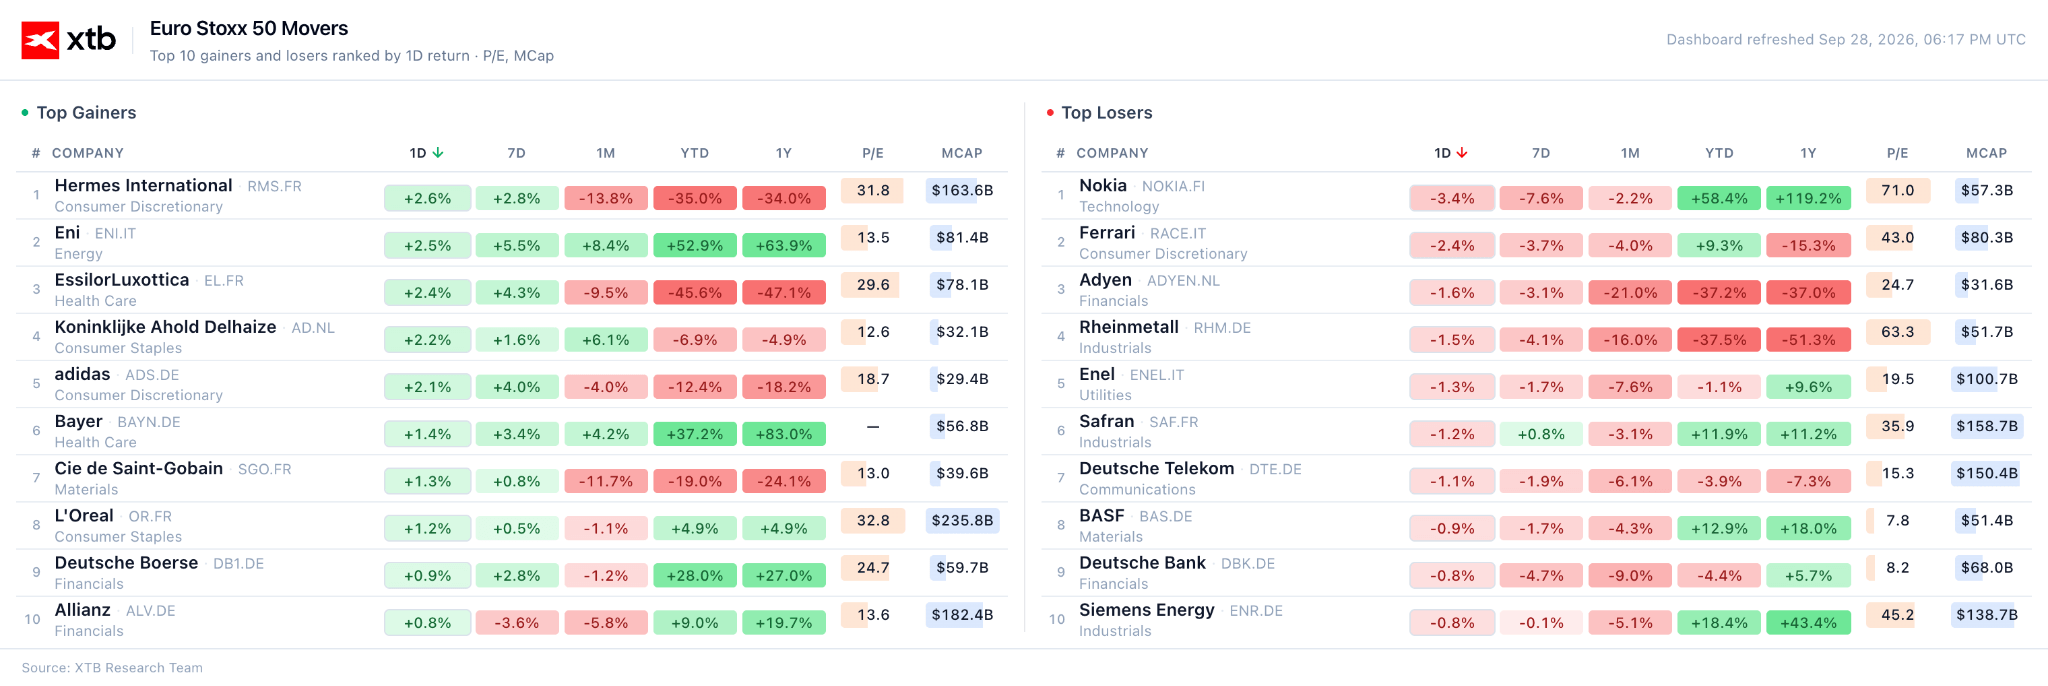
Europe saw greater calm today, with most indices trading close to Friday's closing levels. The German DAX lost 0.1%, while the pan-European Euro Stoxx 50, French CAC 40, and British FTSE 100 remained virtually flat.
Figure 4: Gainers and Losers in Euro Stoxx 50 (28.09.2026)
 Source: XTB Research, 28.09.2026
Precious Metals
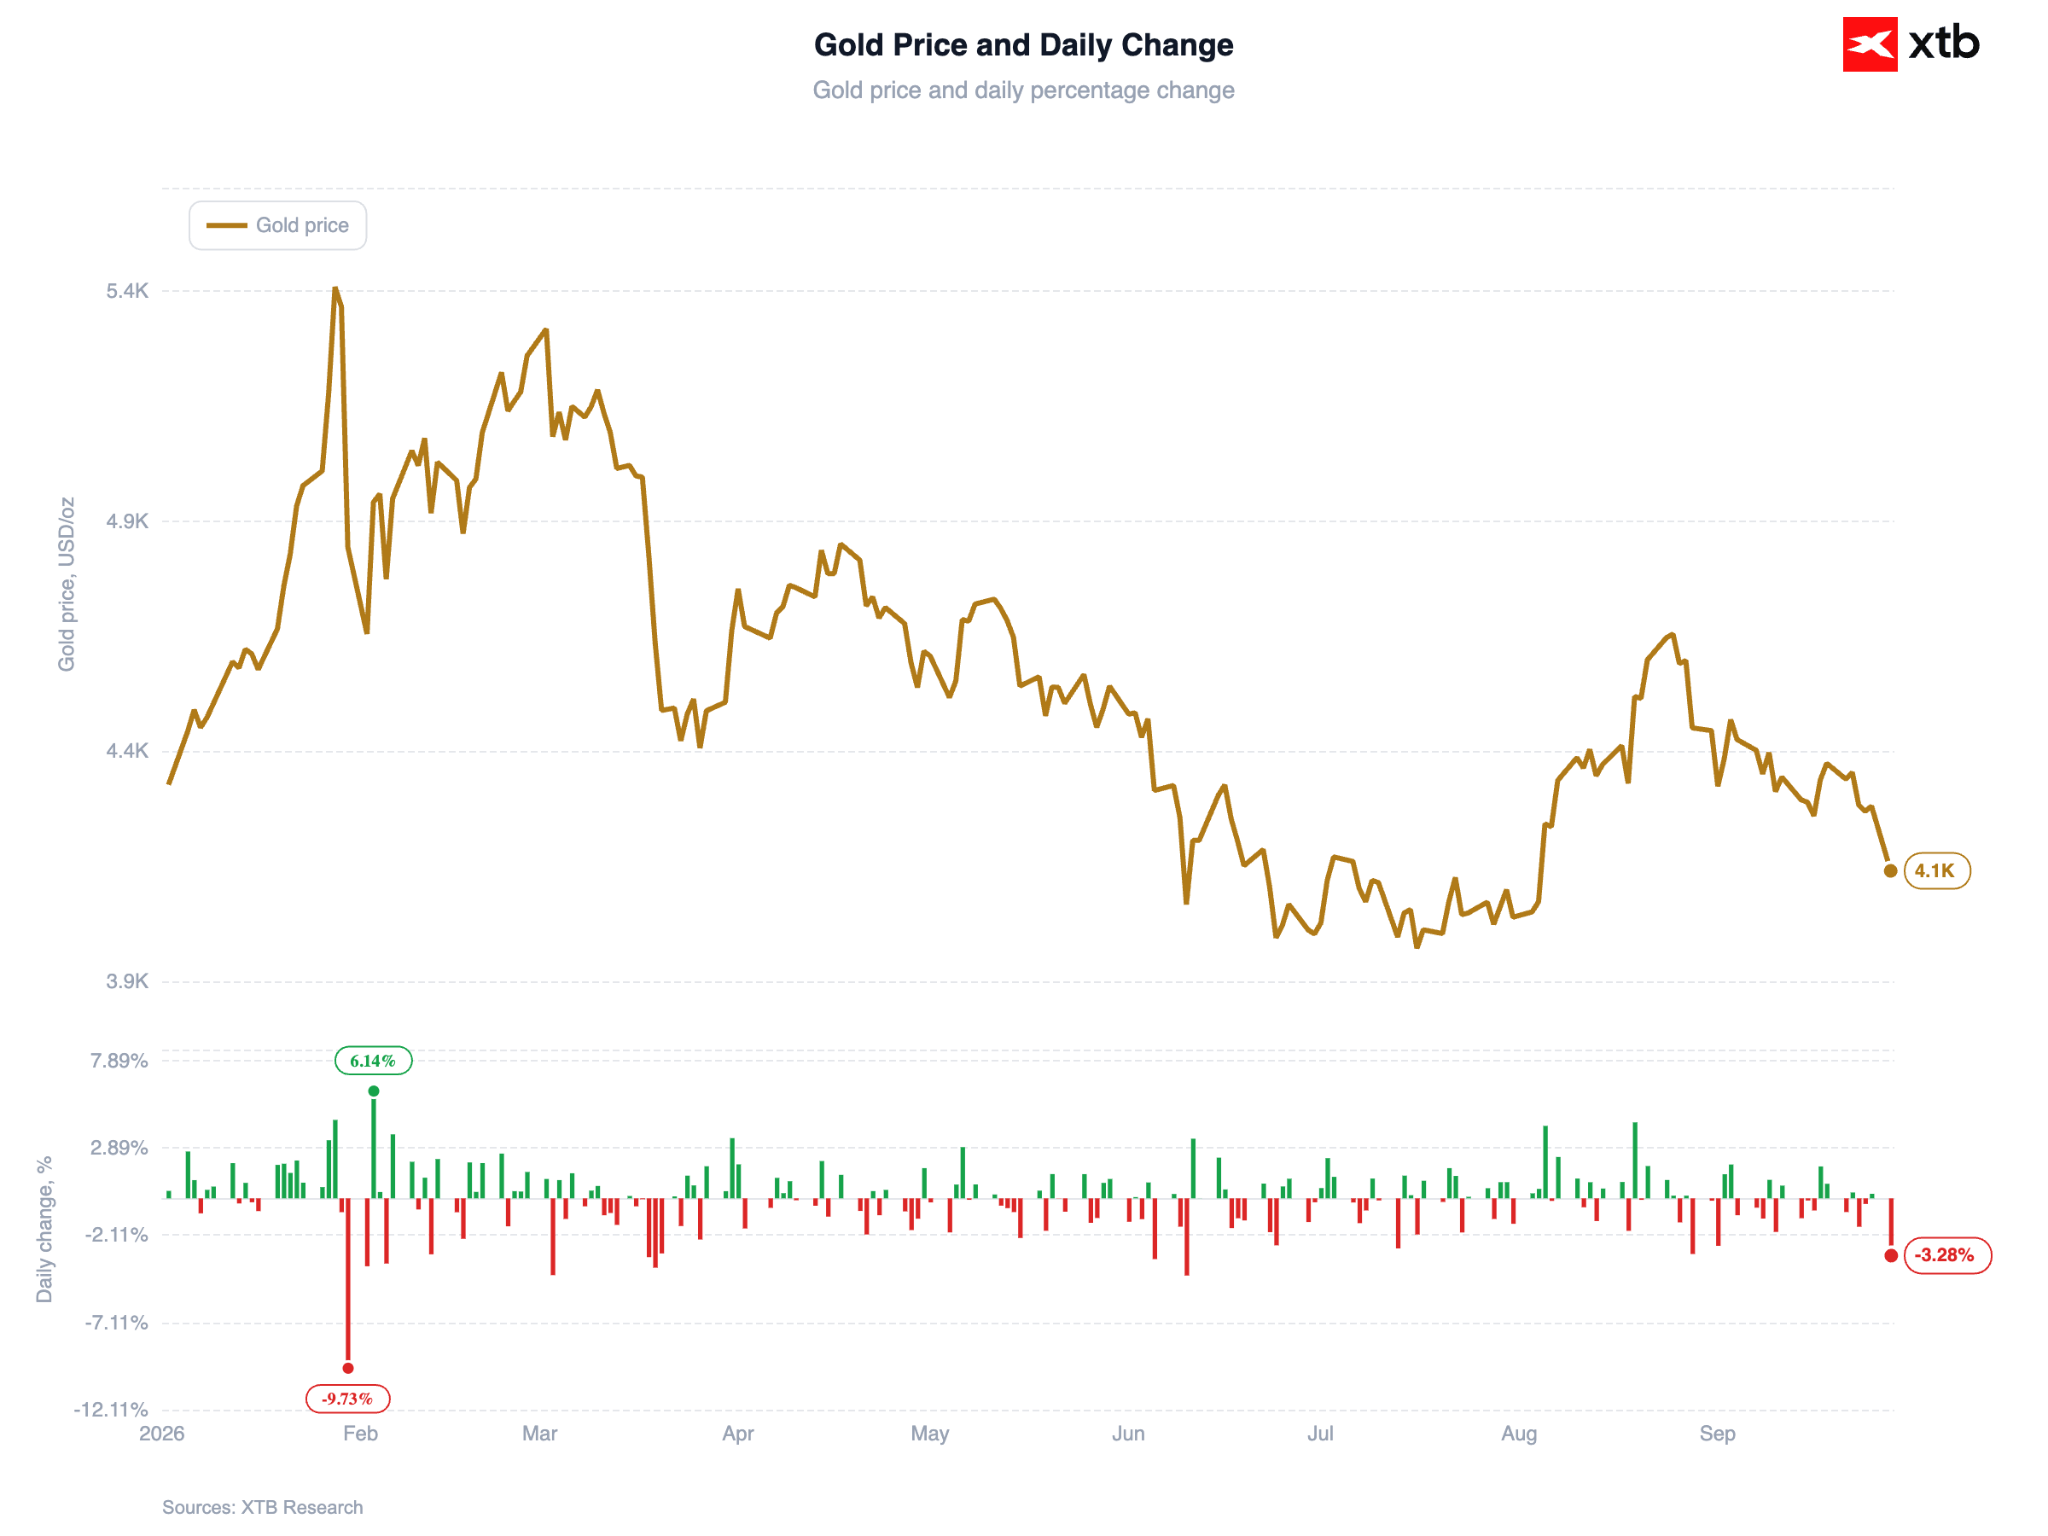
Gold continues the sell-off that began in the second half of August, falling below $4,140 per troy ounce (-3.6%). The decline from the local peak in August now exceeds 10%. Silver is suffering even steeper losses, down approximately 5% to around $61 per ounce.
Figure 5: Gold (2026)
 Source: XTB Research, 28.09.2026
The opportunity cost of investing in non-yielding precious metals increases daily, diminishing their appeal even amidst a highly volatile geopolitical environment. Pressure is further compounded by profit-taking from Chinese investors ahead of Golden Week, a traditional holiday period representing one of China's primary annual vacation weeks (1–7 October).
Monetary Policy
Higher long-term yields are driven both by government debt concerns and stronger economic growth prospects, along with expectations of further rate hikes, as highlighted on Friday by Cleveland Fed President Beth Hammack.
Over the weekend, Scott Bessent urged policymakers to maintain an "open mind" regarding interest rates. Just over a week ago, the Fed delivered its first rate hike since 2023 to combat persistent inflation and signaled the potential for further increases. Markets are currently pricing in roughly a 70% probability of an October rate hike.
Investors are now awaiting Wednesday's release of US PCE inflation data for August, which could temper growing price pressure concerns across the Atlantic and lead to a correction in the bond market.
—
Michał Jóźwiak, Financial Markets Analyst at XTB



US Open: Wall Street starts the week in red (28.09.2026)


📊Market Wrap: Oil drives yields higher and gold lower (28.09.2026)

Chart of the Day: Trump’s remarks strengthen the yen (25.09.2026)

Economic Calendar: Trump-Xi summit yields no breakthrough (25.09.2026)
This content has been created by XTB S.A. This service is provided by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, entered in the register of entrepreneurs of the National Court Register (Krajowy Rejestr Sądowy) conducted by District Court for the Capital City of Warsaw, XII Commercial Division of the National Court Register under KRS number 0000217580, REGON number 015803782 and Tax Identification Number (NIP) 527-24-43-955, with the fully paid up share capital in the amount of PLN 5.869.181,75. XTB S.A. conducts brokerage activities on the basis of the license granted by Polish Securities and Exchange Commission on 8th November 2005 No. DDM-M-4021-57-1/2005 and is supervised by Polish Supervision Authority.