


The headlines are strong. Chinese company YMTC has risen to third place worldwide in NAND memory shipments, overtaking Japan’s Kioxia. Comments have already emerged suggesting that Korean dominance of the memory market is under threat and that the future of NAND could belong to China. However, there is still a significant gap between ranking third in shipment volumes and posing a real threat to Samsung or SK hynix.
YMTC has indeed made significant progress. In the second quarter, the Chinese company accounted for 14% of global NAND shipments, compared with 25% for Samsung and 22% for SK hynix and Solidigm combined. YMTC overtook Kioxia in terms of shipment volume, but in terms of revenue it still ranked only fifth, behind Micron and Kioxia. This is an important distinction because it shows that the Chinese company is currently selling a large volume of memory, but has yet to establish a comparable position in the most valuable segments of the market.
It is also important not to look at the memory market as if all chips were equal. The largest manufacturers have long been shifting part of their production capacity toward more advanced and more profitable solutions. DRAM and HBM memory, used in data centers and artificial intelligence infrastructure, are particularly important here. Demand for these products is currently enormous, and their contribution to the financial performance of the biggest manufacturers continues to grow.
NAND remains a very important market, of course. These types of memory are used in smartphones, computers, SSDs, and many other devices. This is the segment where YMTC has considerably more room for further growth, particularly if it manages to increase its international sales. Apple could be a very important customer here, as the company is testing Chinese memory products and looking for ways to diversify its supply chain. If YMTC does gain access to a larger share of Apple’s supply chain, it could significantly accelerate the company’s growth.
That does not change the fact that the memory industry requires enormous investment. Building fabrication plants costs billions of dollars, developing each new generation of technology requires continuous spending, and increasing production does not guarantee that high margins can be maintained. YMTC may therefore be able to rapidly increase its share of the NAND market, but translating that growth into a position comparable to Samsung or SK hynix will be much more difficult.
YMTC’s current position therefore does not yet represent a threat to the dominance of Samsung and SK hynix. It does, however, demonstrate something equally important: China is capable of entering the global NAND elite, rapidly expanding production, and gradually taking market share from companies that have controlled this segment for years.
That alone is a major development. YMTC wants to go even further and, according to reports, plans to challenge for the number one position worldwide by the end of 2027. Its planned public offering is expected to raise around $5 billion to fund production expansion and research.
It is also worth looking at the bigger picture. China is no longer simply trying to copy Western technologies. It is building its own companies, its own factories, and its own technological ecosystem. YMTC is one of the best examples of this process. China may still be several years behind the global leaders in some of the most advanced technologies, but that gap no longer looks like a barrier that Beijing is incapable of overcoming.
And that is precisely why YMTC’s rise to third place is more significant than the 14% figure alone might suggest. It does not yet signal the end of Samsung’s or SK hynix’s dominance. What it does show is that China’s semiconductor industry is capable of steadily increasing its scale, capturing additional market segments, and leveraging the enormous resources Beijing is directing toward the development of domestic technology.
For Samsung, SK hynix, and Micron, this is not yet a reason to panic. It is, however, another signal that cannot be ignored. If YMTC maintains its current pace, today’s battle for third place could be only the beginning of a much larger struggle for control of the memory market.
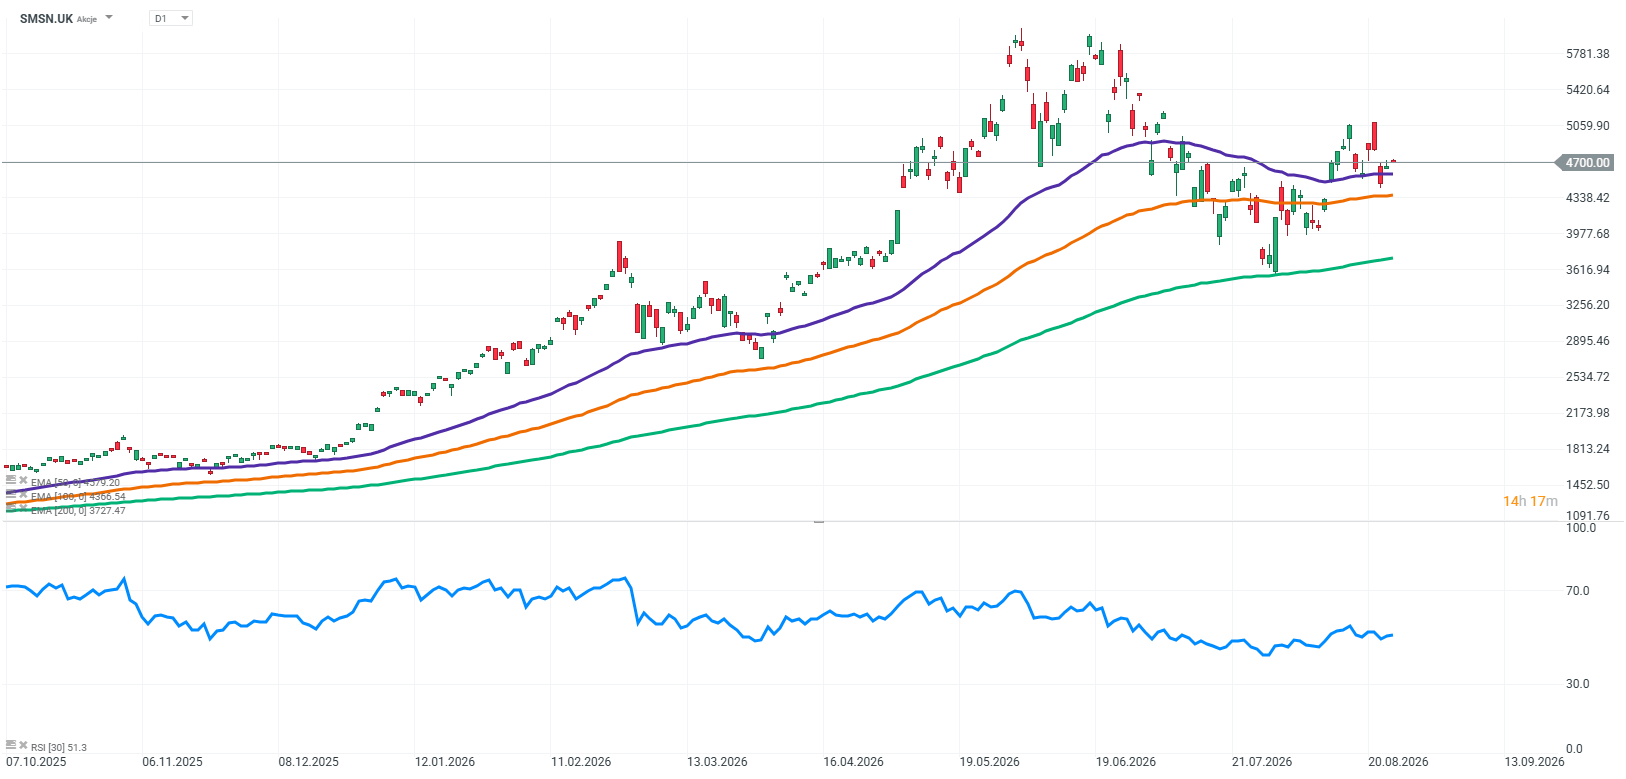
Source: xStation5



Morning Wrap: Brent at $107, AI sell-off (15.09.2026)


Michael Burry’s portfolio: Revolution or rebalance?



US OPEN: AI slows, oil rises, markets fall


Market Wrap: European Stocks in the Red. AI Sinks, Oil Surges
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.