


Wednesday's trading session saw a sharp deterioration in sentiment across global markets. Following a multi-day decline, crude oil prices staged a rebound, alongside a rise in LNG prices. Combined with further hawkish comments from Federal Reserve officials and extraordinarily robust US PMI data, this led to heightened expectations of Fed interest rate hikes. Markets now anticipate that the FOMC will continue its tightening cycle as early as the October meeting.
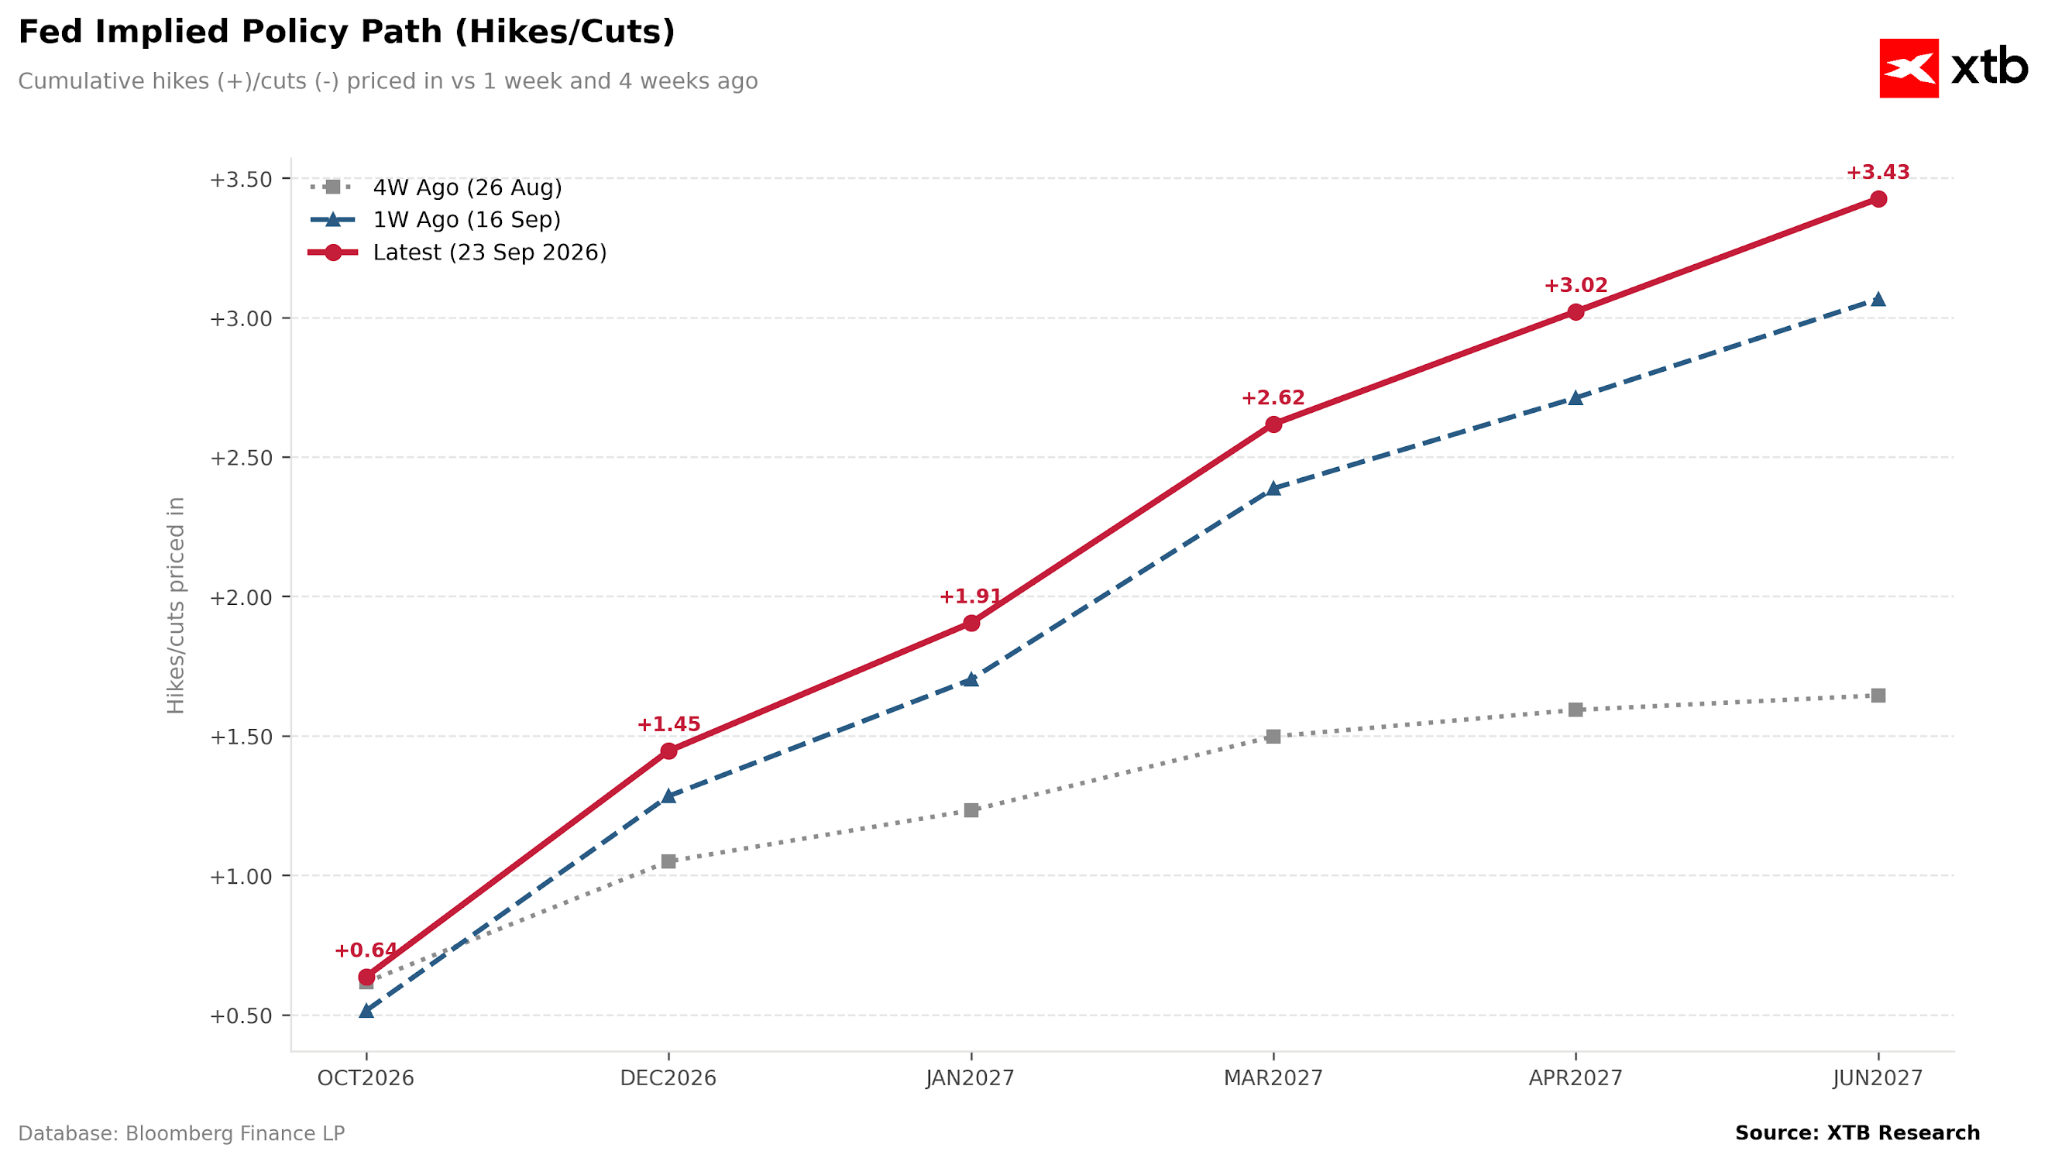
Figure 1: Changes in Market Expectations for Federal Reserve Interest Rate Hikes (2026 - 2027)
 Source: XTB Research, 23.09.2026
Note: The path from 4 weeks ago refers to a lower base level (i.e. interest rate levels prior to last week's rate hike)
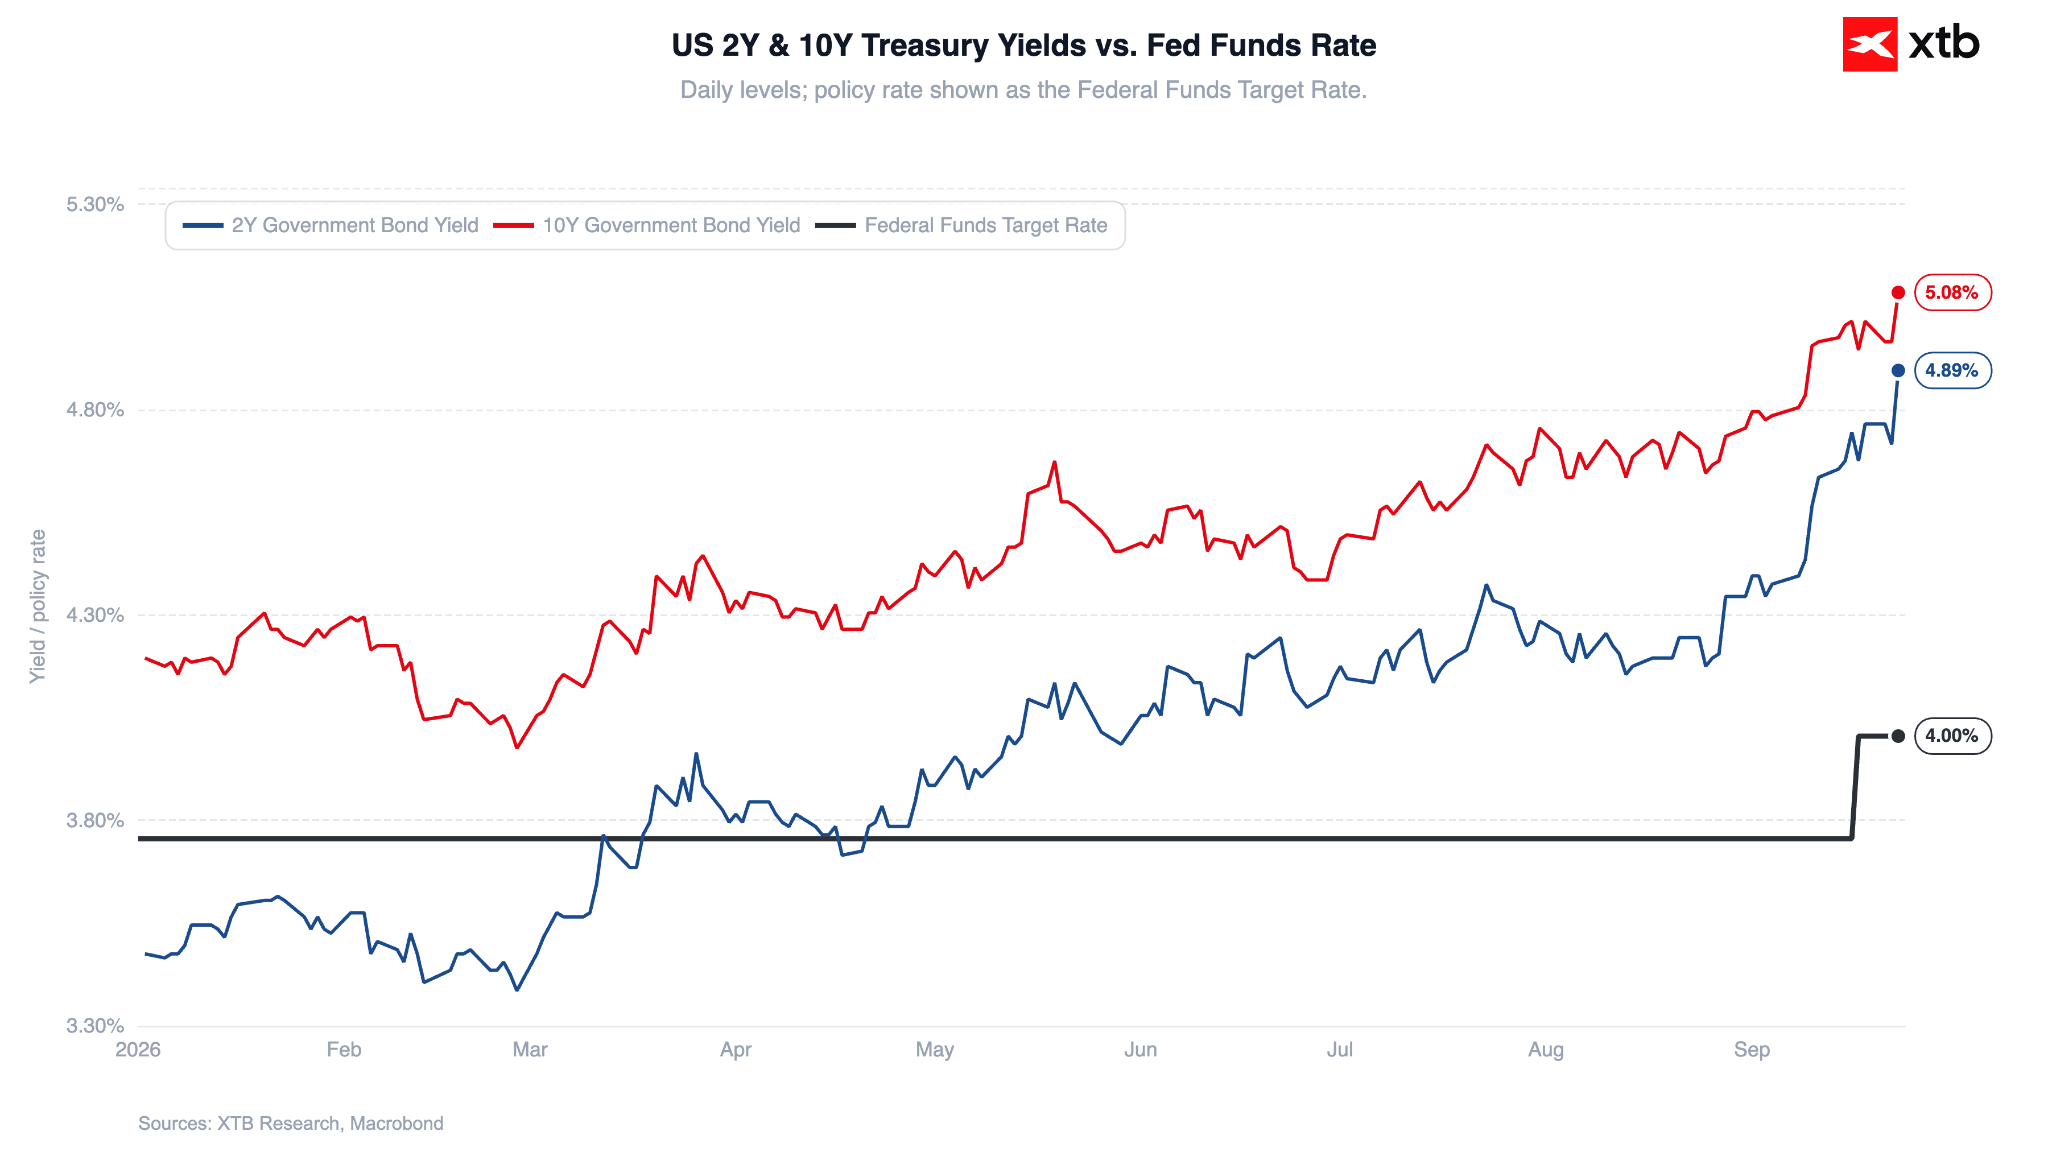
10-year Treasury yields climbed to 5.12%, reaching their highest level since 2007. The technology sector, particularly sensitive to shifts in the bond market, suffered notable losses. However, the broader Wall Street market was not spared either:
- Nasdaq: -0,9%
- S&P 500: -0,7%
- Dow Jones: -0,5%
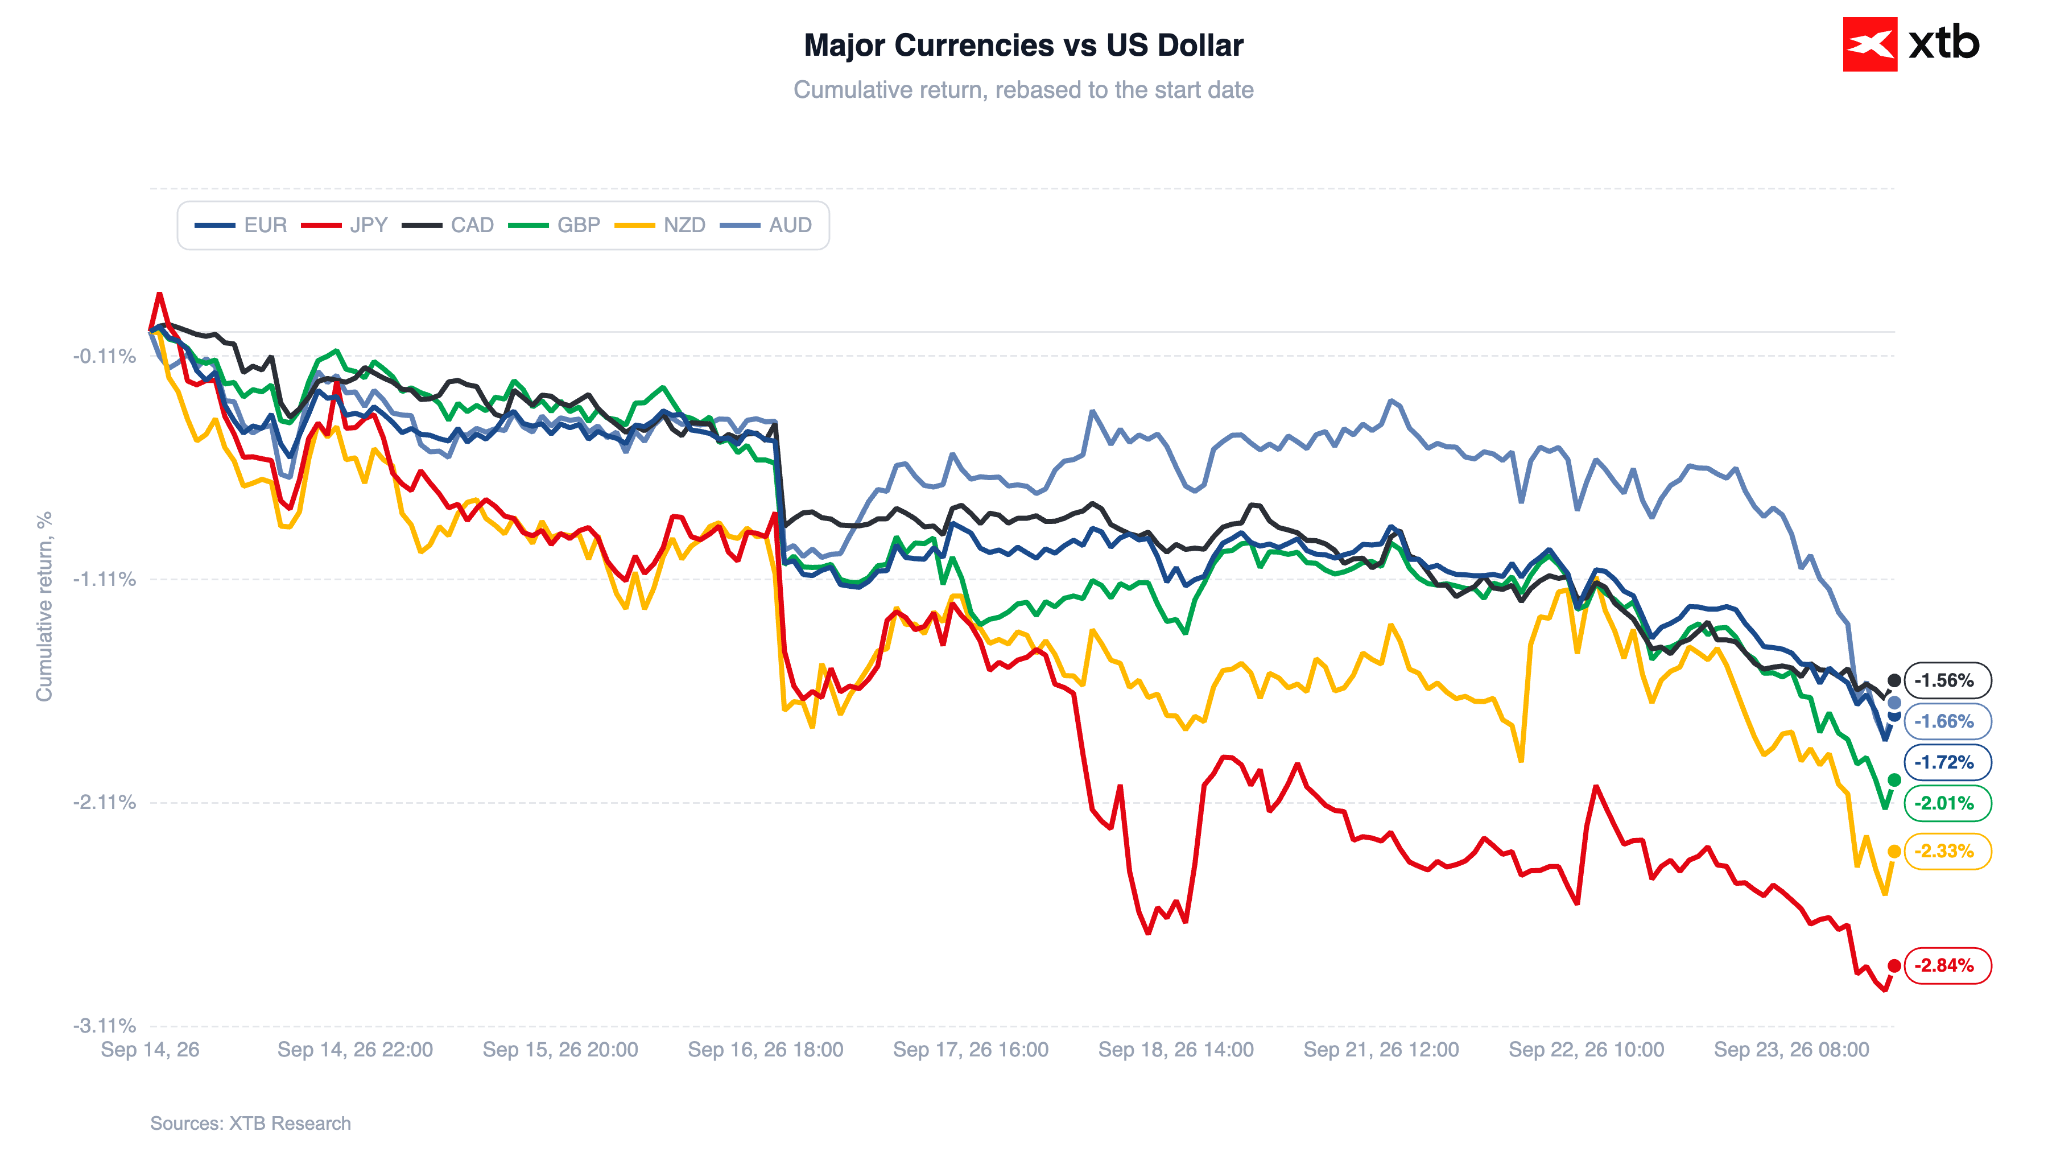
Attention also turned to the foreign exchange market, driven by the continued appreciation of the US dollar. The EURUSD pair broke sharply below the 1.14 level, falling by more than 0.5% today.
Figure 2: Performance of Major Currencies Against the US Dollar (10.09.2026 - 23.09.2026)
 Source: XTB Research, 23.09.2026
Stock Market
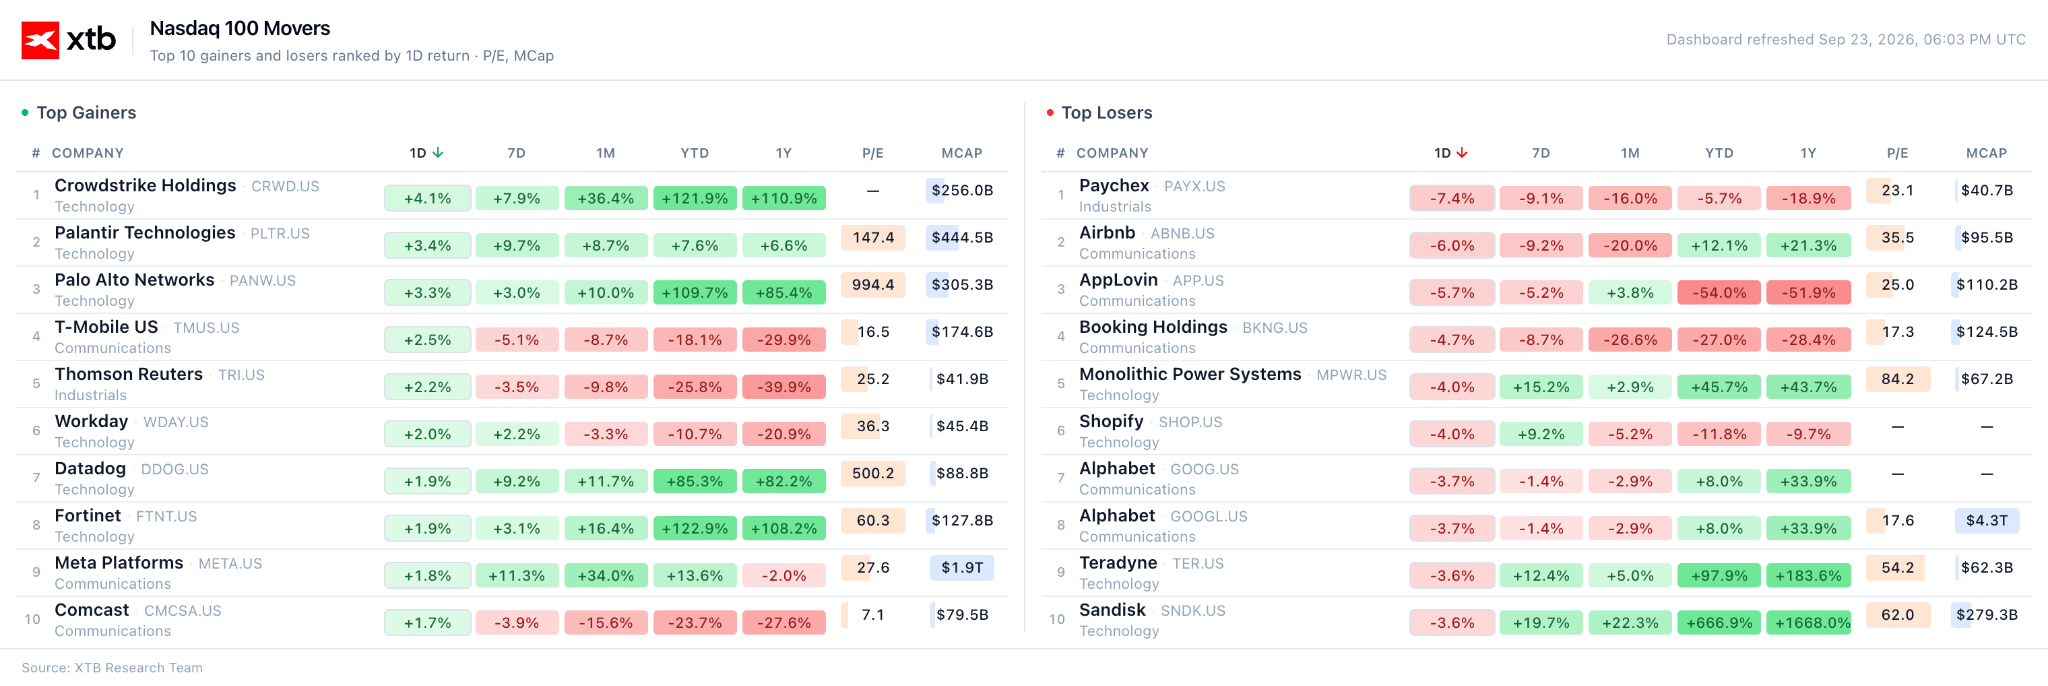
Pressure today fell primarily on technology stocks, which had recorded substantial gains in recent days. The SOXX index dropped by more than 1.5%, snapping a six-session winning streak. Sandisk and Micron surrendered part of yesterday's gains (down 3.0% and 1.9%, respectively), while Nvidia also suffered losses (-1.5%). This pullback can be attributed to profit-taking following the Nasdaq 100 reaching a new all-time high yesterday, as well as rising oil prices and US bond yields.
Figure 3: Gainers and Losers in the Nasdaq 100 (23.09.2026)
 Source: XTB Research, 23.09.2026
Small-cap stocks also underperformed, with the Russell index losing 1.6% today.
Meta the Star of September
Meta shares gained nearly 2% today. Month-to-date in September, the company is up almost 30%, putting it on track for its best monthly performance since July 2013.
The primary catalyst remains Muse, an AI agent capable of transforming not only user engagement across Meta's applications but also the monetization model of its entire ecosystem. Some analysts expect Meta to capture market share in user traffic and customer relationships from platforms such as Booking, Uber, and DoorDash.
Fed Receives Further Justification for Rate Hikes
Monetary policy remains the focal point for markets. Investors are increasingly pricing in further rate increases at the upcoming October meeting, driven by highly hawkish statements from Fed officials and robust macroeconomic data.
Speaking in Chicago today, Governor Michael Barr highlighted the necessity for continued rate increases. He noted that the US economy remains strong and the labour market solid, providing scope for further monetary tightening.
Rising interest rate expectations exerted upward pressure on bond yields. US 10-year Treasury yields rose by approximately 14 bps today to 5.08%.
Figure 4: US 2-Year and 10-Year Treasury Yields vs. Fed Funds Rate (2026)
 Source: XTB Research, 23.09.2026
PMI Data Exceed Expectations Again
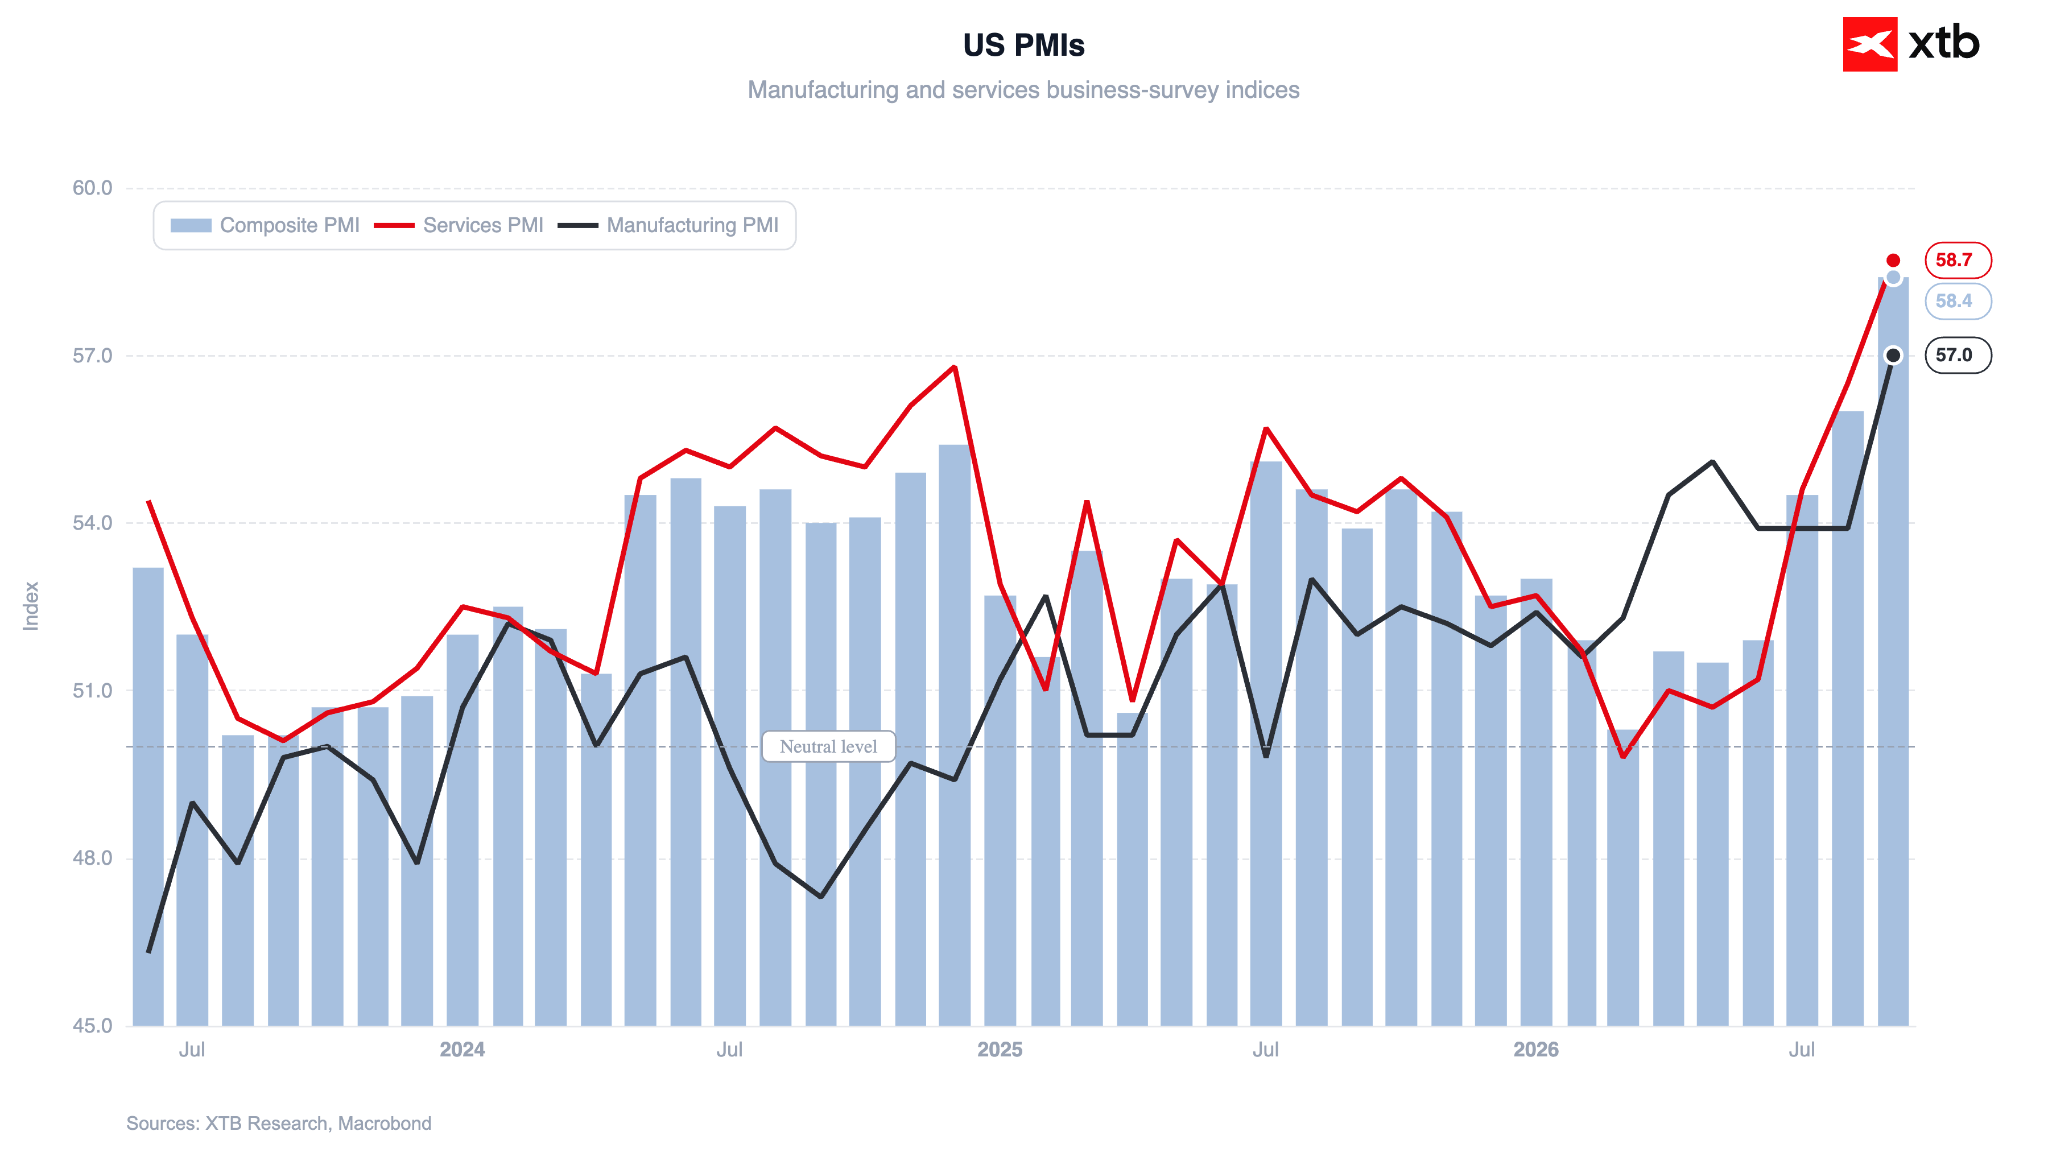
This economic strength was confirmed today by key leading indicators for the US economy.
Figure 5: US PMI Indices (2023 - 2026)
 Source: XTB Research, 23.09.2026
Indicators for both sectors came in significantly above consensus. The Services PMI rose to 58.7, while the Manufacturing PMI climbed to 57.0. On a composite basis, these are the strongest readings in 5 years, consistent with annualised GDP growth of around 5%.
According to the S&P report, conditions in the labour market improved markedly, with businesses actively expanding headcount to tackle substantial order backlogs. These backlogs accumulated at their fastest pace since May 2022.
Cost pressures intensified once again, with businesses increasingly passing higher costs on to customers.
Oil Snaps Losing Streak
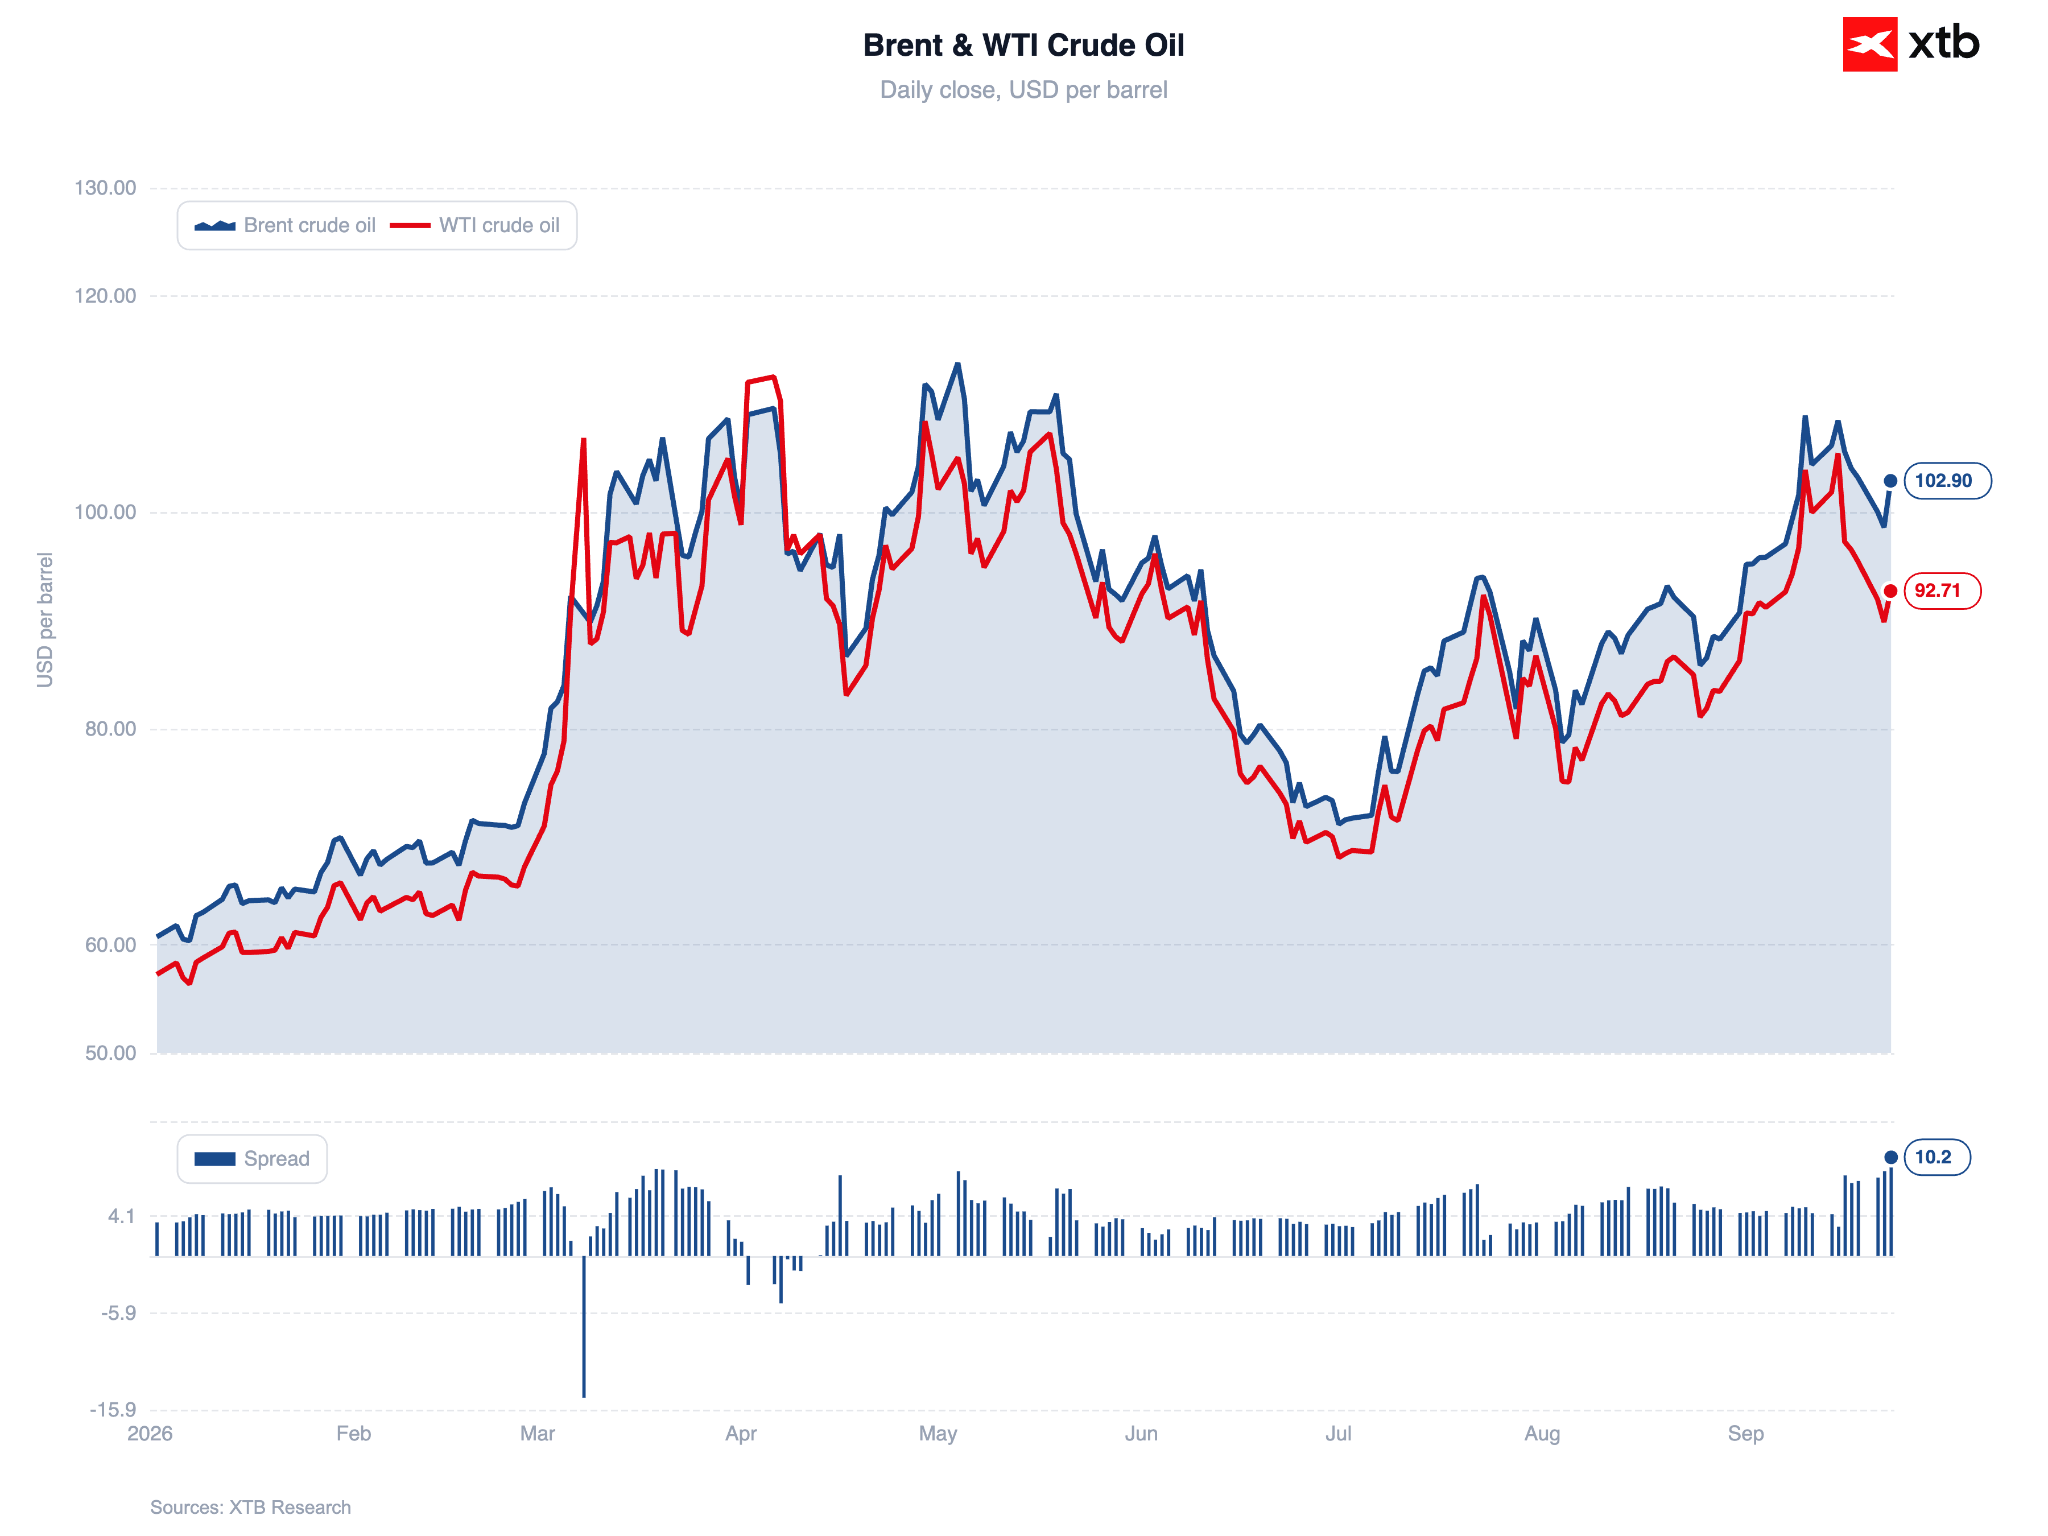
Brent crude gained over 3% today, climbing back above $102 per barrel and snapping a multi-day losing streak. WTI rose by 2.4% to just below $93. While Trump signaled progress in US-Iran talks, markets appeared to attach little significance to the statements.
In this context, it is worth highlighting the report from the US Department of Energy, which announced a 3 million barrel increase in crude oil inventories for the week ended 18 September. Meanwhile, both crude imports and exports declined significantly, falling by 1.2 million and 1.6 million barrels, respectively. Gasoline inventories also fell (by 1.7 million barrels), while refinery capacity utilisation dropped to 94%.
Figure 6: Brent and WTI Crude Oil (2026)
 Source: XTB Research, 23.09.2026
—
Michał Jóźwiak, Financial Markets Analyst at XTB


US Open: Nasdaq drops from the all-time high (23.09.2026)

BREAKING: Strong PMI indicators do not help the euro! EURUSD tests key 1.1400 level


US OPEN: Tech is looking for a reason to grow, diplomacy in the background



🛢️WTI crude tests $90. Brent below $100
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.