


US health insurance giant UnitedHealth Group (UNH.US) reported third-quarter 2026 results that significantly exceeded Wall Street expectations in terms of both revenue and earnings per share. Shares are rising nearly 3% after operating profitability improved and the medical care ratio came in below forecasts, suggesting more effective control over healthcare costs. Another positive development was the upward revision to the company's full-year earnings guidance, although total enrollment figures slightly disappointed.
-
Group revenue reached $112.69 billion, compared with expectations of $111.03 billion. Adjusted earnings per share (EPS) came in at $4.69, comfortably exceeding the consensus estimate of $4.12.
-
Reported EPS increased to $4.56 from $2.59 a year earlier, representing approximately 76% year-over-year growth and pointing to a substantial recovery in profitability.
-
The UnitedHealthcare insurance segment generated $86.33 billion in revenue, exceeding the forecast of $84.87 billion. Optum, which provides healthcare services, pharmacy solutions and analytics, reported revenue of $66.88 billion, slightly above the consensus estimate of $66.48 billion.
-
Total enrollment reached 48.3 million, below expectations of 48.62 million. This was one of the weaker aspects of the report, potentially reflecting ongoing competitive pressures or changes in the company's insurance portfolio.
-
The medical care ratio (MCR) came in at 88.4%, compared with expectations of 89.9%. A lower ratio means that a smaller proportion of premium revenue was spent on medical benefits, supporting profitability in the insurance business.
-
Operating margin improved to 5.8% from 3.8% a year earlier, despite the operating cost ratio reaching 12.8%, slightly above expectations of 12.6%. The margin improvement suggests that the benefits of lower medical costs outweighed pressure from other operating expenses.
-
UnitedHealth raised its full-year 2026 adjusted EPS guidance to at least $20.50, up from its previous range of $19.50–$20.00. At the same time, the company increased its reported EPS guidance to at least $19.50, compared with the previous range of $18.45–$18.95, signaling greater management confidence in its performance toward the end of the year.
The results suggest that UnitedHealth's profitability recovery is gaining traction, with the lower-than-expected medical care ratio and upward revision to earnings guidance particularly important for investors. However, sustaining this improvement in the coming quarters will depend on medical cost trends and the stabilization of enrollment levels.
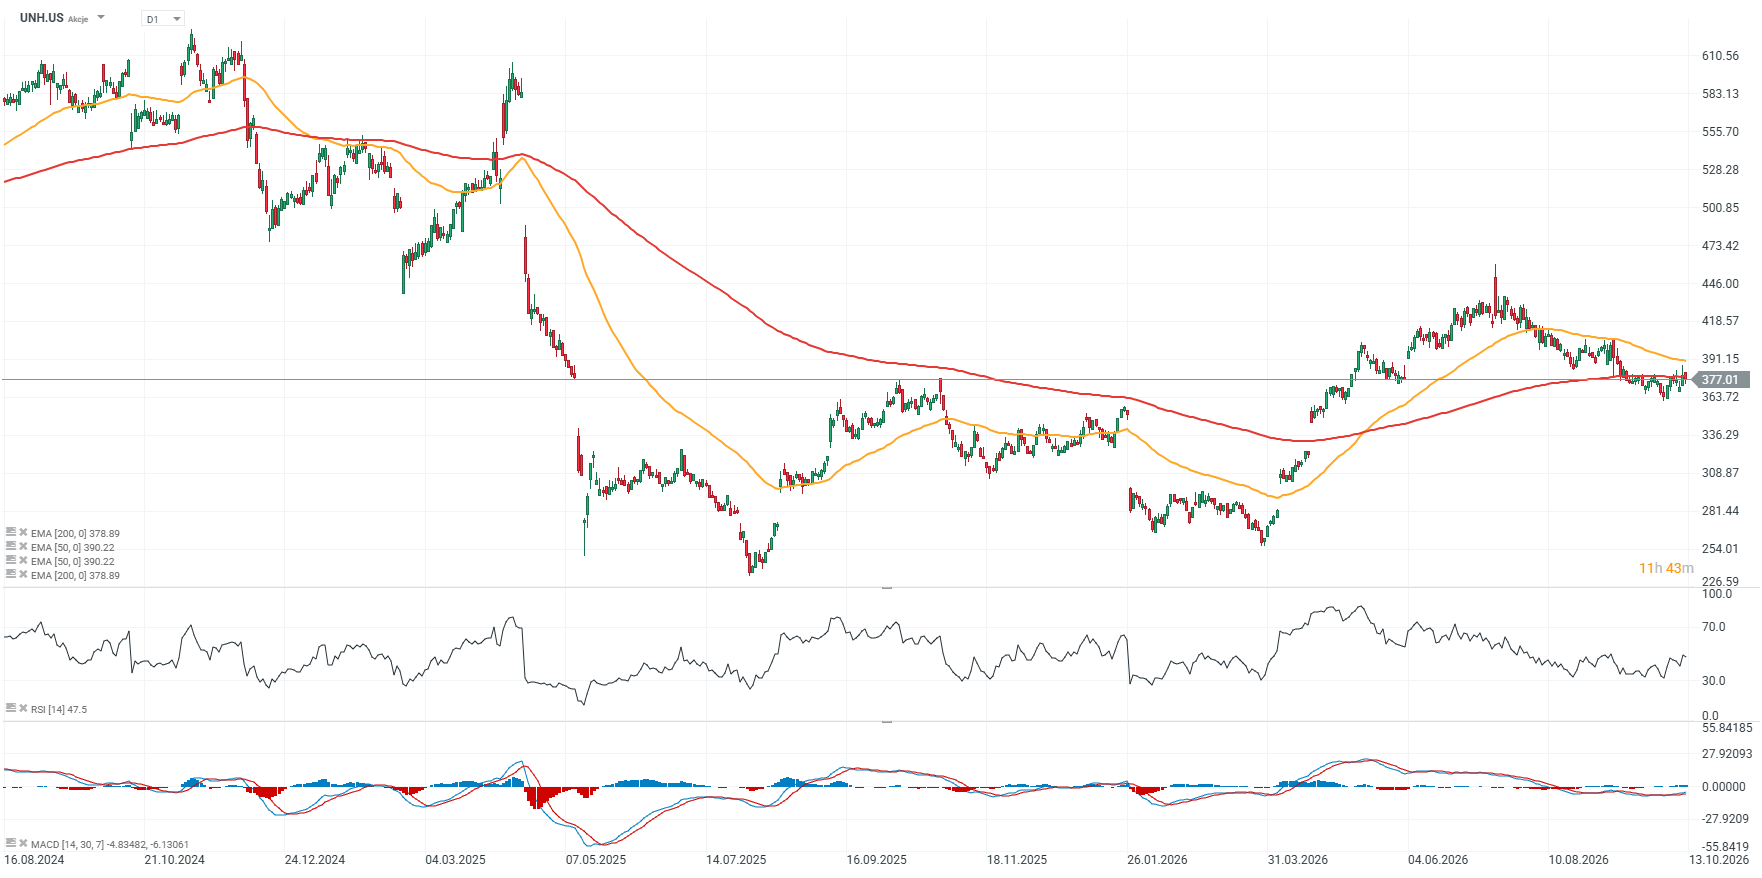
UNH.US Stock Chart (D1 Timeframe)
The stock has endured a challenging period and is still trading approximately 40% below its all-time highs. Recently, shares have attempted to break above the key 200-session exponential moving average (EMA200, red line), and the positive market reaction to the earnings report appears likely to support a breakout above this resistance level, potentially opening the way toward $400 and $440.
Source: xStation5
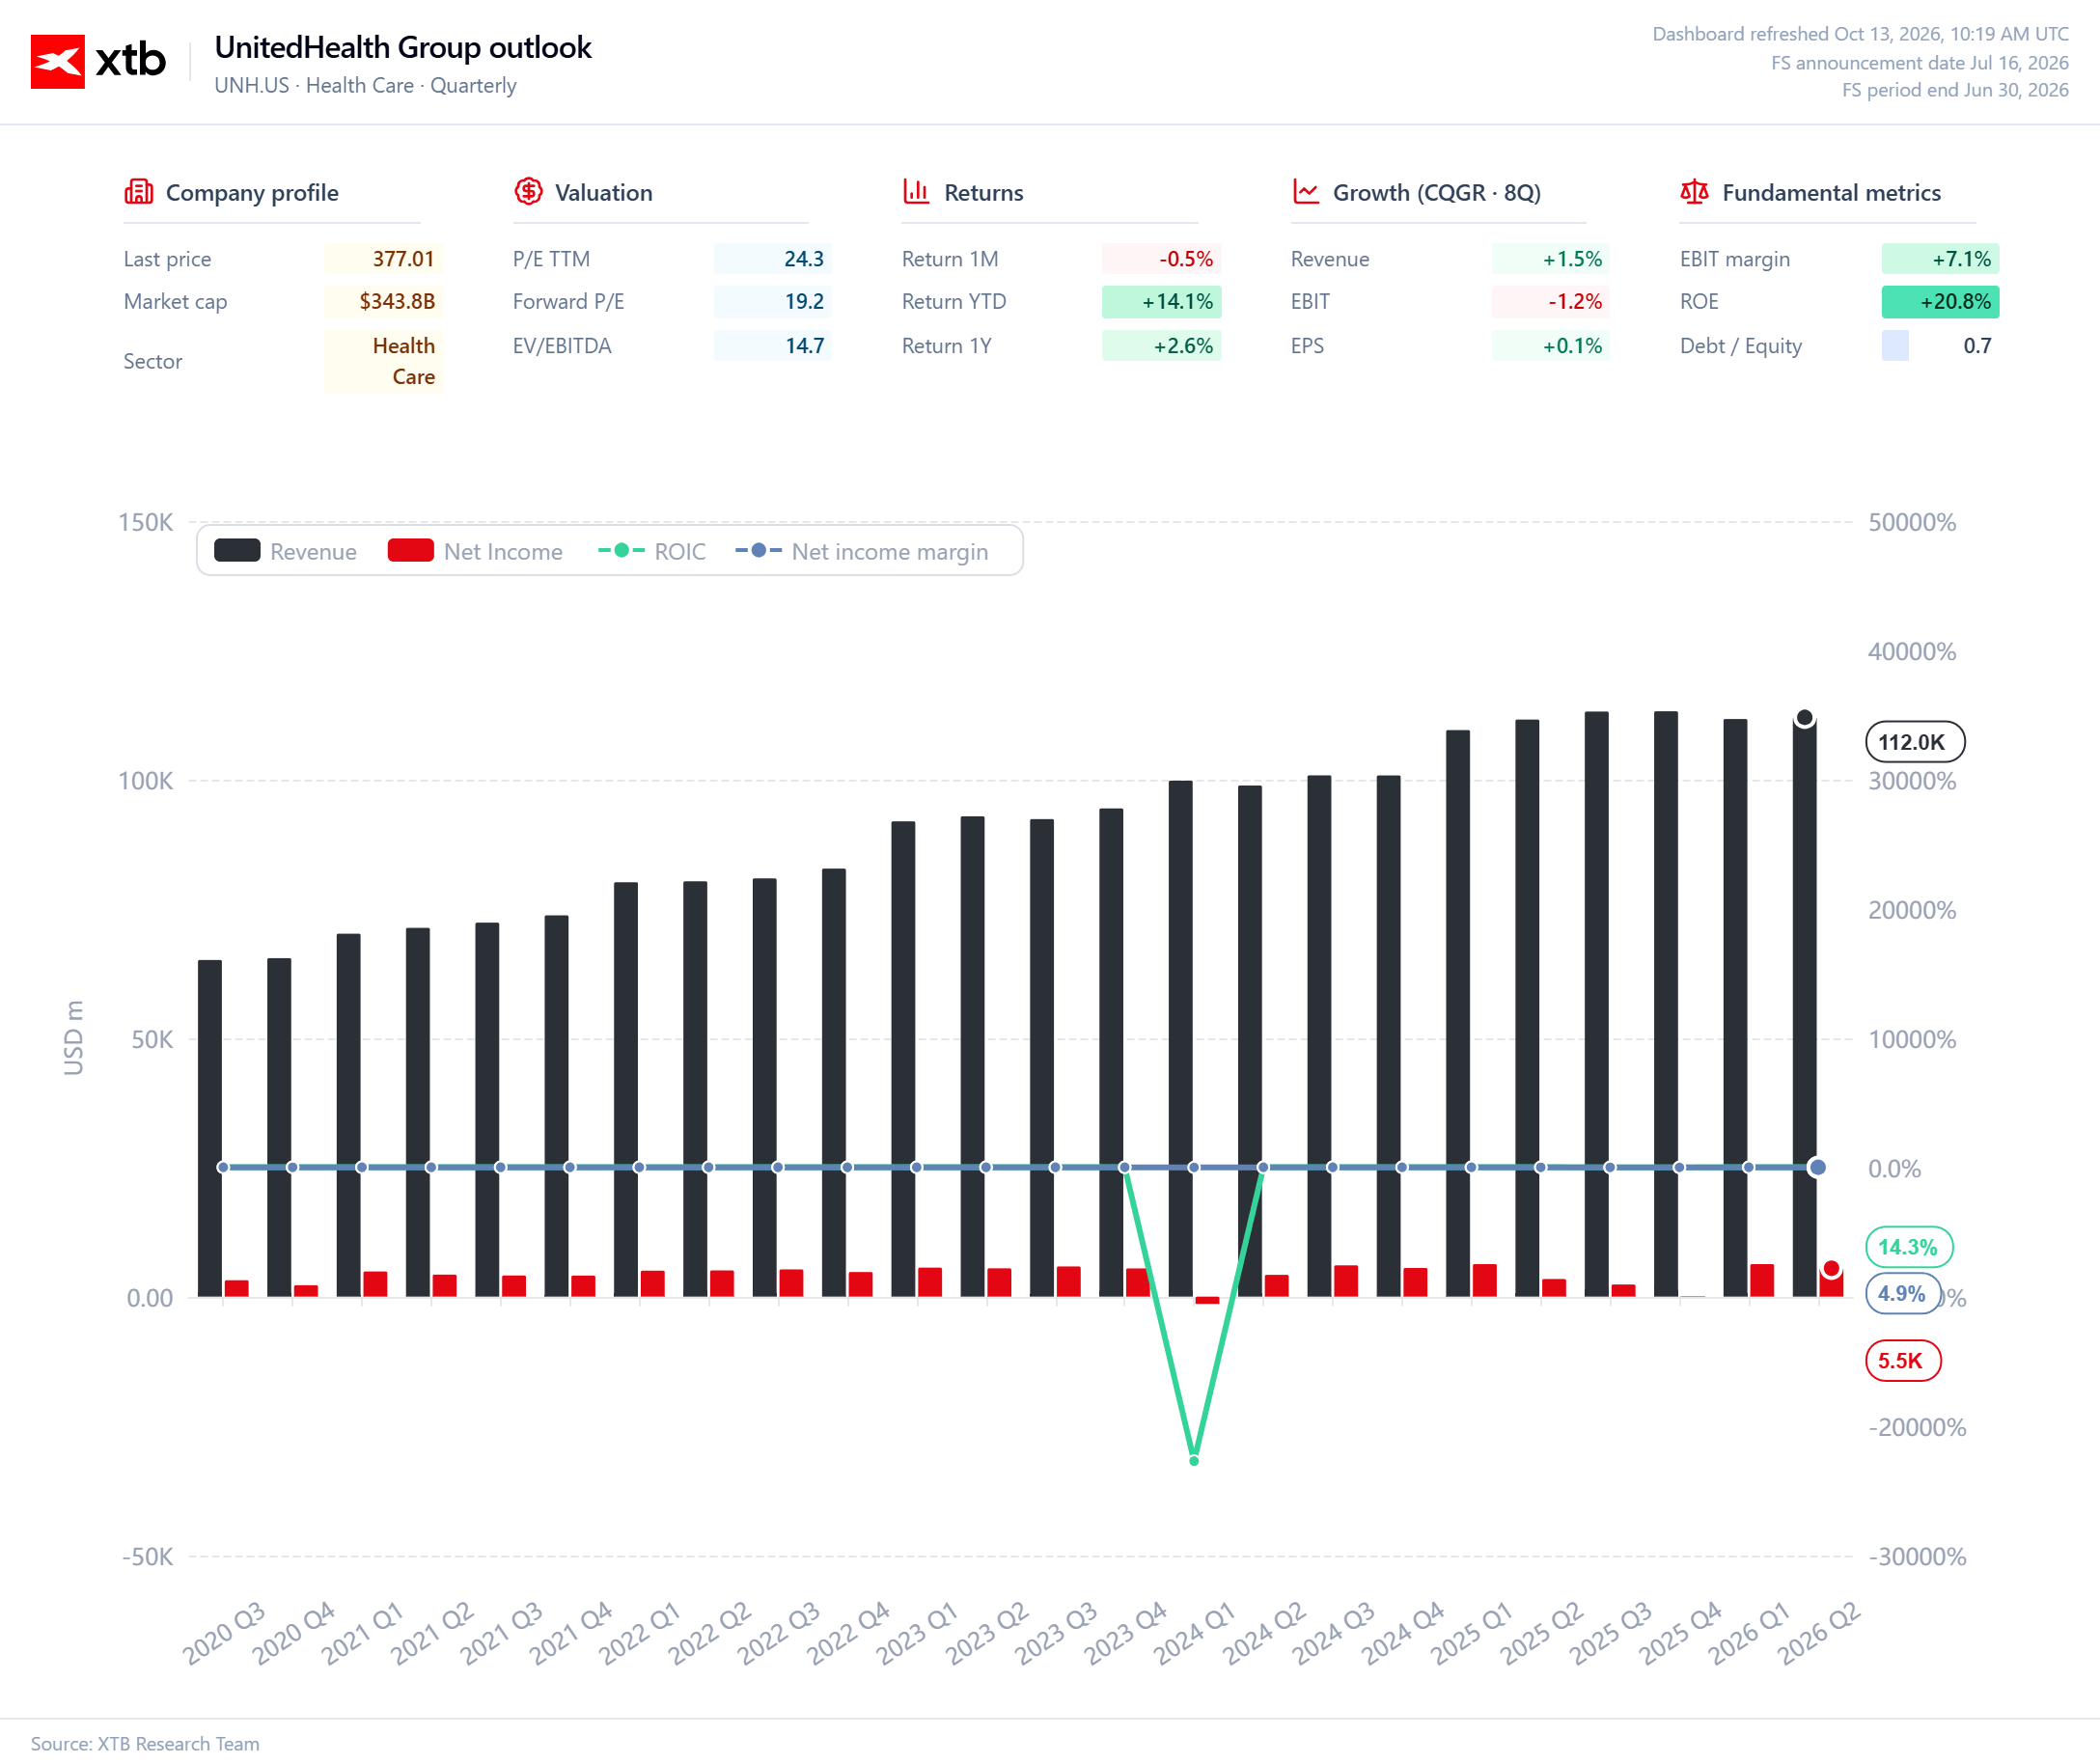
UnitedHealth Group's revenue remains on a long-term upward trajectory, although recent quarters demonstrate that business expansion does not necessarily translate into a proportional improvement in profitability. In the second quarter of 2026, revenue reached approximately $112 billion, while net income amounted to around $5.5 billion and net profit margin stood at 4.9%, indicating a recovery following a period of elevated cost pressures. Return on invested capital (ROIC) of 14.3% suggests that the company continues to generate meaningful returns on the capital deployed in its business, although this metric alone does not guarantee a sustainable improvement in profitability.
With a trailing price-to-earnings (P/E) ratio of 24.3 and a forward P/E of 19.2, based on expected earnings over the next 12 months, the market appears to be pricing in a continued earnings recovery, even though earnings per share growth has remained virtually flat over the past eight quarters (+0.1% CQGR). The key to UnitedHealth's outlook will therefore be not only maintaining revenue growth but, more importantly, improving margins, controlling medical costs and generating higher returns on invested capital.
Source: XTB Research



🖥️Chart of the Day - US100: Is the KOSPI crash a foretaste of Nasdaq's troubles?



Daily Summary: Investors Concerns Rise Ahead of Earnings Season


US OPEN: Wall Street under pressure from oil and semiconductors

Morning Wrap: Oil cheaper despite attacks on Saudi Arabia, markets await CPI (12.10.2026)
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.