

- Semiconductor losses weigh on the Nasdaq 100, while major banks support the Dow Jones.
- JPMorgan, Citigroup, and Wells Fargo reported strong third-quarter lending revenue despite elevated interest rates.
- Microsoft shares gained over 1%, approaching their first record closing high in nearly a year.
- Fermi shares surged nearly 20% after securing an AMD credit support agreement for Project Matador.
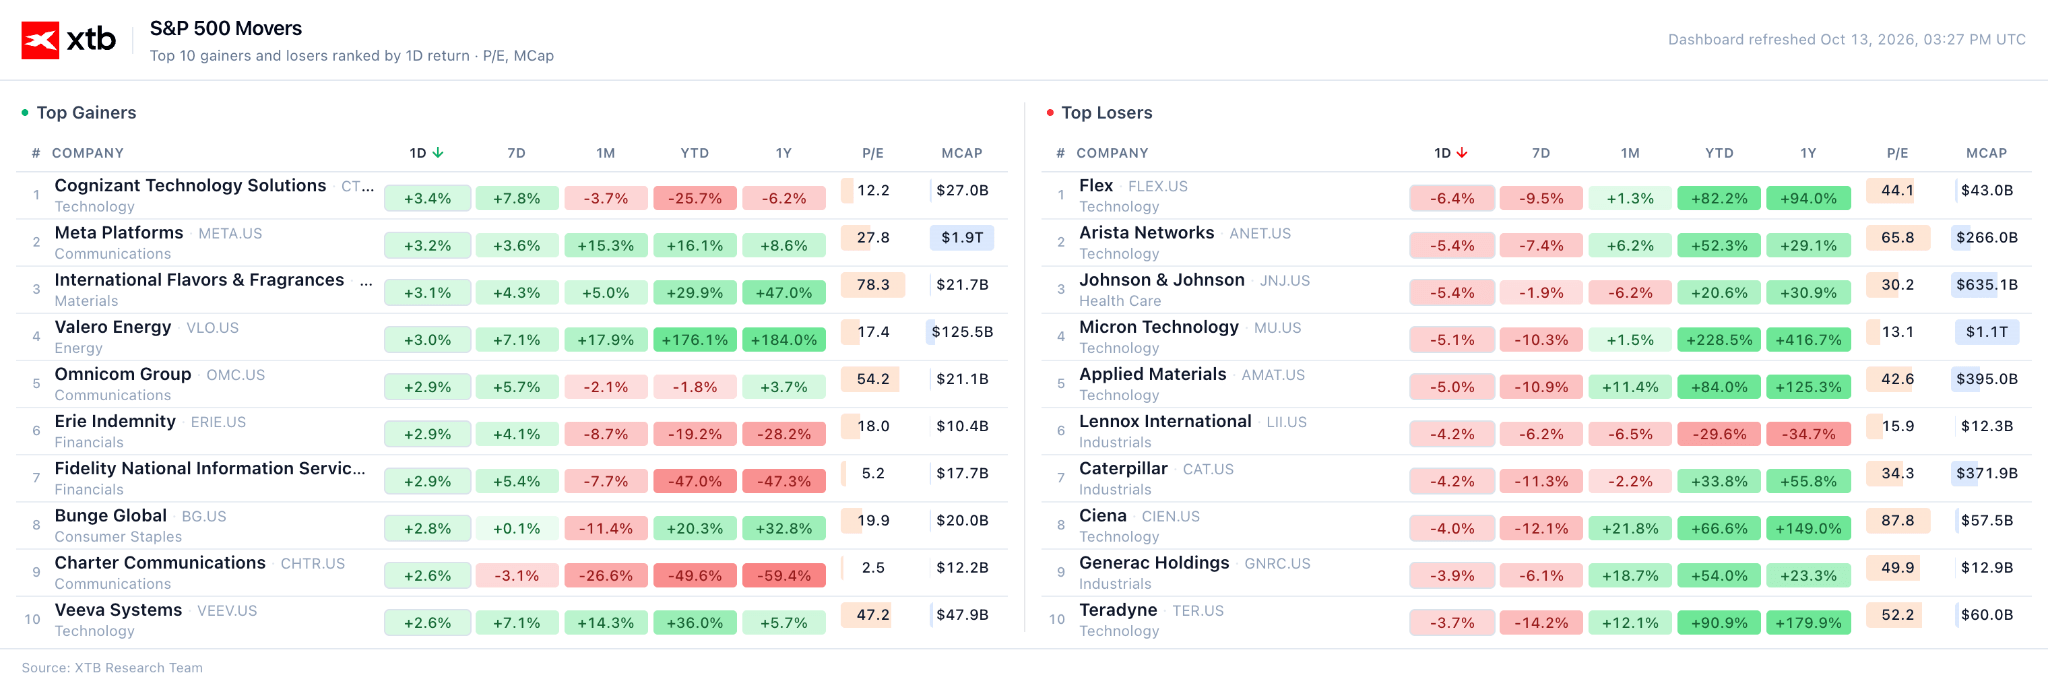
Wall Street opened slightly in the red today. The S&P 500 slipped by 0.1%, remaining close to record highs. The Nasdaq 100 (-0.5%) was dragged down by another day of sell-offs in the semiconductor sector (the SOXX index dropped by 1.7%). Meanwhile, the Dow Jones traded in the green (+0.1%), supported by encouraging quarterly reports released today by several major banks.
Figure 1: S&P 500 Winners and Losers (13.10.2026)
 Source: XTB Research, 13.10.2026
Semiconductor sell-off persists
The broad semiconductor ETF (iShares Semiconductor ETF, commonly known as SOXX) is currently trading more than 18% below its June peak, posting a further decline of over 1.7% today.
It is worth noting that earlier in the day, South Korea's KOSPI index - heavily weighted towards memory chip manufacturers - suffered significant losses (-5.5%).
This came following reports that China's CXMT has achieved a technological breakthrough in memory chip production, posing a direct threat to the oligopoly held by the three DRAM giants: Samsung, SK Hynix, and Micron.
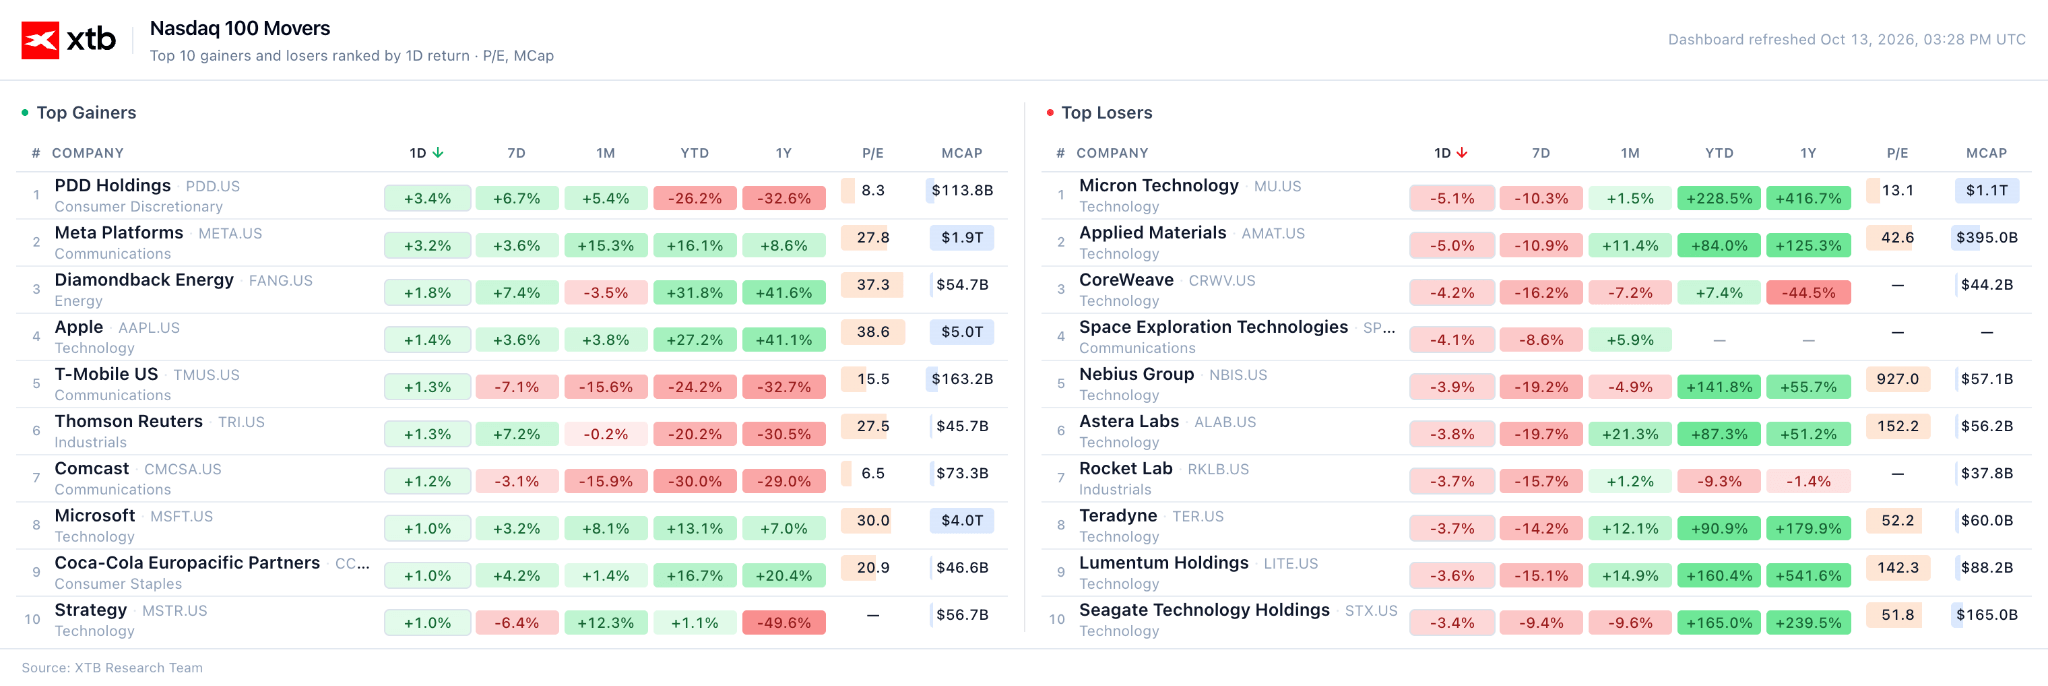
Figure 2: Nasdaq 100 Gainers and Losers (13.10.2026)
 Source: XTB Research, 13.10.2026
Unsurprisingly, Micron is among the heaviest hit today (-5.2%). Hard drive manufacturers are also pulling back, including Seagate (-3.6%) and Western Digital (-3.7%).
Nvidia (-0.6%), Broadcom (-0.2%), and AMD (-1.2%) are recording relatively modest losses.
Banks kick off earnings season with impact
JPMorgan, Citigroup, and Wells Fargo reported record lending revenue for the third quarter, as loan demand remains robust despite elevated interest rates. Goldman Sachs also stood out with impressive results in its equities segment (+3.5%).
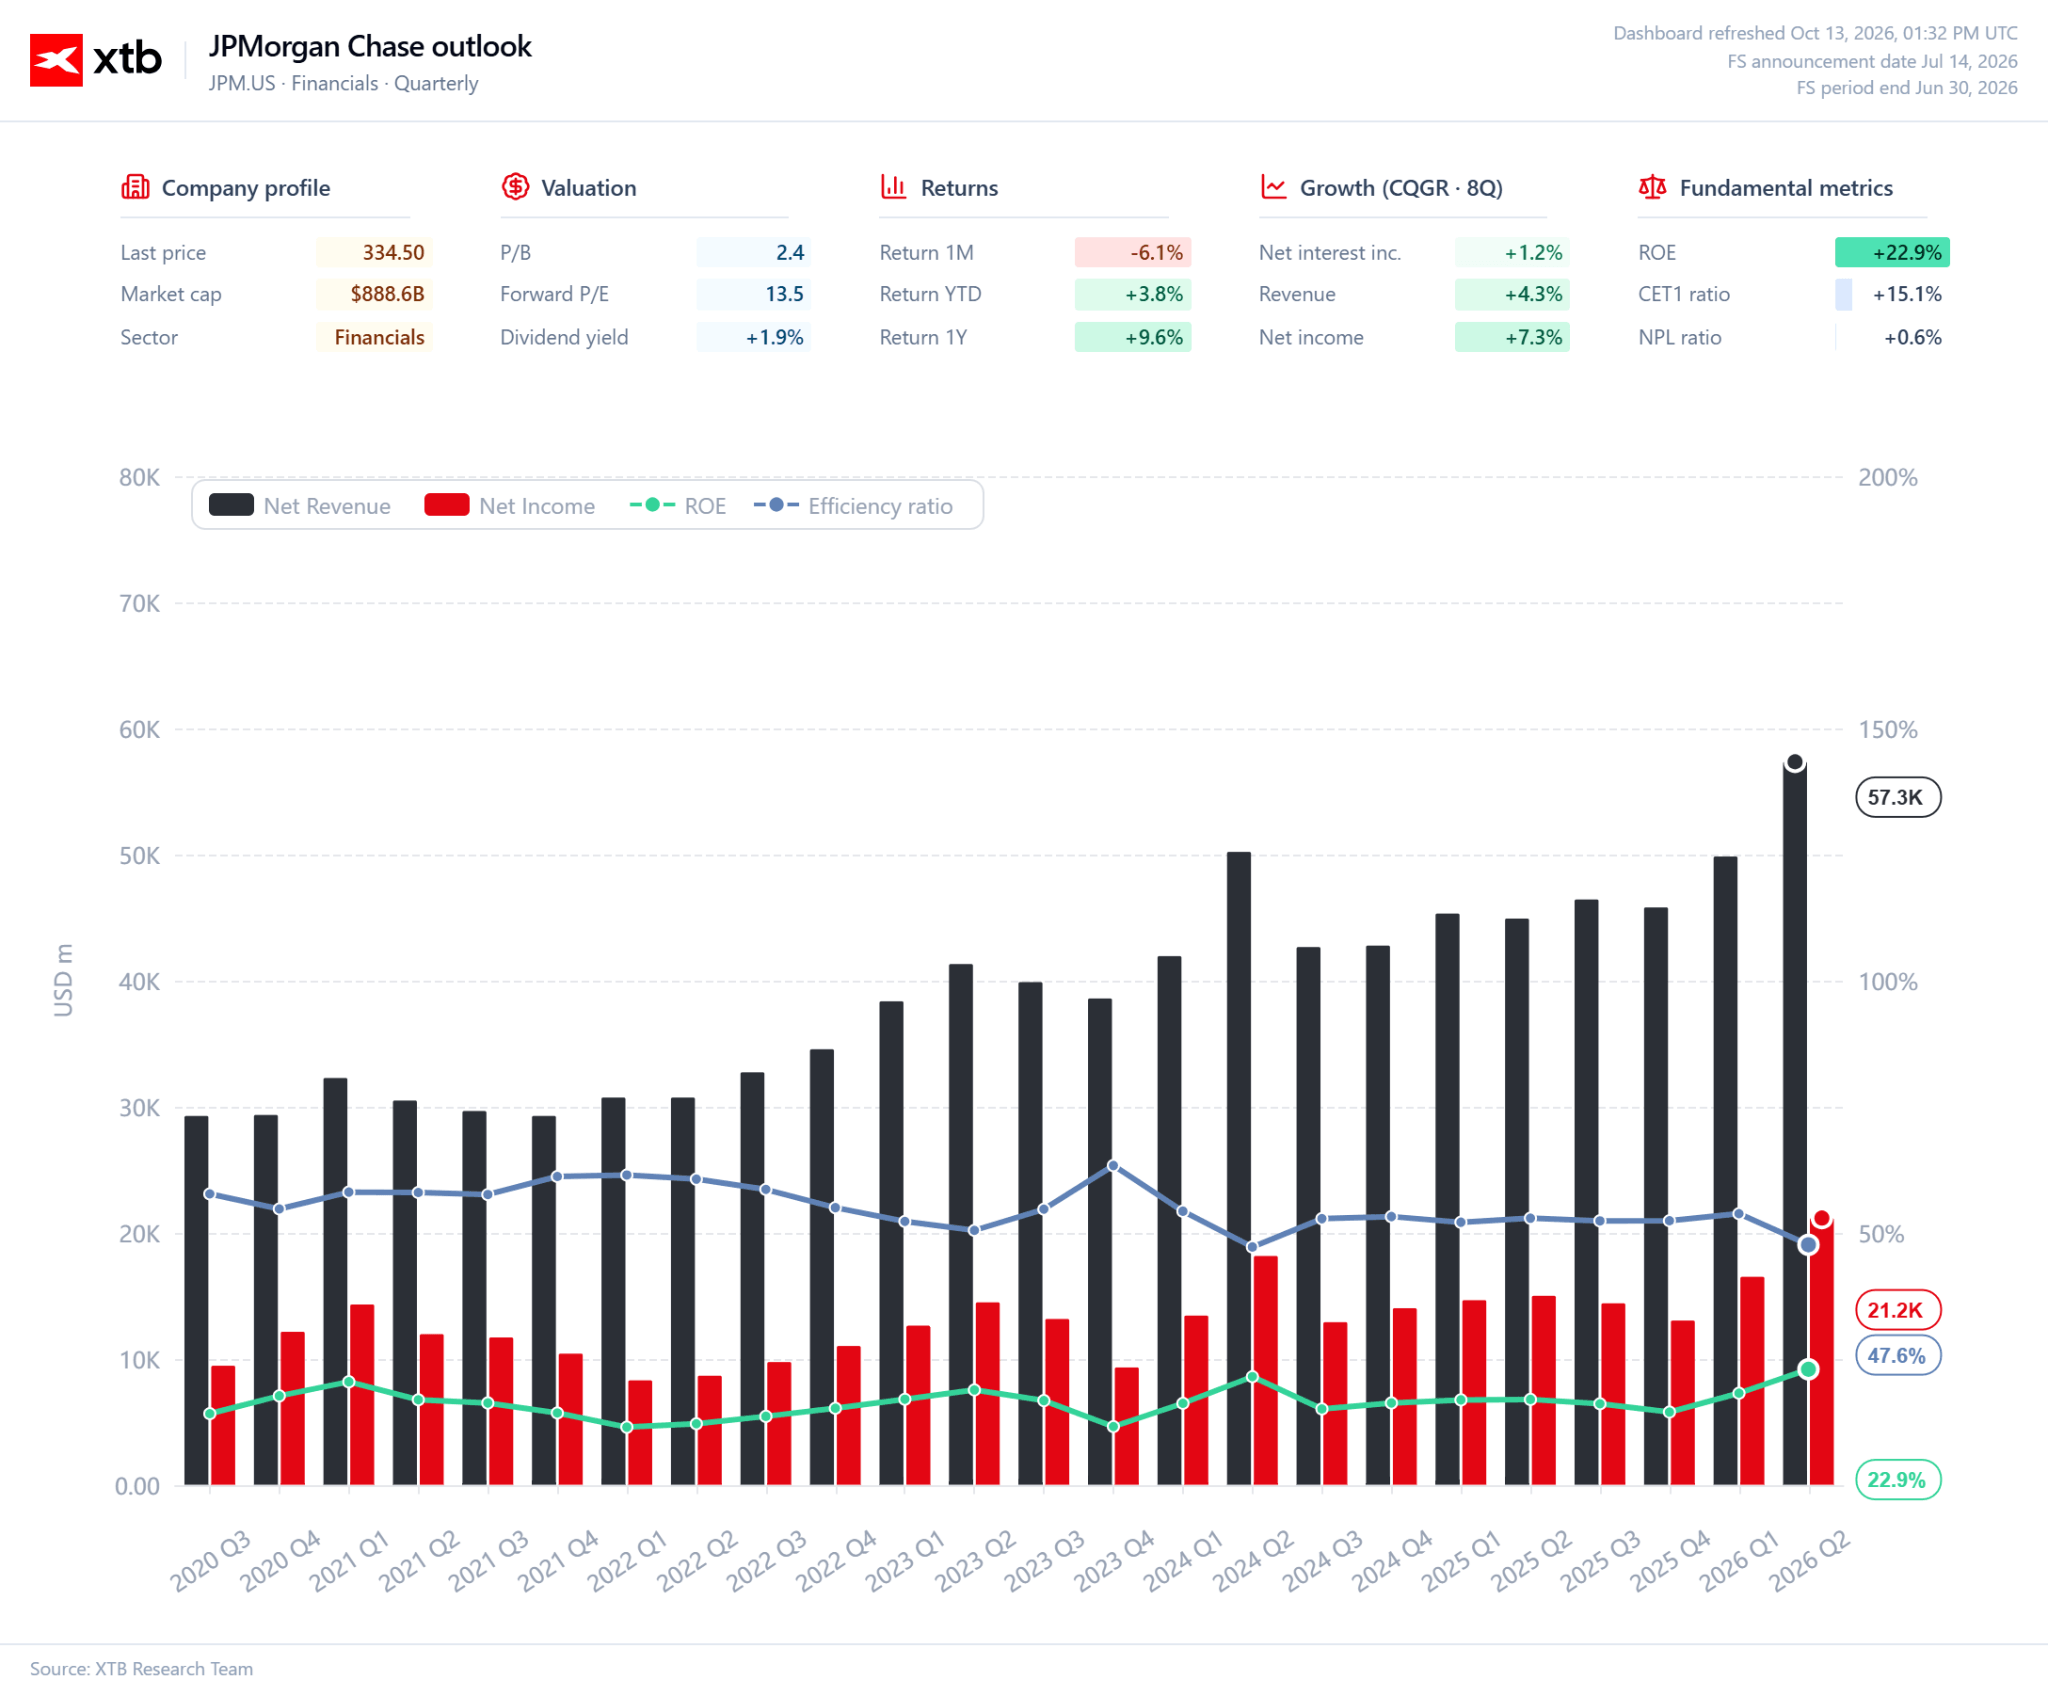
JPMorgan shares rebounded into positive territory (+0.5%) after an initial drop caused by weaker FICC results (Fixed Income, Currencies, and Commodities). Sentiment was boosted by an upward revision to full-year net interest income guidance, projected to increase by nearly $10 billion next year.
Figure 3: Dashboard for JPMorgan Chase (2021-2026)
 Source: XTB Research, 13.10.2026
Citigroup and Wells Fargo are currently trading more than 1% lower.
Despite a solid start to the earnings season, the banking sector remains in technical correction, with the iShares S&P US Banks ETF trading over 10% below its August highs.
For more details, please see Mikołaj Sobierajski's article titled "Goldman Sachs Shines, JPMorgan Surprises, and Wells Fargo Still Awaits a Breakthrough", now available on the platform.
Microsoft nears record highs
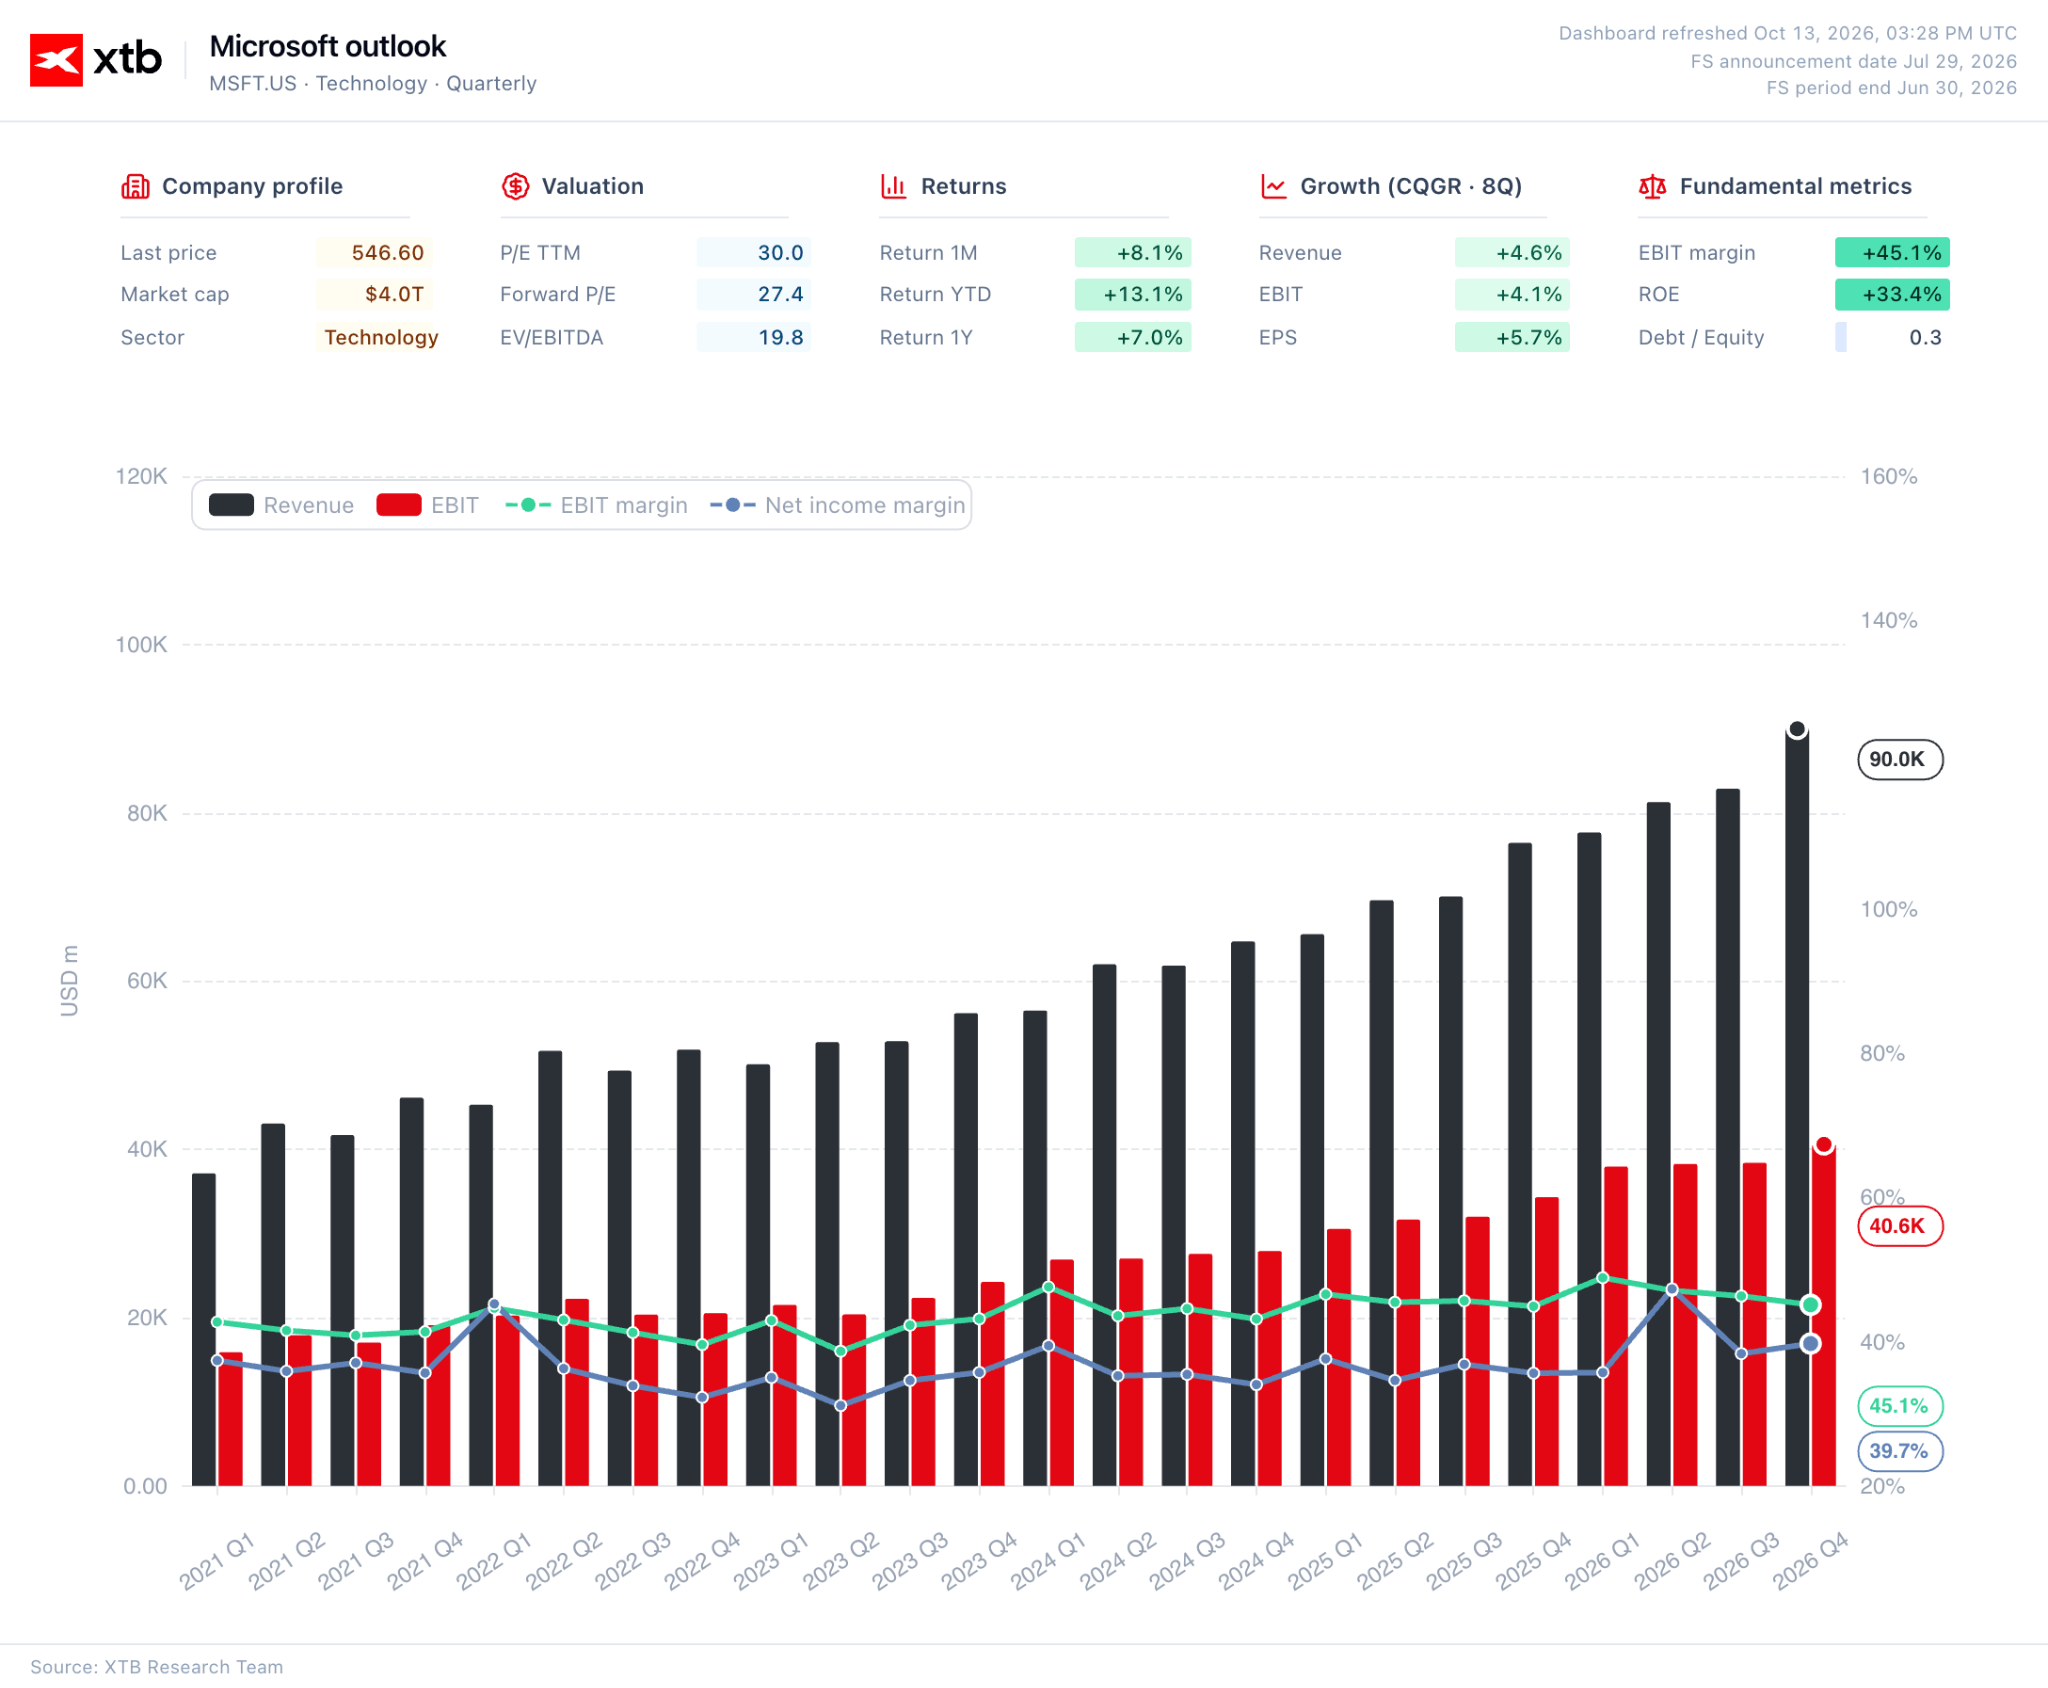
Shares of Microsoft gained over 1%, putting the stock on track for its first record closing high in nearly a year (the previous peak was reached in October 2025). The share price has surged over 50% from its June trough, adding nearly $1.5 trillion to the company's market capitalisation.
Figure 4: Dashboard for Microsoft (2021-2026)
 Source: XTB Research, 13.10.2026
Despite this impressive rally, Microsoft's year-to-date performance (+15.5%) is only slightly outperforming the S&P 500 (+14.5%) and lags behind the Nasdaq 100 (+21.5%). It also trails Meta (+18%), Apple (+28%), and Nvidia (+19%), placing it in the middle of the Magnificent Seven pack.
Corporate News
Fermi ($FRMI.US)
Shares in the energy company surged nearly 20% after securing a credit support agreement with AMD for the initial phase of Project Matador, a large-scale energy and infrastructure initiative.
VF Corp. ($VFC.US)
Shares of the apparel group behind Vans, The North Face, and Timberland recorded modest gains after Piper Sandler and Truist Securities upgraded the stock to a Buy rating. Market focus centers on the Vans brand, which is expected to reach a key turning point in the coming period.
Syndax Pharmaceuticals ($SNDX.US)
Shares in the biopharmaceutical firm dropped over 17%, marking their sharpest single-day decline since May 2025, following the discontinuation of clinical trials for a rare lung disease treatment. Axatilimab failed to meet its primary endpoints in Phase II trials.
Johnson & Johnson ($JNJ.US)
The healthcare giant lost nearly 6% following the release of its Q3 earnings report. While the company raised its full-year earnings guidance on strong demand for newer oncology and immunology drugs, performance in the medical devices division proved disappointing.
—
Michał Jóźwiak, Financial Markets Analyst at XTB



🖥️Chart of the Day - US100: Is the KOSPI crash a foretaste of Nasdaq's troubles?



Morning Wrap: Tech Crash in Asia and Hawkish Central Banks in the Shadow of an Oil Shock (13.10.2026)


Morning Wrap: Oil cheaper despite attacks on Saudi Arabia, markets await CPI (12.10.2026)


Daily Summary: A Shallow Rebound Ahead of Earnings Season
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.